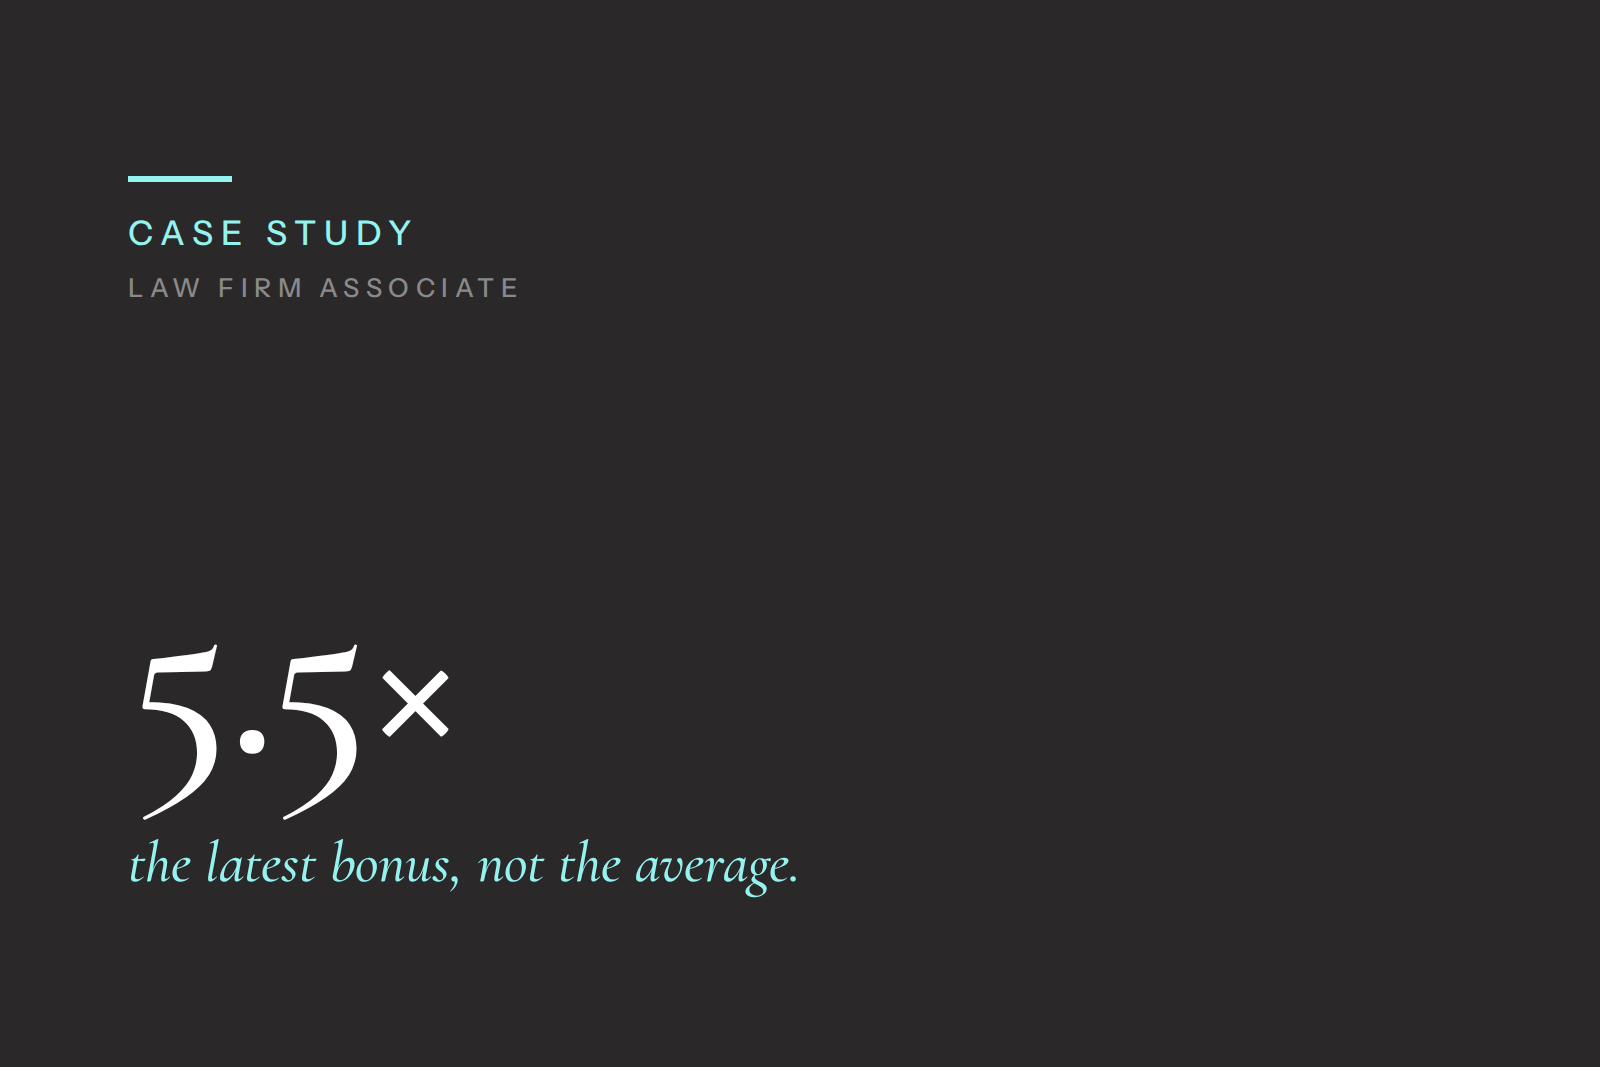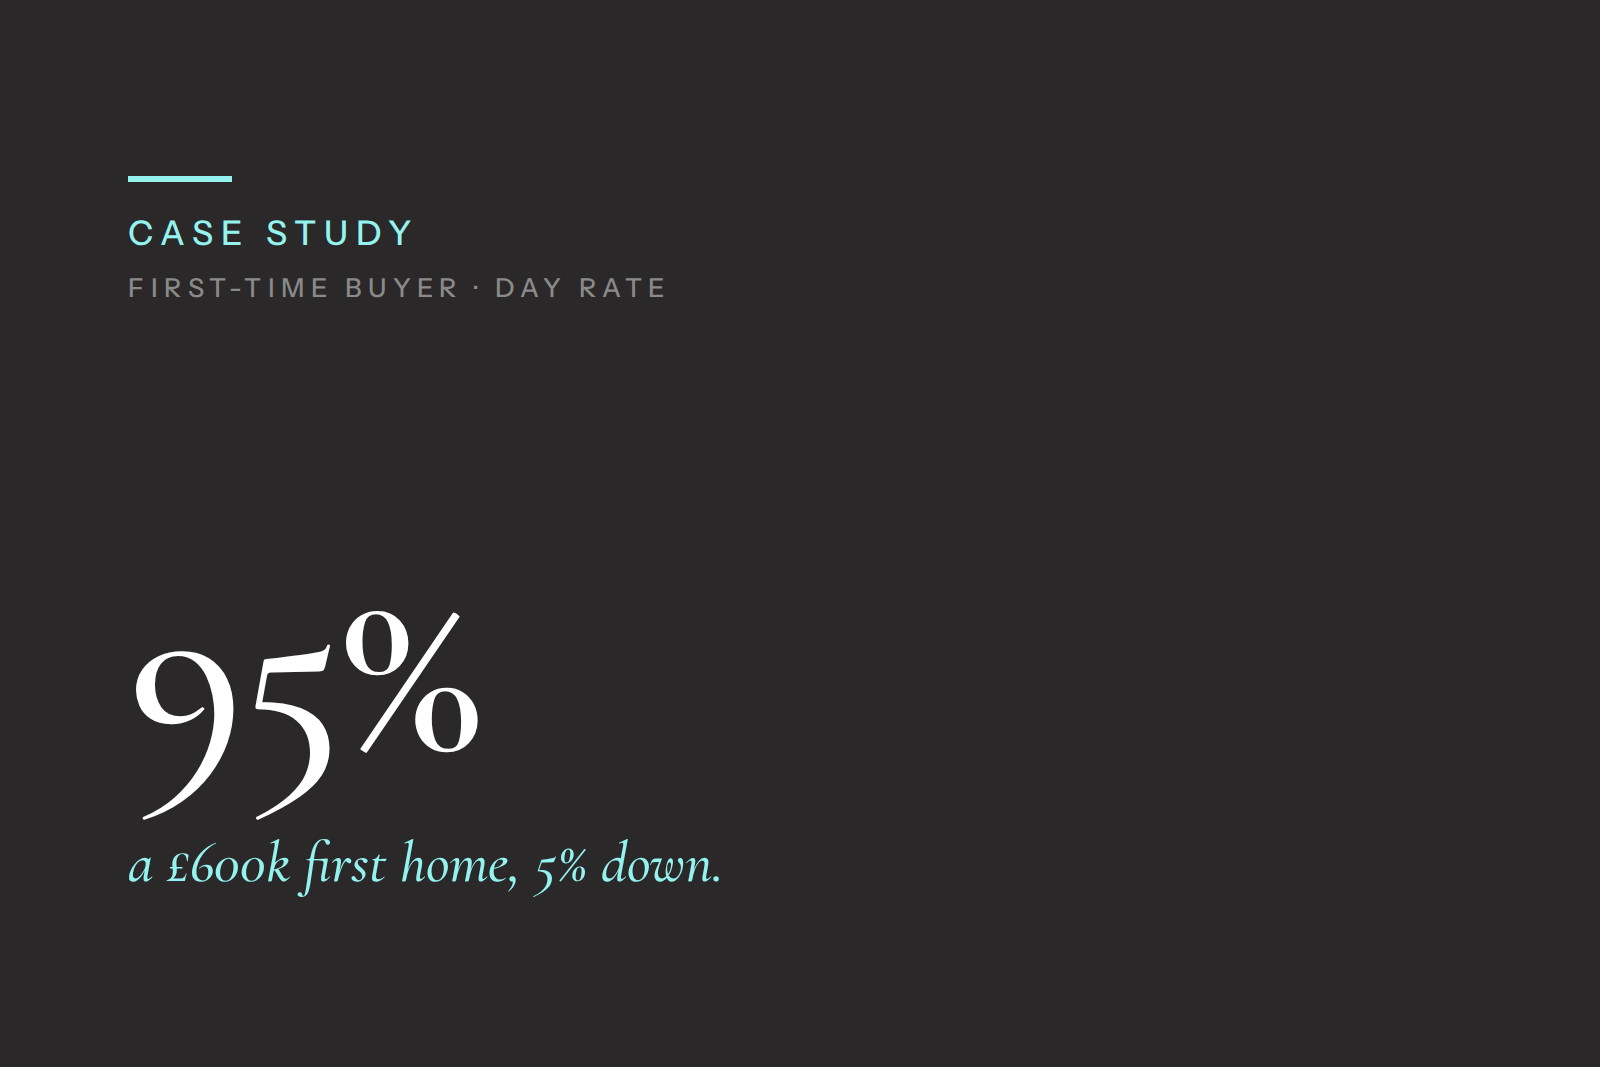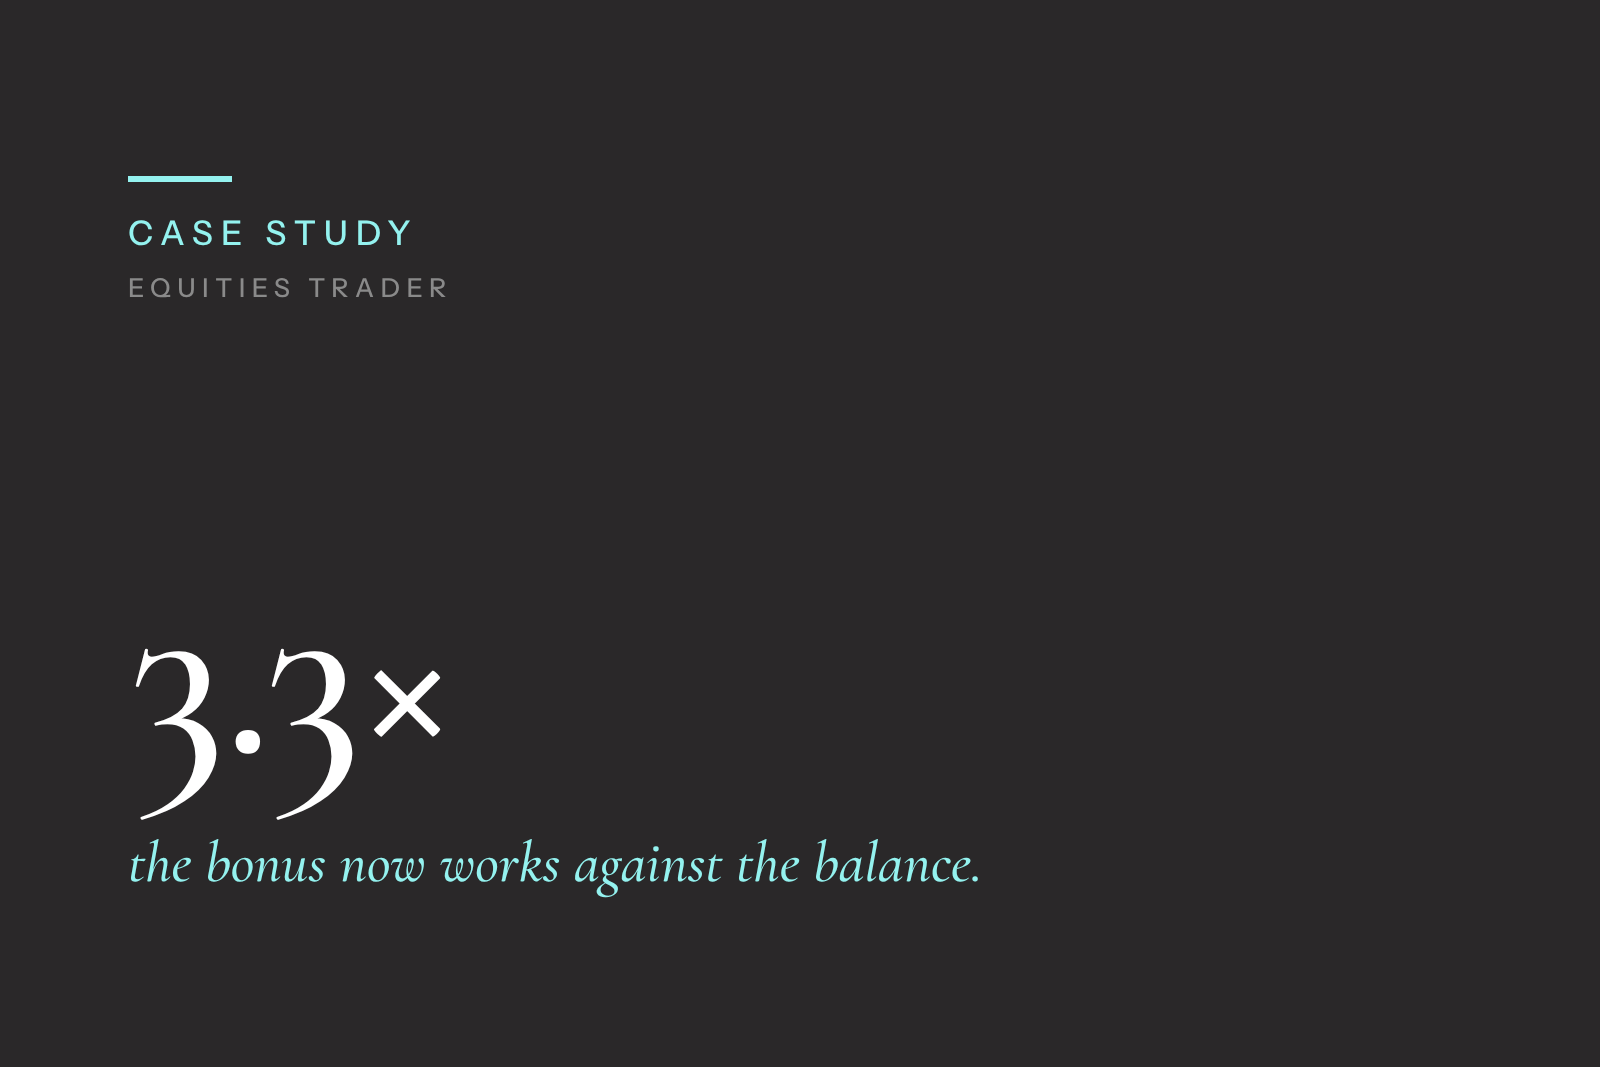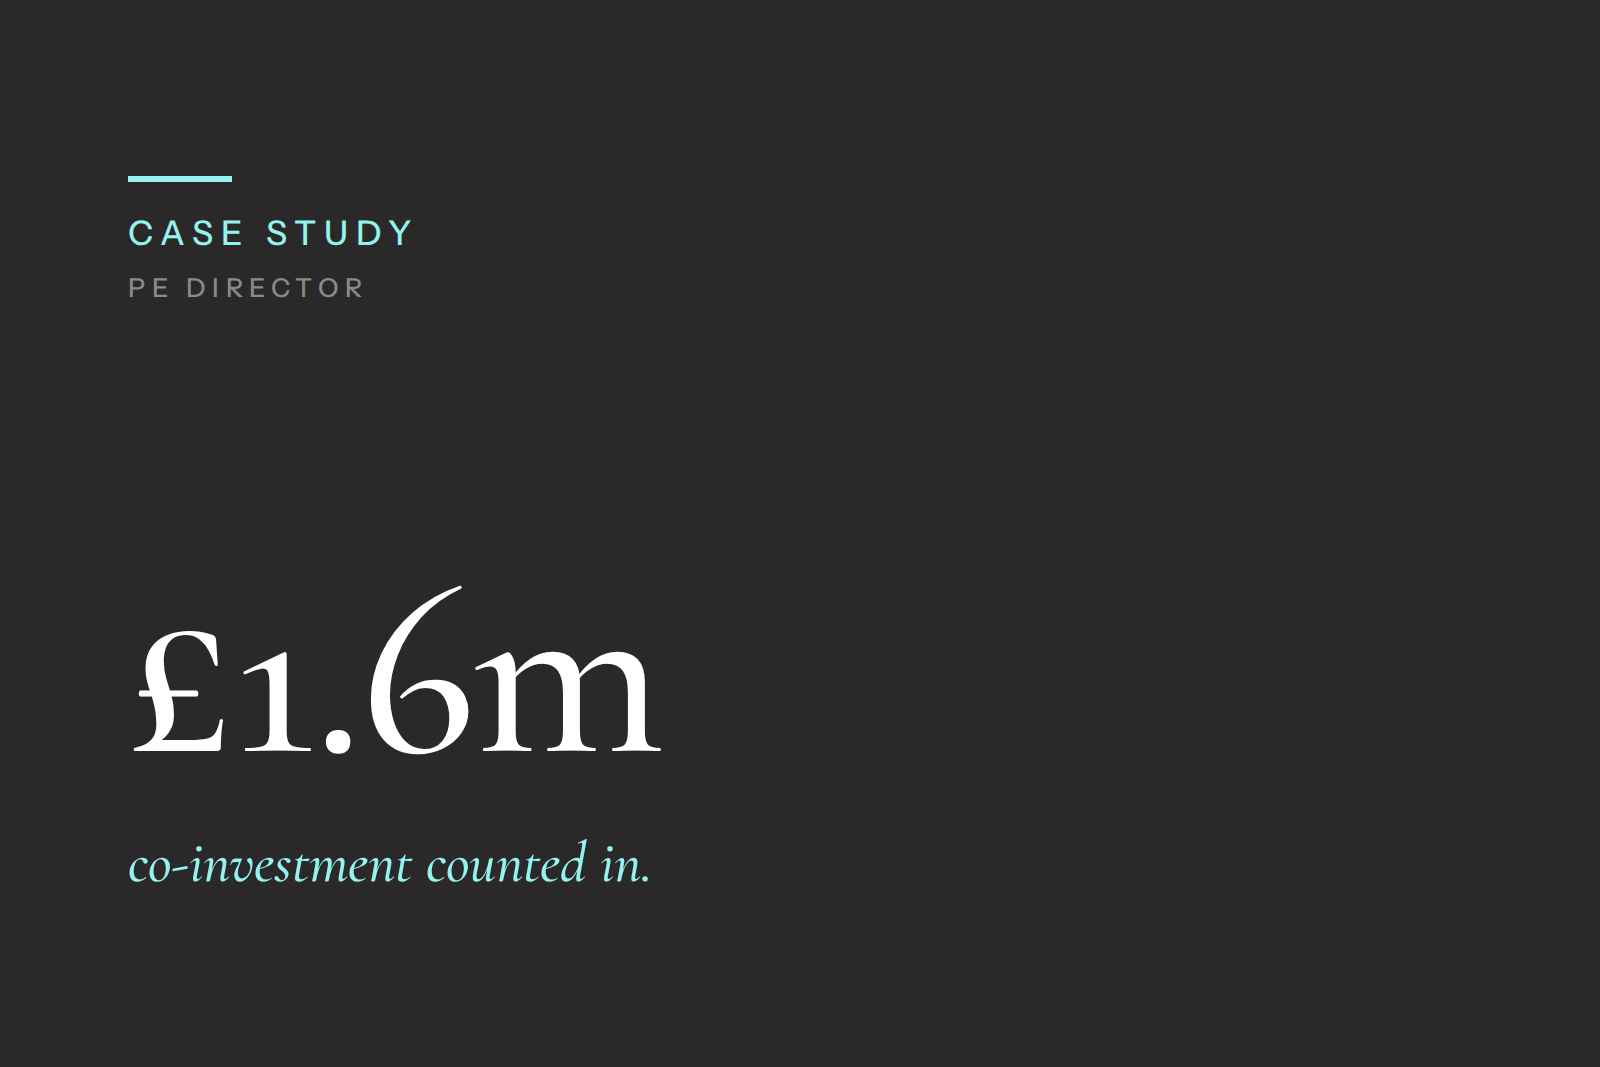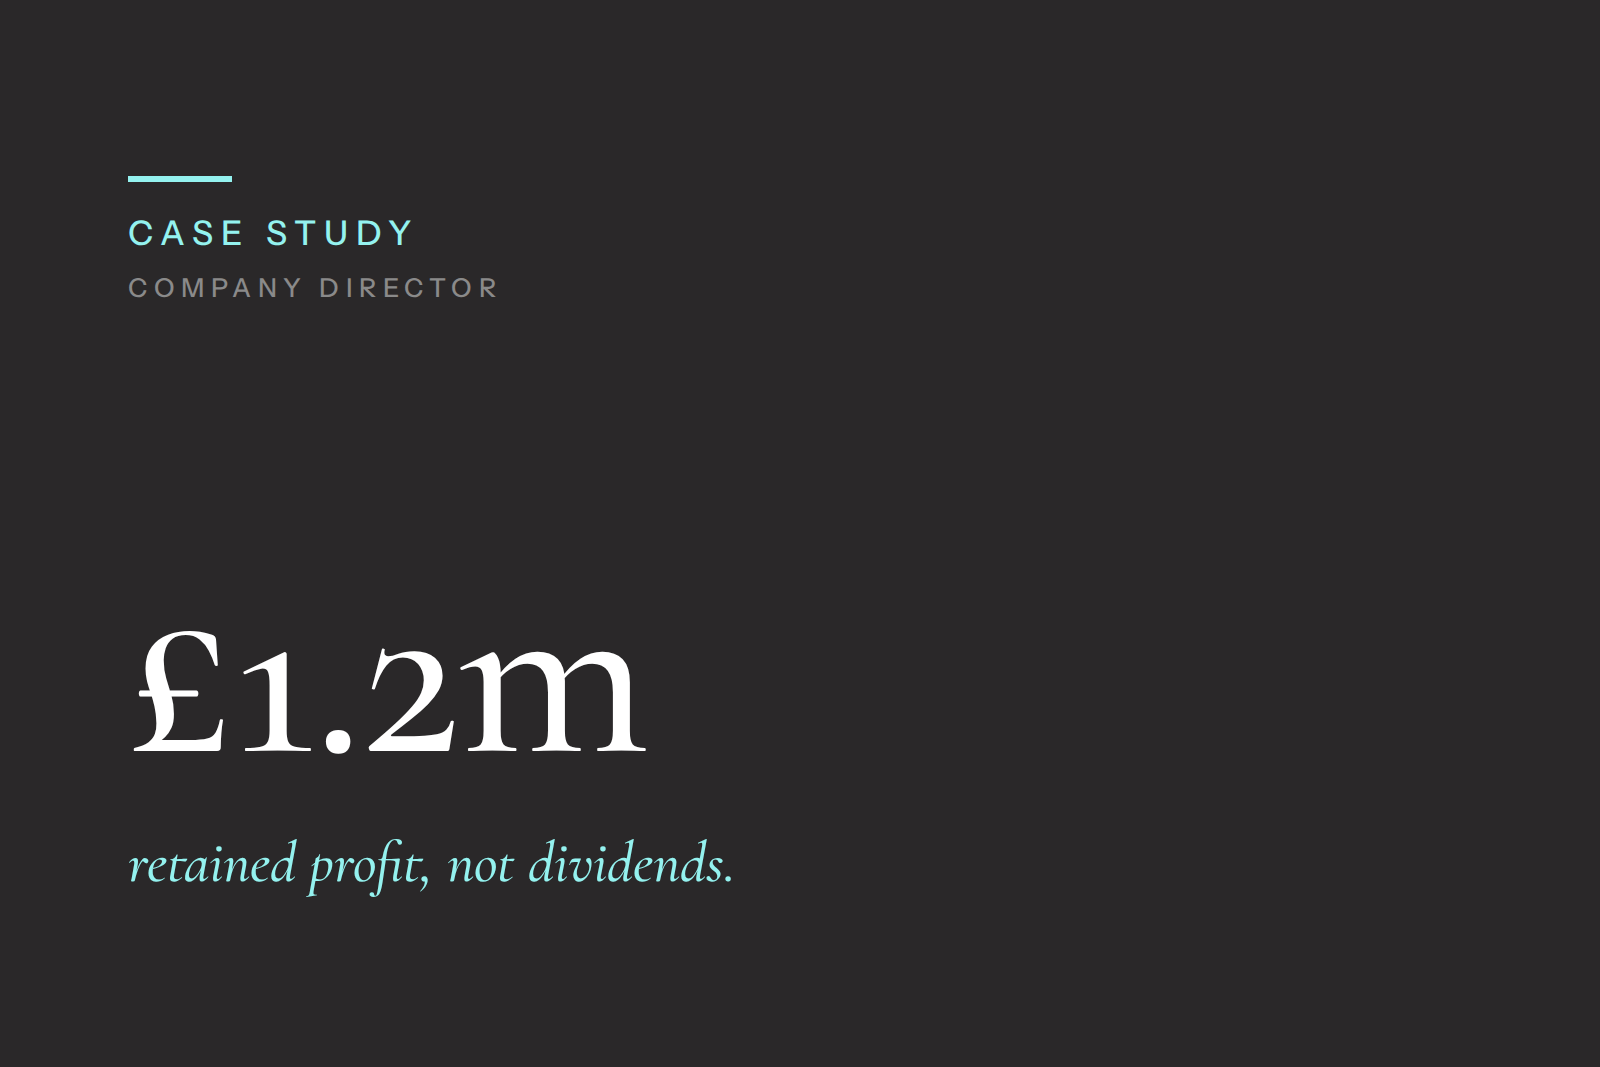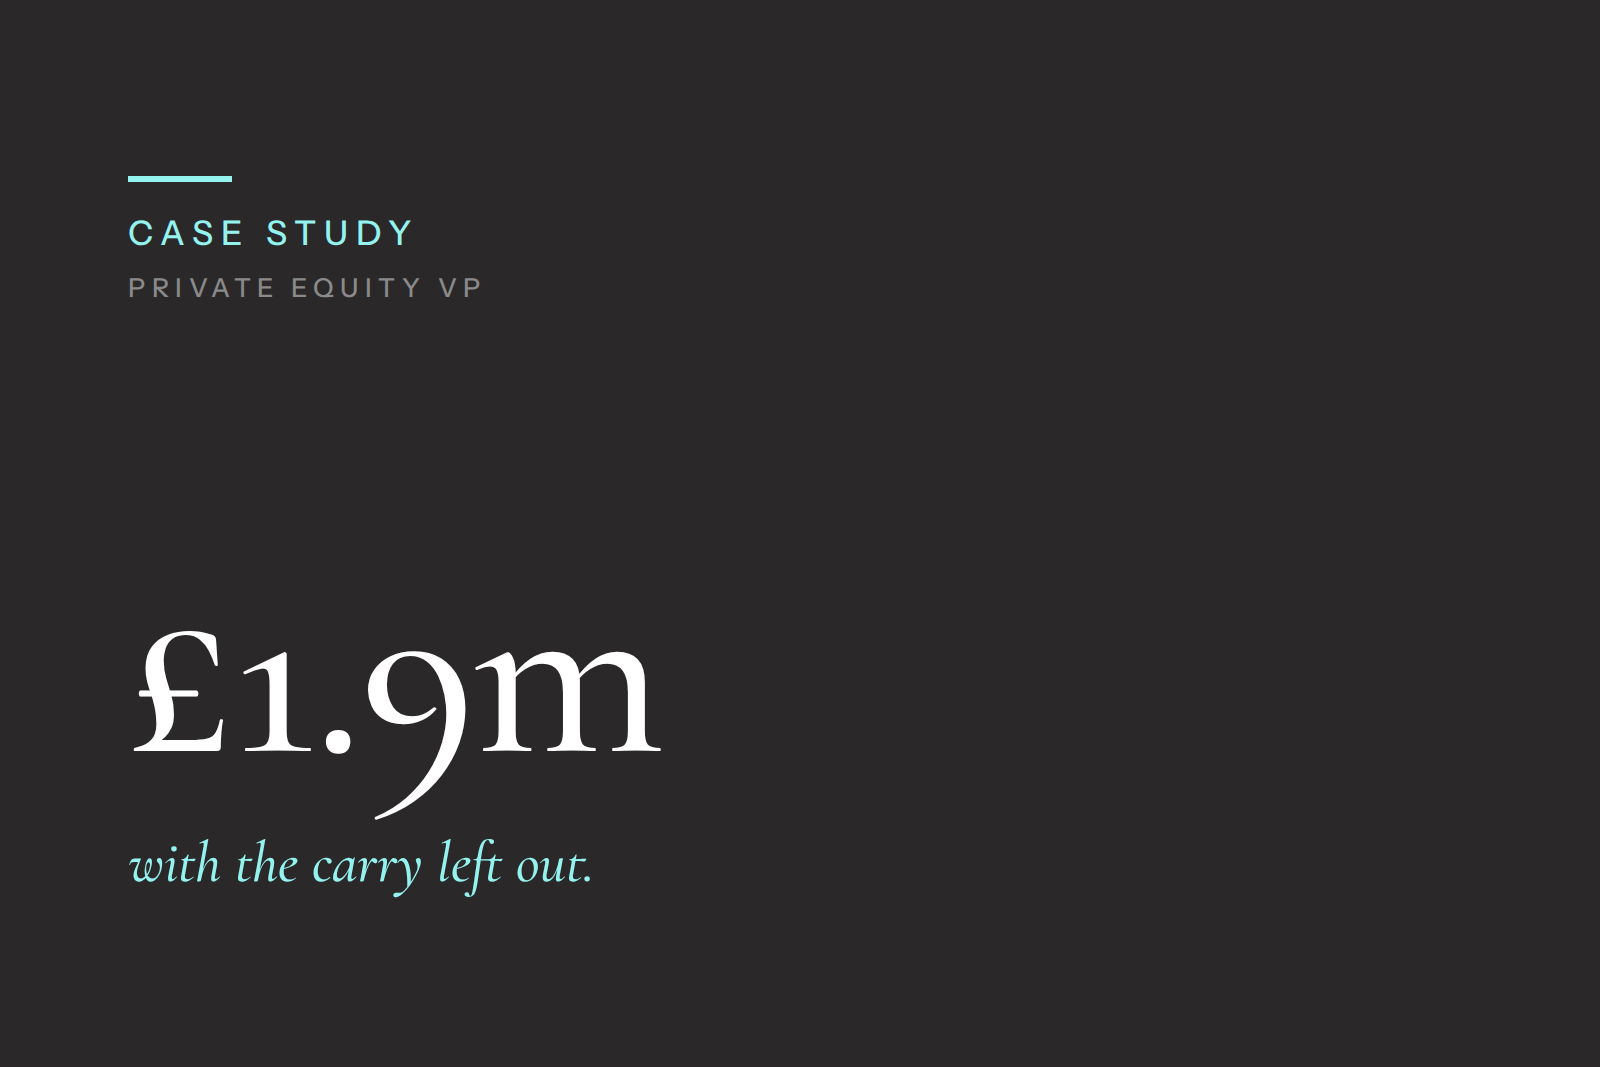
DIRECTOR AND MORTGAGE ADVISER
Specialist broker for high-earning professionals and complex income cases.
Contractors and business owners live with lumpy months, tax deadlines and working capital needs. An offset mortgage can turn that cash volatility into lower interest and more breathing room—without locking money away. Here’s the practical guide, with worked examples and guardrails.
Offset For Contractors And Self-Employed: Smoothing Irregular Cashflow
An offset mortgage links your savings to your mortgage. Contractors and self-employed borrowers can park tax reserves and personal savings against the loan, cutting interest while keeping cash accessible. This smooths irregular cashflow, reduces total cost and protects liquidity.
Important: Offset balances must be held in the borrower’s personal accounts (names matching the mortgage). Company cash reserves cannot be linked to a personal residential offset.
Who This Guide Is For
Day-rate contractors, freelancers, sole traders, limited-company directors and LLP partners who hold meaningful personal cash balances (tax set-asides, savings, drawings waiting to be used) and want flexibility without committing to overpayments.
Request your fee free mortgage consultation today. No obligation, just sound advice.
How An Offset Mortgage Works (In Two Lines)
Your savings sit in linked accounts. Lenders charge interest on mortgage balance minus savings balance each day. You can withdraw anytime; interest adjusts automatically. You can target lower payments, faster payoff, or a mix.
Why Offset Suits Irregular Income
Keeps cash liquid: Use funds for tax bills, gaps between contracts, equipment—no redemption or overpayment clawbacks.
Interest savings every day: Even short-term balances (e.g., VAT/self-assessment set-asides) reduce interest during that period.
Cashflow smoothing: Choose lower monthly payments (where policy allows) or keep payments level and shorten term.
Stay organised: Use separate personal sub-accounts for Emergency fund, Operating buffer, and Tax reserve (where the product allows).
Lender Basics For Contractors & Self-Employed (Offset Edition)
Eligibility: Offset products exist with both repayment and interest-only/part-and-part structures.
Income assessment:
Day-rate contractors: Common method = day rate × 5 × 46 weeks, subject to history and gaps.
Self-employed/LLP: Usually 2 years’ accounts/SA302s (some may use latest year if trending positively).
Affordability: Some lenders may credit a portion of variable income (bonus/dividends/retained profit) with evidence.
Loan-to-value (LTV): Pricing steps at 60/75/80/85% are typical; lower LTV often unlocks sharper offset pricing.
Currencies: Income is generally assessed in sterling; foreign currency income is often discounted before affordability.
Professional/complex cases: Private banks may consider bespoke offset-style solutions for large loans or multi-income profiles (still personal funds only for offsetting).
How We’ve Helped Clients Like You
These clients faced similar challenges - here’s how we helped them secure the right deal.
Three advisers read her as self-employed: two years of £45 to 60k drawings, capacity under £270k. Her 22% post-round stake put her below some lenders' ownership line. Assessed as an employee on a £180,000 board-set salary, she borrowed £770,000 at 4.3x.
She expected the structuring she had seen partners need. Her pay was a £120k base and a cash bonus. Half the two-year bonus average counted, recognised income was £157,500, and a top-five clearing bank lent £680,000 at 85% LTV on its standard range at 4.3x.
Buy the townhouse, renovate for a year, then move and sell the flat. Base salaries supported £1.39m; the plan needed £1.725m across two loans. Full bonus recognition made it 4.2x, with a no-ERC tracker on one side and an offset catching the proceeds on the other.
His RSUs were worth £400k on paper and nil to a lender until the listing. The £1.1m purchase stood on a £210k base at roughly 5.2x, on a tracker with no early repayment charges. After the listing £300k went into the balance without penalty, and £800k was fixed at 55% LTV.
His private bank facility had done its job five years ago. At renewal it still asked for £500,000 of his assets to stay with the bank. Refinanced interest-only at 60% LTV with a clearing bank's large-loan team, at 4.4x recognised income, the condition ended.
Paid CHF 480,000 in Zurich, living in Twickenham, mid-fifties: three reasons most lenders hesitate. One high street lender counted the converted £428,500 in full and refinanced £730,000 over a 14-year term, with unlimited overpayments to finish early.
A Big Tech Principal Engineer whose base had sat at £200k for three years needed £1.3m for a £1.75m Sevenoaks home. A building society counted half of his latest twelve months of vested RSUs, recognised £290,000 of income and lent at roughly 4.5x.
Four months into partnership, paid entirely in USD, and needing £2.48m at 80% LTV. An international bank’s large-loan team worked from the firm’s own schedule, applied no currency haircut and recognised £550,000 of income, roughly 4.5x.
An M&A associate had just moved banks with a £60k sign-on and a £90k guaranteed bonus. Neither counted. Her first home, £930k on a £1.1m Earlsfield house at under 85% LTV, was placed at 6x her £155k base salary alone.
Standard bonus averaging supported £791,000; the buyout needed £1.24m. A clearing bank recognised £235,000 of income, the full latest bonus, and lent at roughly 5.3x, keeping her in the family home and her former partner’s share released in full.
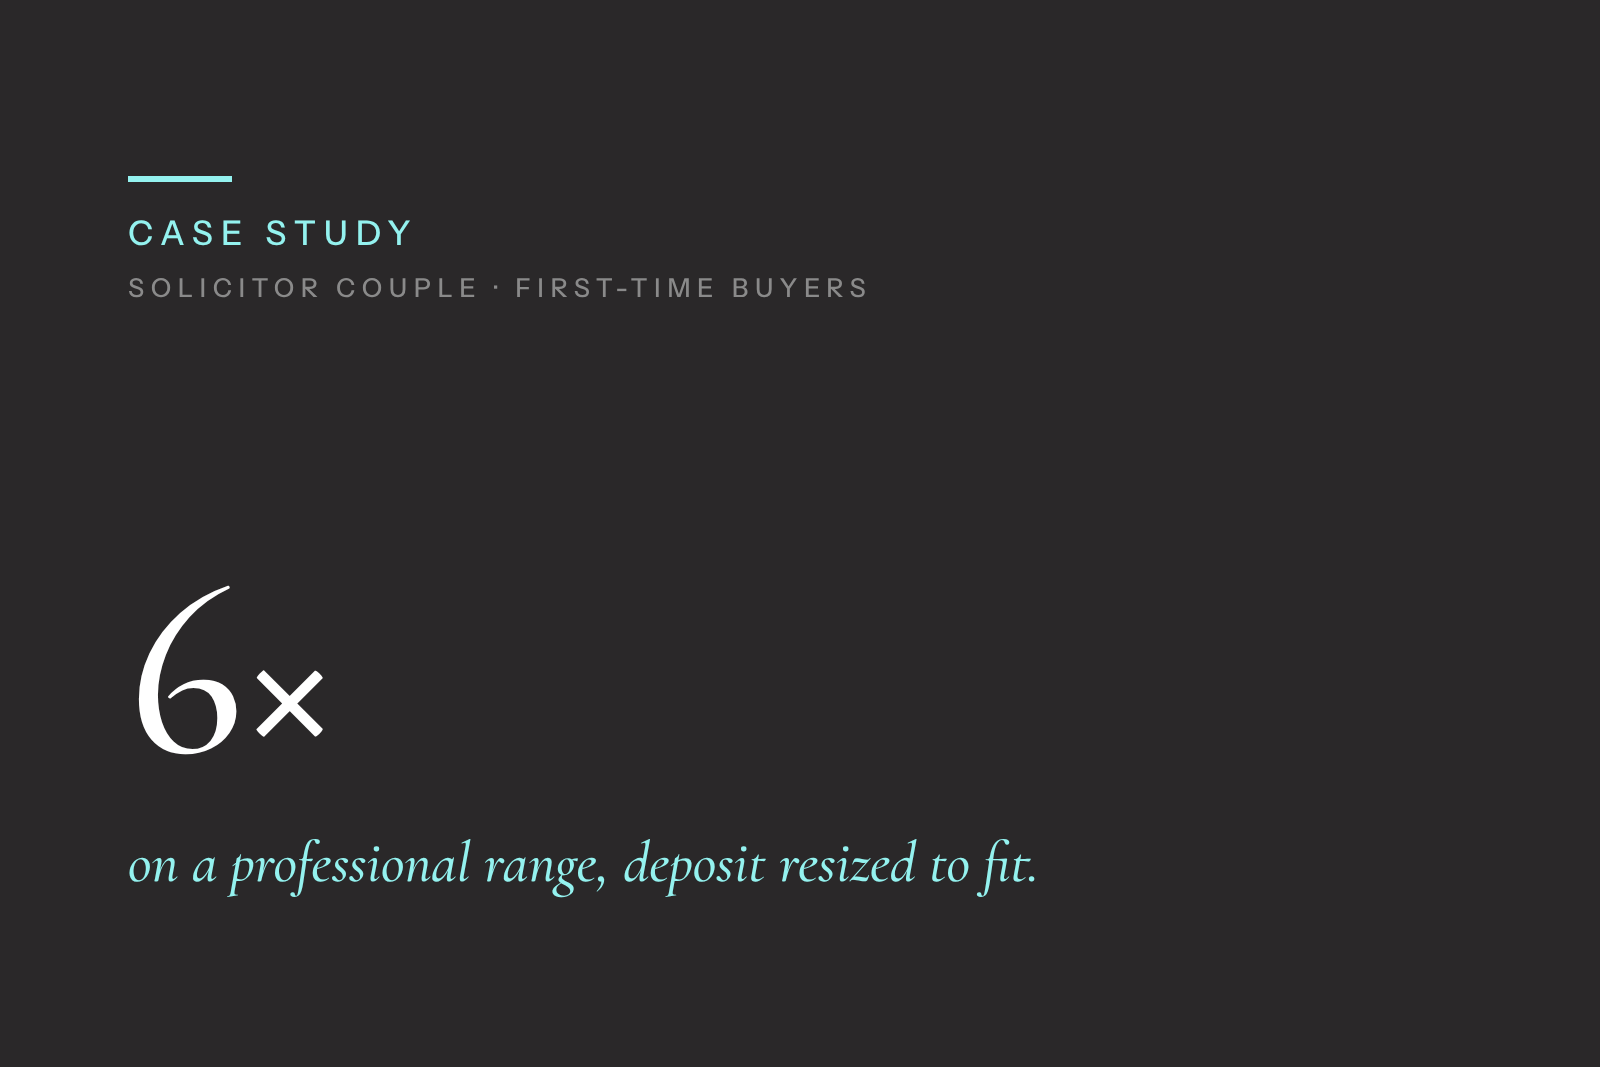
Two solicitors on £242,000 of combined basic salary needed £1.45m for a £1.725m St Albans house. At 4.49x and 5.5x they fell short. A professional range at up to 6x lent the full amount at 84% LTV, once the deposit was resized to fit the band.
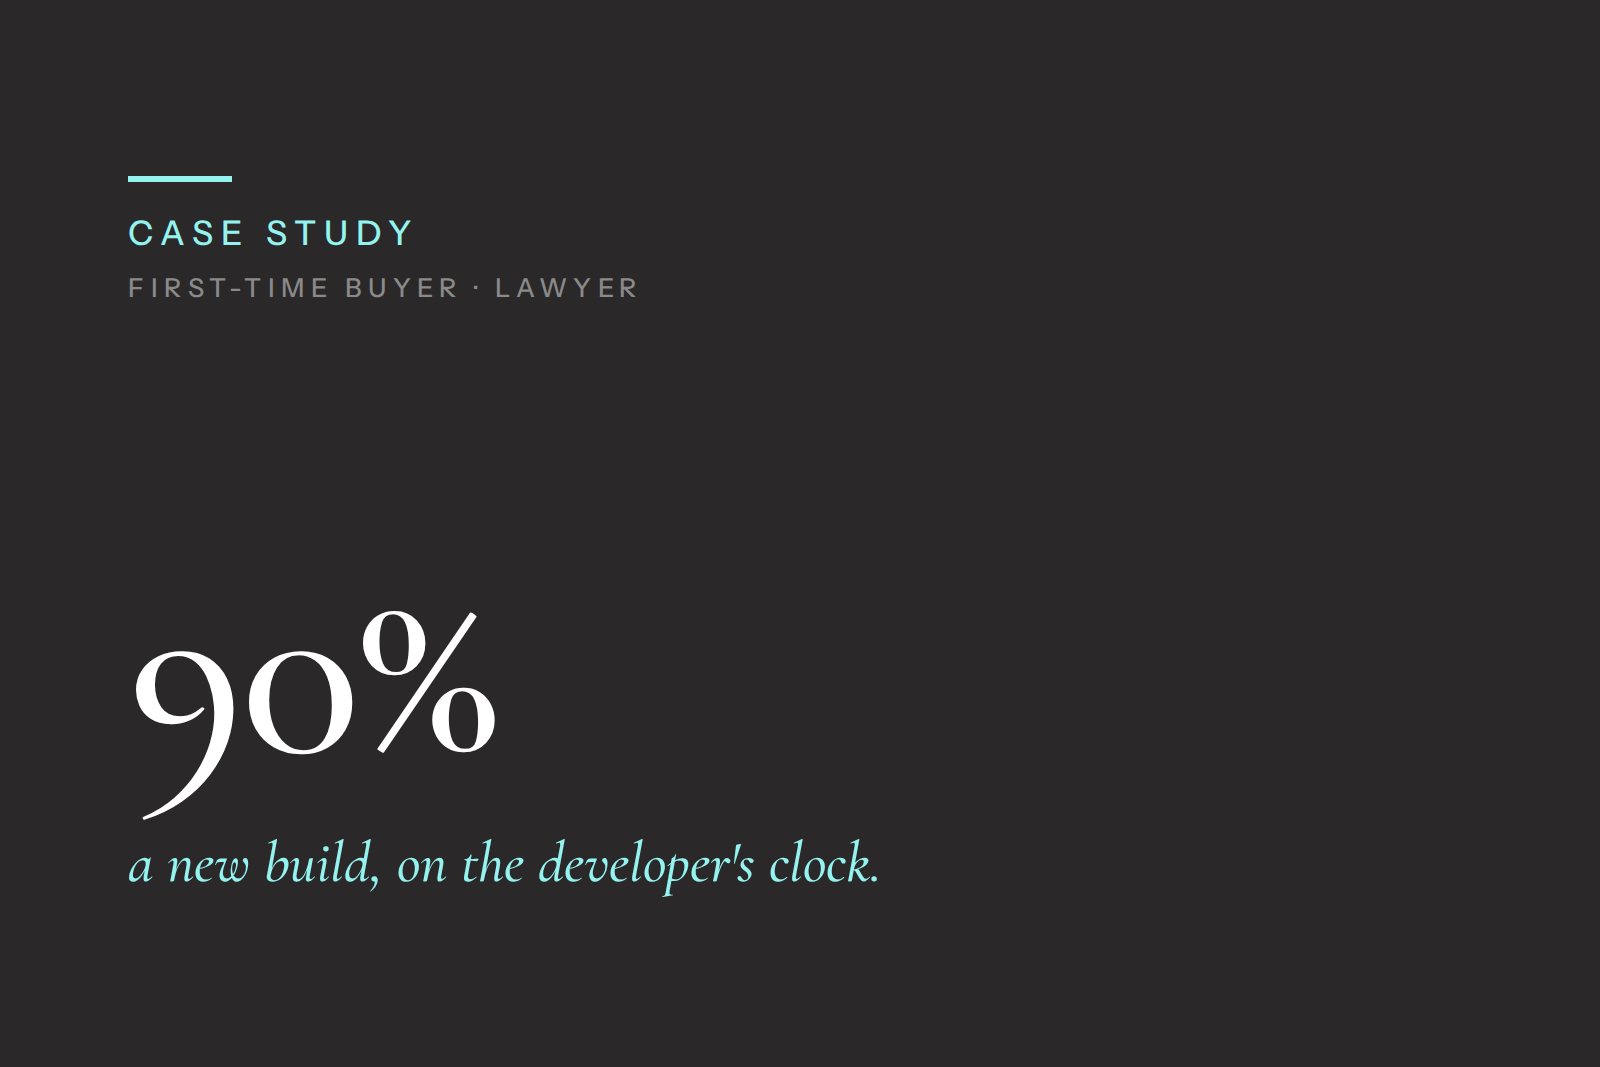
Half his deposit was a developer incentive and he had received one bonus. A high street lender accepted both — £157,500 of recognised income, £675,000 at 90% LTV, roughly 4.3x, with a new-build offer that flexes to the completion date.
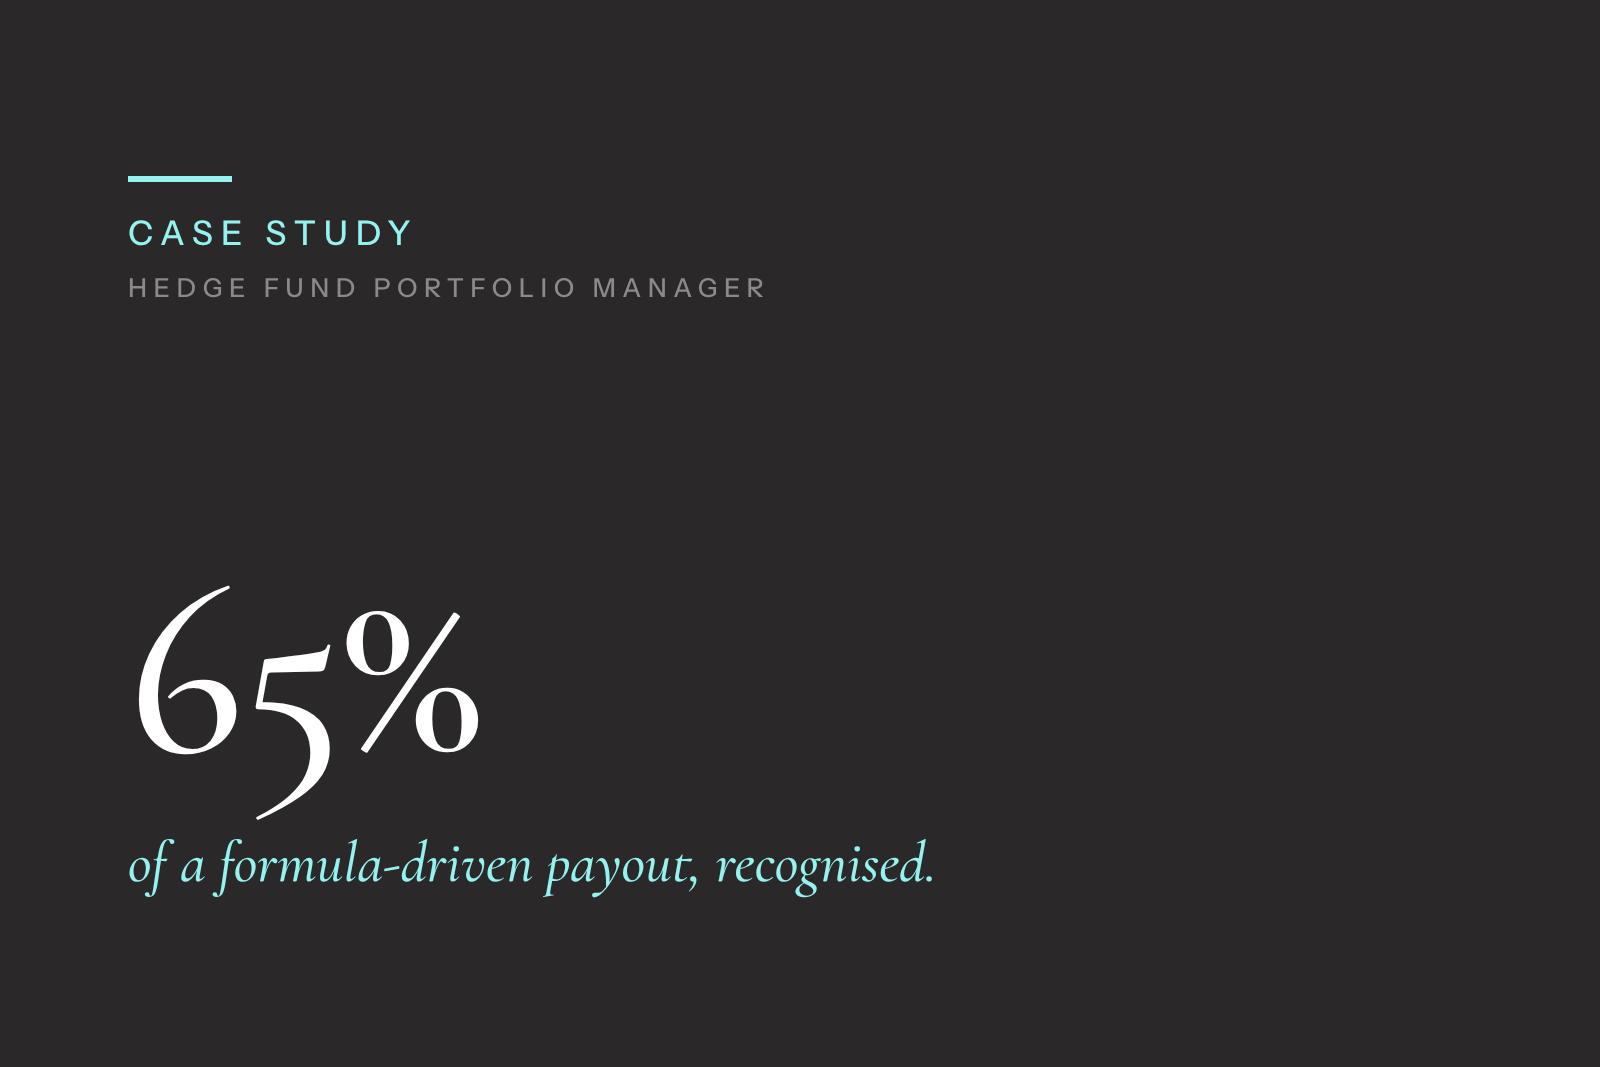
A hedge fund portfolio manager on a £180k base, paid a fixed share of his book’s performance fees, needed £2.4m interest-only on a £3.25m home. A clearing bank’s large-loan team recognised £453,000 of income and lent at roughly 5.3x.
Told to wait two years for accounts, a software developer on a £575 day rate bought his first home instead. A high street contractor policy annualised the rate to £132,250 and lent £570,000 at 95% LTV, roughly 4.3x, with his renovation fund intact.
An equities trader on a £160k base and a £200k average annual bonus was ending a fix on an £850k mortgage against his £1.2m London home. A remortgage to a clearing-bank offset product recognised £260,000 of income at roughly 3.3x — and each bonus now works against the balance from the day it lands.
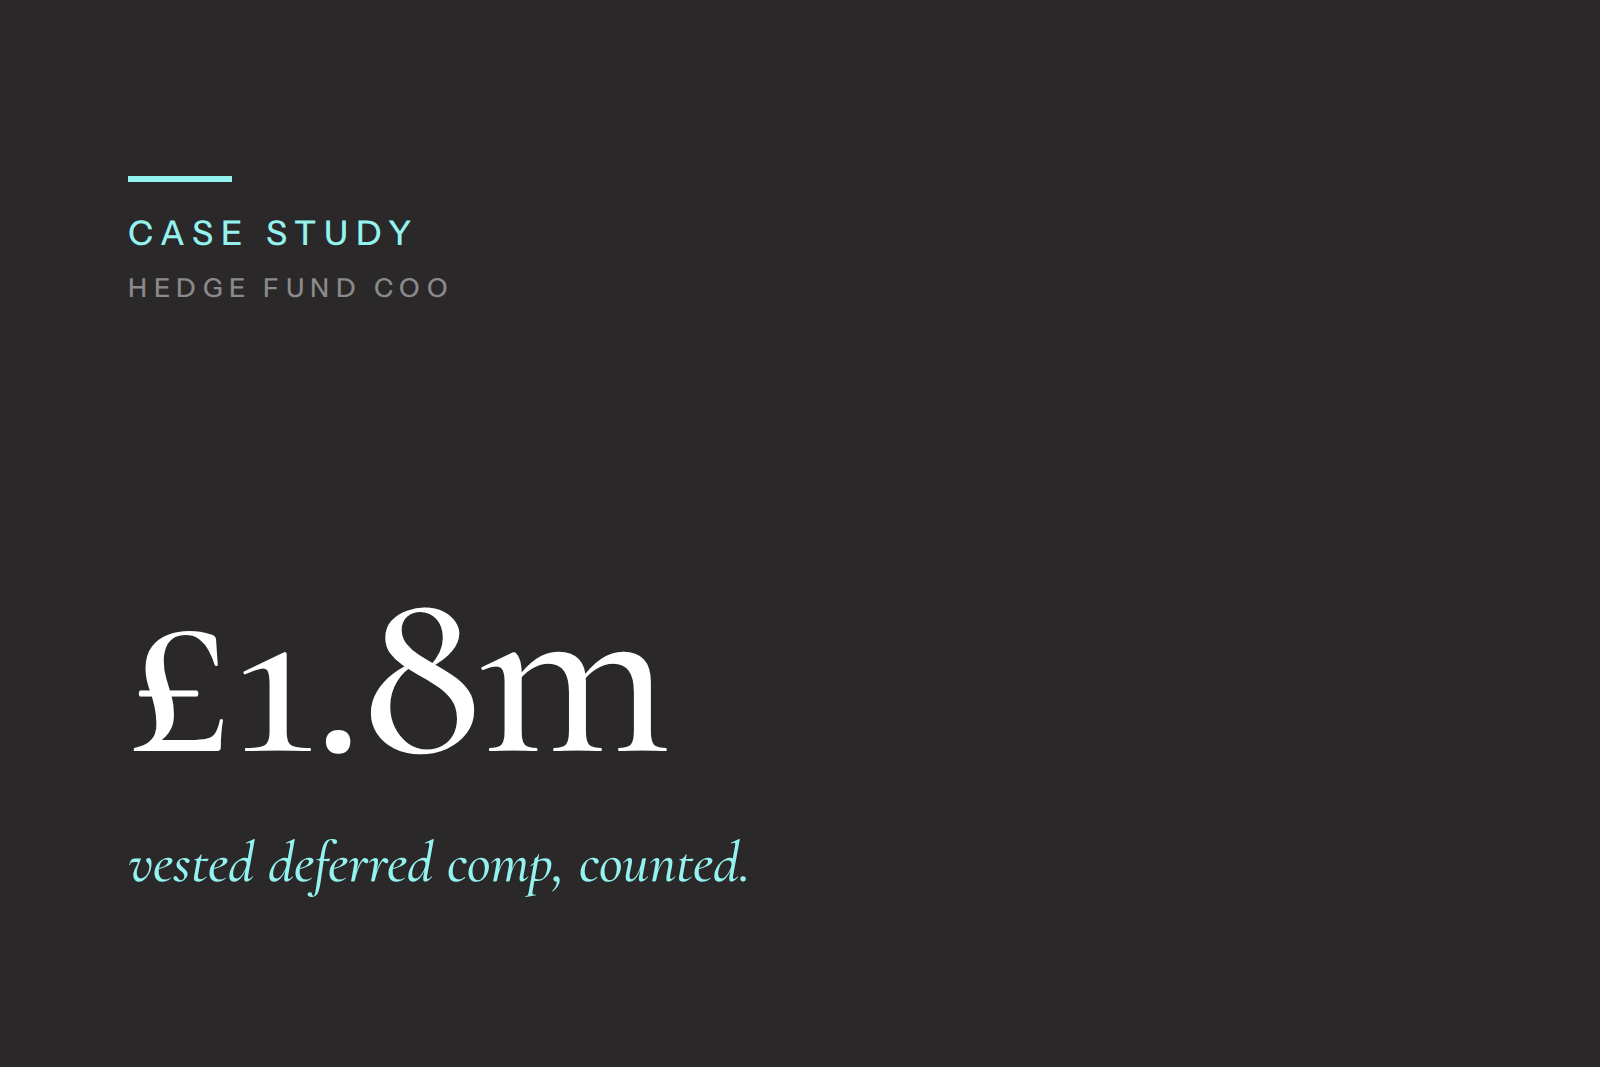
A hedge fund COO with half his bonus deferred needed to refinance £1.8m on a £2.5m home before his fix expired. A clearing bank counted the vested tranches paid through payroll, recognising £400,000 of income, and the remortgage completed at 4.5x.
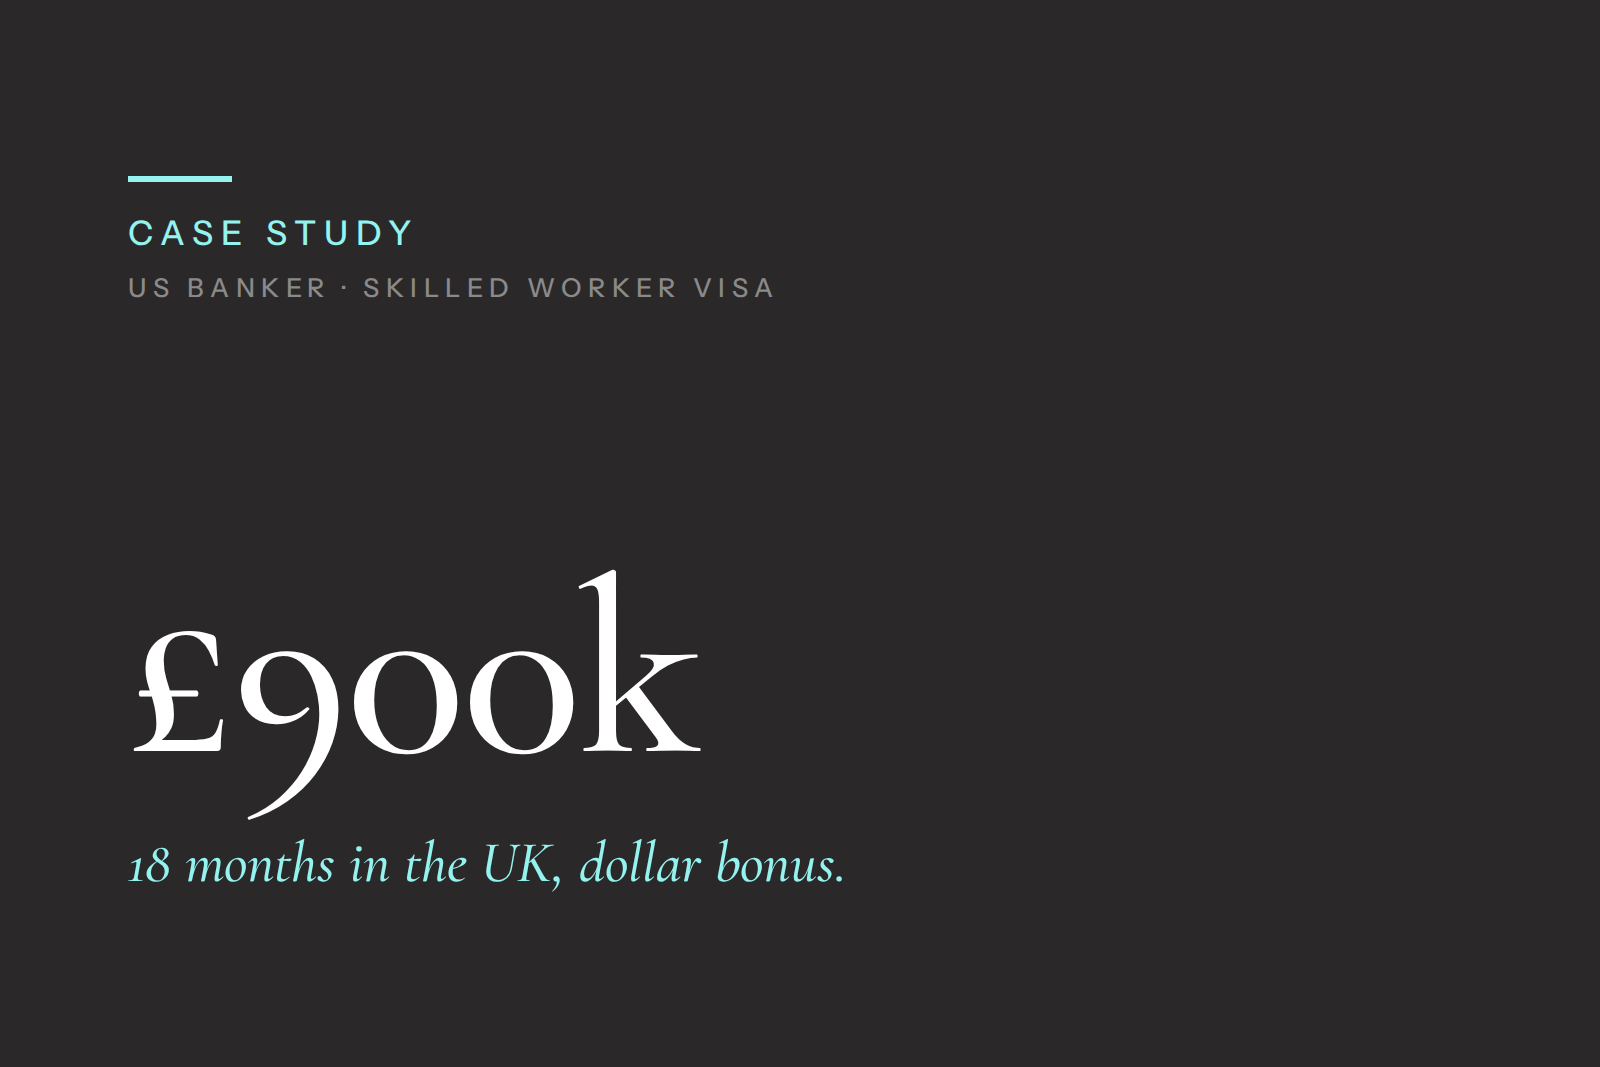
An American VP on a Skilled Worker visa, 18 months into a London posting, needed £900,000 for a £1.2m house. A large international bank whose criteria let income override residency recognised £238,400 including his USD bonus; completed at 75% LTV.
A PE Partner refinancing £2.4m on a £3.2m home saw mainstream calculators read his carry as zero. A holistic underwrite credited a smoothed share of four years of distributions and the refinance completed interest-only at 4.8x recognised income.
A macro trader earning a £200k base with a bonus that swung between £180k and £420k needed £1.7m for a £2.3m family home. A clearing bank averaging three full years recognised £386,000 of income and agreed the loan interest-only at roughly 4.4x.
A hedge fund analyst on a £150k base needed £1.1m for a £1.4m home after his bonus fell to £120k from £270k. A lender applying 60% of a two-year average recognised £267,000 of income, and the loan completed at roughly 4.1x with the deposit unchanged.
An operating partner at a mid-market buyout firm needed £1.3m on a £1.7m home, with income spread across fixed drawings, board fees and a volatile profit share. Built on the stable layers at roughly 4.4x, it completed on mainstream large-loan terms.
A mid-market PE director needed £1.6m for a £2.1m home; salary and bonus reached £1,425,000 at most. A private bank recognised three years of crystallised co-investment gains, taking recognised income to £375,000 and the loan to roughly 4.3x.
A sole director drawing £90k while his company retained its profit needed £1.2m of borrowing. A lender assessing salary plus share of net profit after corporation tax recognised £267,570 of income, and the loan completed at just under 4.5x with no change to his dividends.
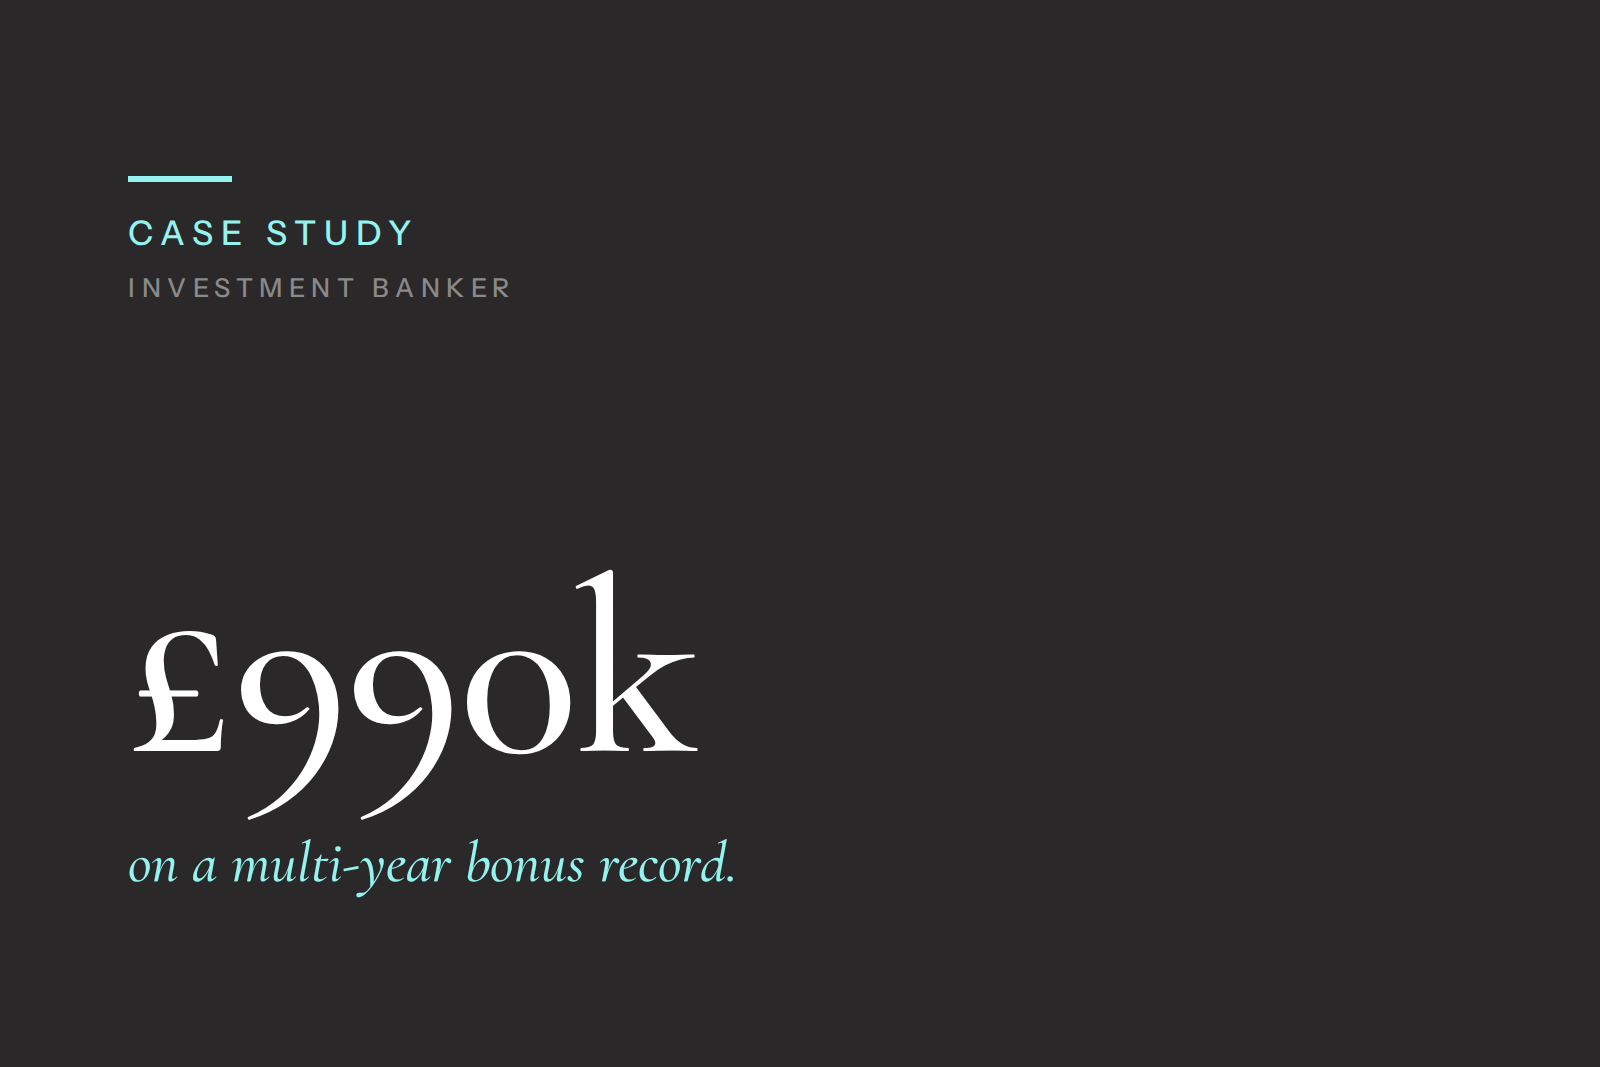
An investment banking Director secured a £990k mortgage on a £1.1m London flat at 90% LTV using multi-year bonus income. This case study shows how bonus averaging supported borrowing while retaining funds for property works.
A private equity VP secured a £1.9m mortgage on a £2.4m family home using salary and bonus income. This case study shows how part interest-only structuring and a five-year product aligned borrowing with future carry payments.
A UK-based employee of a US technology firm secured a £2.58m remortgage using USD salary, bonus, and RSUs. This case study explains how equity compensation and foreign currency income were assessed through a private banking solution.
An equity partner at a City law firm secured a £1.55m mortgage on a £1.85m family home using LLP income. This case study shows how part interest-only structuring supported affordability during a period of higher household costs.
A fixed-income trader secured a £1.5m mortgage on a £2.1m purchase using bonus-led income. This case study explains how lender selection and income structuring supported affordability despite restrictive bonus caps.
A senior finance professional returning from Singapore secured a £950k UK mortgage on a £1.45m London apartment using overseas USD income. This case study explains how foreign currency income was assessed ahead of UK relocation.
Offset Guardrails For Contractors & Business Owners
Offset balances must be personal, not company-held.
Limited company directors: To use funds for offset, distribute via declared salary/dividends into your personal account and allow for any tax due.
LLP partners: Only after drawings land in your personal account per the partnership agreement can they offset.
Sole traders: Keep funds in personal accounts to offset; maintain a clean audit trail.
Avoid last-minute large transfers; keep a clear 3–6 month trail.
Set Your Offset Up For Success (Practical Advice)
Account Structure (Personal)
Emergency Pot (3–6 months’ household outgoings)
Operating Buffer (1–3 months’ drawings)
Tax Reserve (self-assessment and, where relevant, VAT you hold personally until due)
Workflow
Ring-fence tax the day revenue lands (into your personal tax reserve).
Sweep spare cash into offset before big invoices or purchases.
Withdraw when needed; interest adjusts the same day.
Review pots monthly; top up during strong billing periods.
Worked Examples (Simple Numbers)
A) Day-Rate Contractor
Mortgage: £500,000 on repayment, 5-year fix (offset)
Average personal offset balance: £60,000 (tax + reserves)
Interest is charged on £440,000 instead of £500,000 while that cash sits in the account.
Result: lower interest cost and the £60,000 stays accessible for tax deadlines or gaps.
B) Limited-Company Director (Part-And-Part)
Mortgage: £900,000 split £600k repayment / £300k interest-only
Average personal offset cash: £150,000 (dividends already taken and held personally)
Effective charged balance becomes £750,000; you keep flexibility for dividend timing and investments.
Note: Any cash used to offset must be held personally. Company reserves are not linkable to a personal offset; directors should distribute funds legitimately (salary/dividends), allow for tax, and then hold balances in personal offset accounts.
Speak To An Expert Today
Get in touch for a fee free, no-obligation chat about how we might be able to help you.
When Offset May Not Be Right
Low or sporadic cash balances: Little to offset = limited benefit.
Chasing the very lowest rate: Non-offset deals can price a touch cheaper; compare total cost.
High LTV constraint: If funds are small and LTV is high, a standard product might be more efficient.
Interest-Only, Part-And-Part & Exit Plans
Offset pairs well with part-and-part or interest-only where policy allows. You’ll need a credible repayment strategy (e.g., investment proceeds, future bonuses/dividends, downsizing or asset sale). Private banks can be flexible for strong profiles—but company funds still won’t offset a personal residential loan.
Documents Checklist (Contractors & Self-Employed)
ID & address history
Day-rate: current contract(s), 12-month history, invoices/payslips, bank statements showing credits
Self-employed/LLP:2 years’ accounts and SA302s (plus accountant’s letter if helpful)
Savings proof from personal accounts in borrower name(s)
If funds originated from your business: include dividend vouchers / payslips / LLP drawings statements and personal bank statements showing receipt (for source-of-funds evidence only)
Typical Hurdles — And Practical Fixes
Gaps between contracts: Provide full history, explain gaps succinctly, and show current pipeline or signed extension.
Spiky revenue: Use averages/YTD evidence; keep a consistent personal tax reserve to demonstrate sustainability.
High dividends vs modest salary: Lenders may use salary + dividends or share of profit; choose the lender that aligns with your accounts.
Large loans: Consider private banks for bespoke offsets and underwriting (still personal funds only for offsetting).
Ready To Talk?
We’ll benchmark offset vs non-offset (and high-street vs private bank), model total cost using your real cashflow, and design the personal pot structure that keeps you liquid and calm. Request your fee-free mortgage consultation.
Request your fee free mortgage consultation today. No obligation, just sound advice.
FAQs
-
Not always. Sometimes the rate is similar; sometimes non-offset is slightly cheaper. The daily interest saving from your cash can outweigh a small rate gap.
-
No. Personal residential offsets only recognise personal savings in the borrower’s name(s). Company cash reserves cannot be linked. If you are a director/partner, funds must be properly distributed to you (salary/dividend/drawings), any tax liabilities allowed for, and then held in your personal account before they can offset. Policies vary; we’ll confirm product-specific rules.
-
Some may assess as day rate × 5 × 46 weeks with suitable history; others use YTD/P60 or accounts. Policies vary.
-
Often yes—offset lets you change emphasis by moving money in/out, within product rules.
-
Yes—parking self-assessment and, where relevant, VAT funds in personal offset accounts can cut interest until HMRC payment dates, while keeping cash liquid.
Related Articles
You have read how partners with carried interest get their mortgages structured, and assumed yours would need the same. At associate and VP level the pay is salary and cash bonus, and that is one of the cleanest income shapes lenders on our panel see. What decides the figure is how much of the bonus each lender counts.
Your equity may be worth six figures on the last funding round and nil to a mortgage lender, because nothing has vested, nothing can be sold and there is nowhere yet to sell it. Here is what a purchase at a private company may stand on instead, how EMI options and secondary sales fit, and what changes the day the company lists.
NatWest’s published policy may use 100% of converted foreign currency income with no haircut, from a defined currency list, for UK residents. The exchange rate is taken at underwriting rather than fixed early, which cuts the other way. Here is how the published criteria work at the time of writing.
Two engineers with the same base salary and the same four-year grant can be offered different mortgages, because what a lender reads is the vesting schedule. Back-loaded, front-loaded and cliff schedules put the vested value in different years, and the year a lender looks at decides the figure.
A minority of UK lenders accept foreign currency income, and they differ on the three things that decide your case: which currencies they accept, how much income survives the haircut, and whether you need to live in the UK. Here is how the landscape maps, and how to work out where you fit.
The fixed-or-tracker decision looks like a bet on interest rates. For a professional paid in salary plus bonus or equity it is more usefully a decision about flexibility: how much you want to overpay, when the money arrives, and how long you expect to hold the loan.
Two lenders can look at the same banker's P60 and reach borrowing figures hundreds of thousands of pounds apart. The difference is rarely the income. It is how each lender treats the bonus: how much of it counts, how it is averaged, and whether the deferred portion registers at all. Here is how the assessment varies across the panel.
You earn well, you are a qualified professional, and you have heard that lenders offer professionals better rates. Some specialist lenders do, and the rate is rarely better than a mainstream lender’s standard rate. What changes more is the criteria behind the rate: the income multiple a lender may apply, how it reads bonus, profit share or equity, and which structures it opens.
A standard mortgage may lend around 4.5 times income. Some lenders may lend 5x, 5.5x, 6x and occasionally more, and the gates are not what many professionals expect: income thresholds and loan-to-value bands do more of the work than the job title. How the enhanced tiers are gated, what moves an application into one, what the extra borrowing looks like on a professional couple’s income, and why the maximum figure is a reference point.
Your fixed rate is ending and the choice looks binary: stay with your lender on a product transfer, or remortgage to a new one. For a high earner with bonus, equity or partnership income the decision has more moving parts than the rate: whether your income will be reassessed, what a rate gap is worth after fees on a large loan, which structures open up, and when to start.
Halifax accepts non-sterling income in five currencies, with a haircut and an exchange rate fixed at the decision-in-principle stage. The published rules are unusually specific, which cuts both ways. Here is how the criteria work at the time of writing, and when another route may fit better.
You earn well for your age, and most of your pay arrives once a year. That combination is what a mortgage lender has to make sense of. This is how associate and VP income is assessed at the point in your career when the bonus history is still short, and what to do about it before you start viewing.
If you work on a trading floor, your payslips and P60 show what you were paid, not how your pay works. Lenders read a low base and a large discretionary bonus through models built for salaried applicants, and the result can understate your borrowing by a wide margin. Here is how the assessment works, why standard models fail for traders and structurers, what lenders weigh instead, and what a two-year bonus record can support.
Restricted Stock Units (RSUs) can count towards a mortgage, but only at some lenders and usually only once they have vested and been sold for cash. Which lender you use, and how your proceeds have been handled, can move the borrowing figure by hundreds of thousands of pounds on the same income. Here is how RSU income is assessed, what evidence it takes, and when it is better left out.
Your total compensation and your assessed income are rarely the same number. For City professionals, the gap between what you earn and what a lender may count, and at what percentage, is often the difference between the mortgage you want and the one you are offered. Here is how each income type is read, and how lenders combine them.
You have probably heard that self-employed borrowers need a bigger deposit. Not by rule. With two years of figures many lenders on our panel may treat you on the same loan-to-value bands as an employed applicant, and some contractors qualify at 95%. Where a bigger deposit helps is on the restricted ranges: a short trading history, uneven income, or a large loan. Here is how the bands work, and when one year is enough.
Many lenders may count bonus income towards a mortgage, but the proportion varies enormously: some average two years and take half, others may use all of the latest year. On a six-figure bonus, that spread is the difference between the flat and the house. Here is how the assessment works, and when the bonus is better used as deposit.
Becoming an equity partner is a career milestone. For a mortgage it introduces a different test: your income is higher than ever, and many lenders may treat it more cautiously than your old salary. Here is how lenders read equity partner income, exactly what they ask for, and how to package a case so it clears first time.
Six times salary exists. It is also gated: an income floor, a loan-to-value band, a repayment type and a loan size all have to line up before a lender applies it, and missing one gate by a few thousand pounds of deposit can drop the cap straight back to 4.49x on identical income.
You earn well. You will probably be fine. But “fine” can leave a lot of borrowing on the table. The same payslips can produce very different numbers depending on the lender, how your bonus or profit share is presented, and your deposit. Here is how the figure is calculated for lawyers, and which levers move it.
Half of your bonus arrives late, in tranches over the next few years. Which half does a lender count? The answer turns on vesting, not on the award letter: tranches already paid through payroll may be read as bonus income, while tranches still to come are a promise most mainstream lenders may set aside. Here is how the assessment works.
As an LLP partner you are treated as self-employed by mortgage lenders, even when your income is steadier than most PAYE roles. Some lenders want two years of tax calculations before they use your partner income. Others may lend on day one of partnership. The difference can run to six figures of borrowing on identical income.
HSBC is one of the few high street names that may consider foreign currency income and, in some cases, non-UK residents. The policies are broader than most, and more detailed. Here is how the published criteria work, what evidence is expected, and when another route may fit better.
A private bank mortgage is underwritten around your whole financial picture rather than a formula. For some City professionals that is the only route that reads their income properly; for many others a mainstream large-loan team gets there first and cheaper. Here is how to tell which side of that line you are on.
Your fixed deal is ending and you are now living abroad. The property has not changed and your income may not have changed, but the remortgage is assessed on a different basis from the day you bought. Which lenders still lend, how foreign currency is treated, and when to start, all matter more than they did first time round.
Loan sizes in seven figures need a different conversation. This article covers how private banks and specialist lenders underwrite HNW cases, from asset-based affordability and AUM to interest-only and cross-collateral structures, and how to know which route is right for your profile.
You are a partner in name, but your income reaches a lender as something stranger: part profit share, part drawings, sometimes part salary, often with carry the lender sets aside entirely. Operating partners earn well and usually borrow comfortably. The real work is deciding which layers to put forward, and which to leave off.
Run an interest-only mortgage on an offset facility and you stack two features: the low committed payment of interest-only, and the interest reduction of an offset. For City professionals holding large, fluctuating cash balances, that combination can mean a smaller monthly outgoing, less interest paid, and savings that stay within reach.
Carry doesn't arrive in neat annual instalments. It lands deal by deal, clusters in realisation years, and goes quiet in between, and a mortgage model built for regular pay reads that shape badly. The question is rarely whether your carry is real. It's whether the pattern has been evidenced, and the application timed, so a lender can use it.
Operations and business-side pay at a hedge fund is often more legible to a lender than a portfolio manager's, yet the discretionary bonus and the deferred element still decide how much you can borrow. Here is how mainstream lenders read a non-front-office income, and where a specialist changes the outcome.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
Approved by The Openwork Partnership on 27/11/2025