
High Net Worth (HNW) Mortgages: Options, Structures, and What Lies Beyond the High Street
How private banks and specialist lenders underwrite high net worth cases, and how to know which route is right for your profile.
In short
When loan sizes move into seven figures, mainstream criteria can feel blunt. High net worth (HNW) lending runs through two routes: high street large-loan desks (sharper pricing, model-driven affordability) and private banks (relationship-led, asset-based affordability, full interest-only, cross-collateral and revolving structures). The right choice depends on income complexity, loan-to-value (LTV) target and appetite for assets under management (AUM). For many profiles built on carried interest, Restricted Stock Units (RSUs), limited liability partnership (LLP) drawings or foreign currency income, private bank underwriting can open options that mainstream criteria may not reach. An HNW mortgage broker's job is to work out which route fits, then build the file for it.
Who this is for
You are borrowing at £1m or above, or expect to, and you are not sure whether the high street can handle your profile. Your income is some combination of salary, bonus, partnership drawings, carried interest, RSUs or foreign currency. You want to understand what your real options are, how each route works mechanically, and what you need to prepare. This article covers all of that.
What makes HNW mortgage underwriting different?
When you borrow at scale the mechanics of underwriting shift. The fundamentals do not change, lenders still assess income, affordability, credit and property, but the emphasis moves. A mainstream lender's model is calibrated for salary-plus-bonus profiles at standard loan sizes. Move into seven or eight figures with complex income and that model can start to work against you.
Many mainstream lenders cap their loan-to-income multiples regardless of actual wealth. Their interest-only policies may tighten sharply above certain LTV bands. Their income models can struggle with carried interest, LLP profit share, foreign currency earnings and RSU awards, not because these incomes are unreliable but because they do not fit the template. And their valuation panels may not know the micro-market for a specific Prime Central London address.
HNW lending, whether through a high street large-loan desk or a private bank, exists to work around these limits. The two routes work very differently, and the right one depends on your profile. The routes themselves, and how to access each, are covered in our large loans guide. Read the large loans guide →
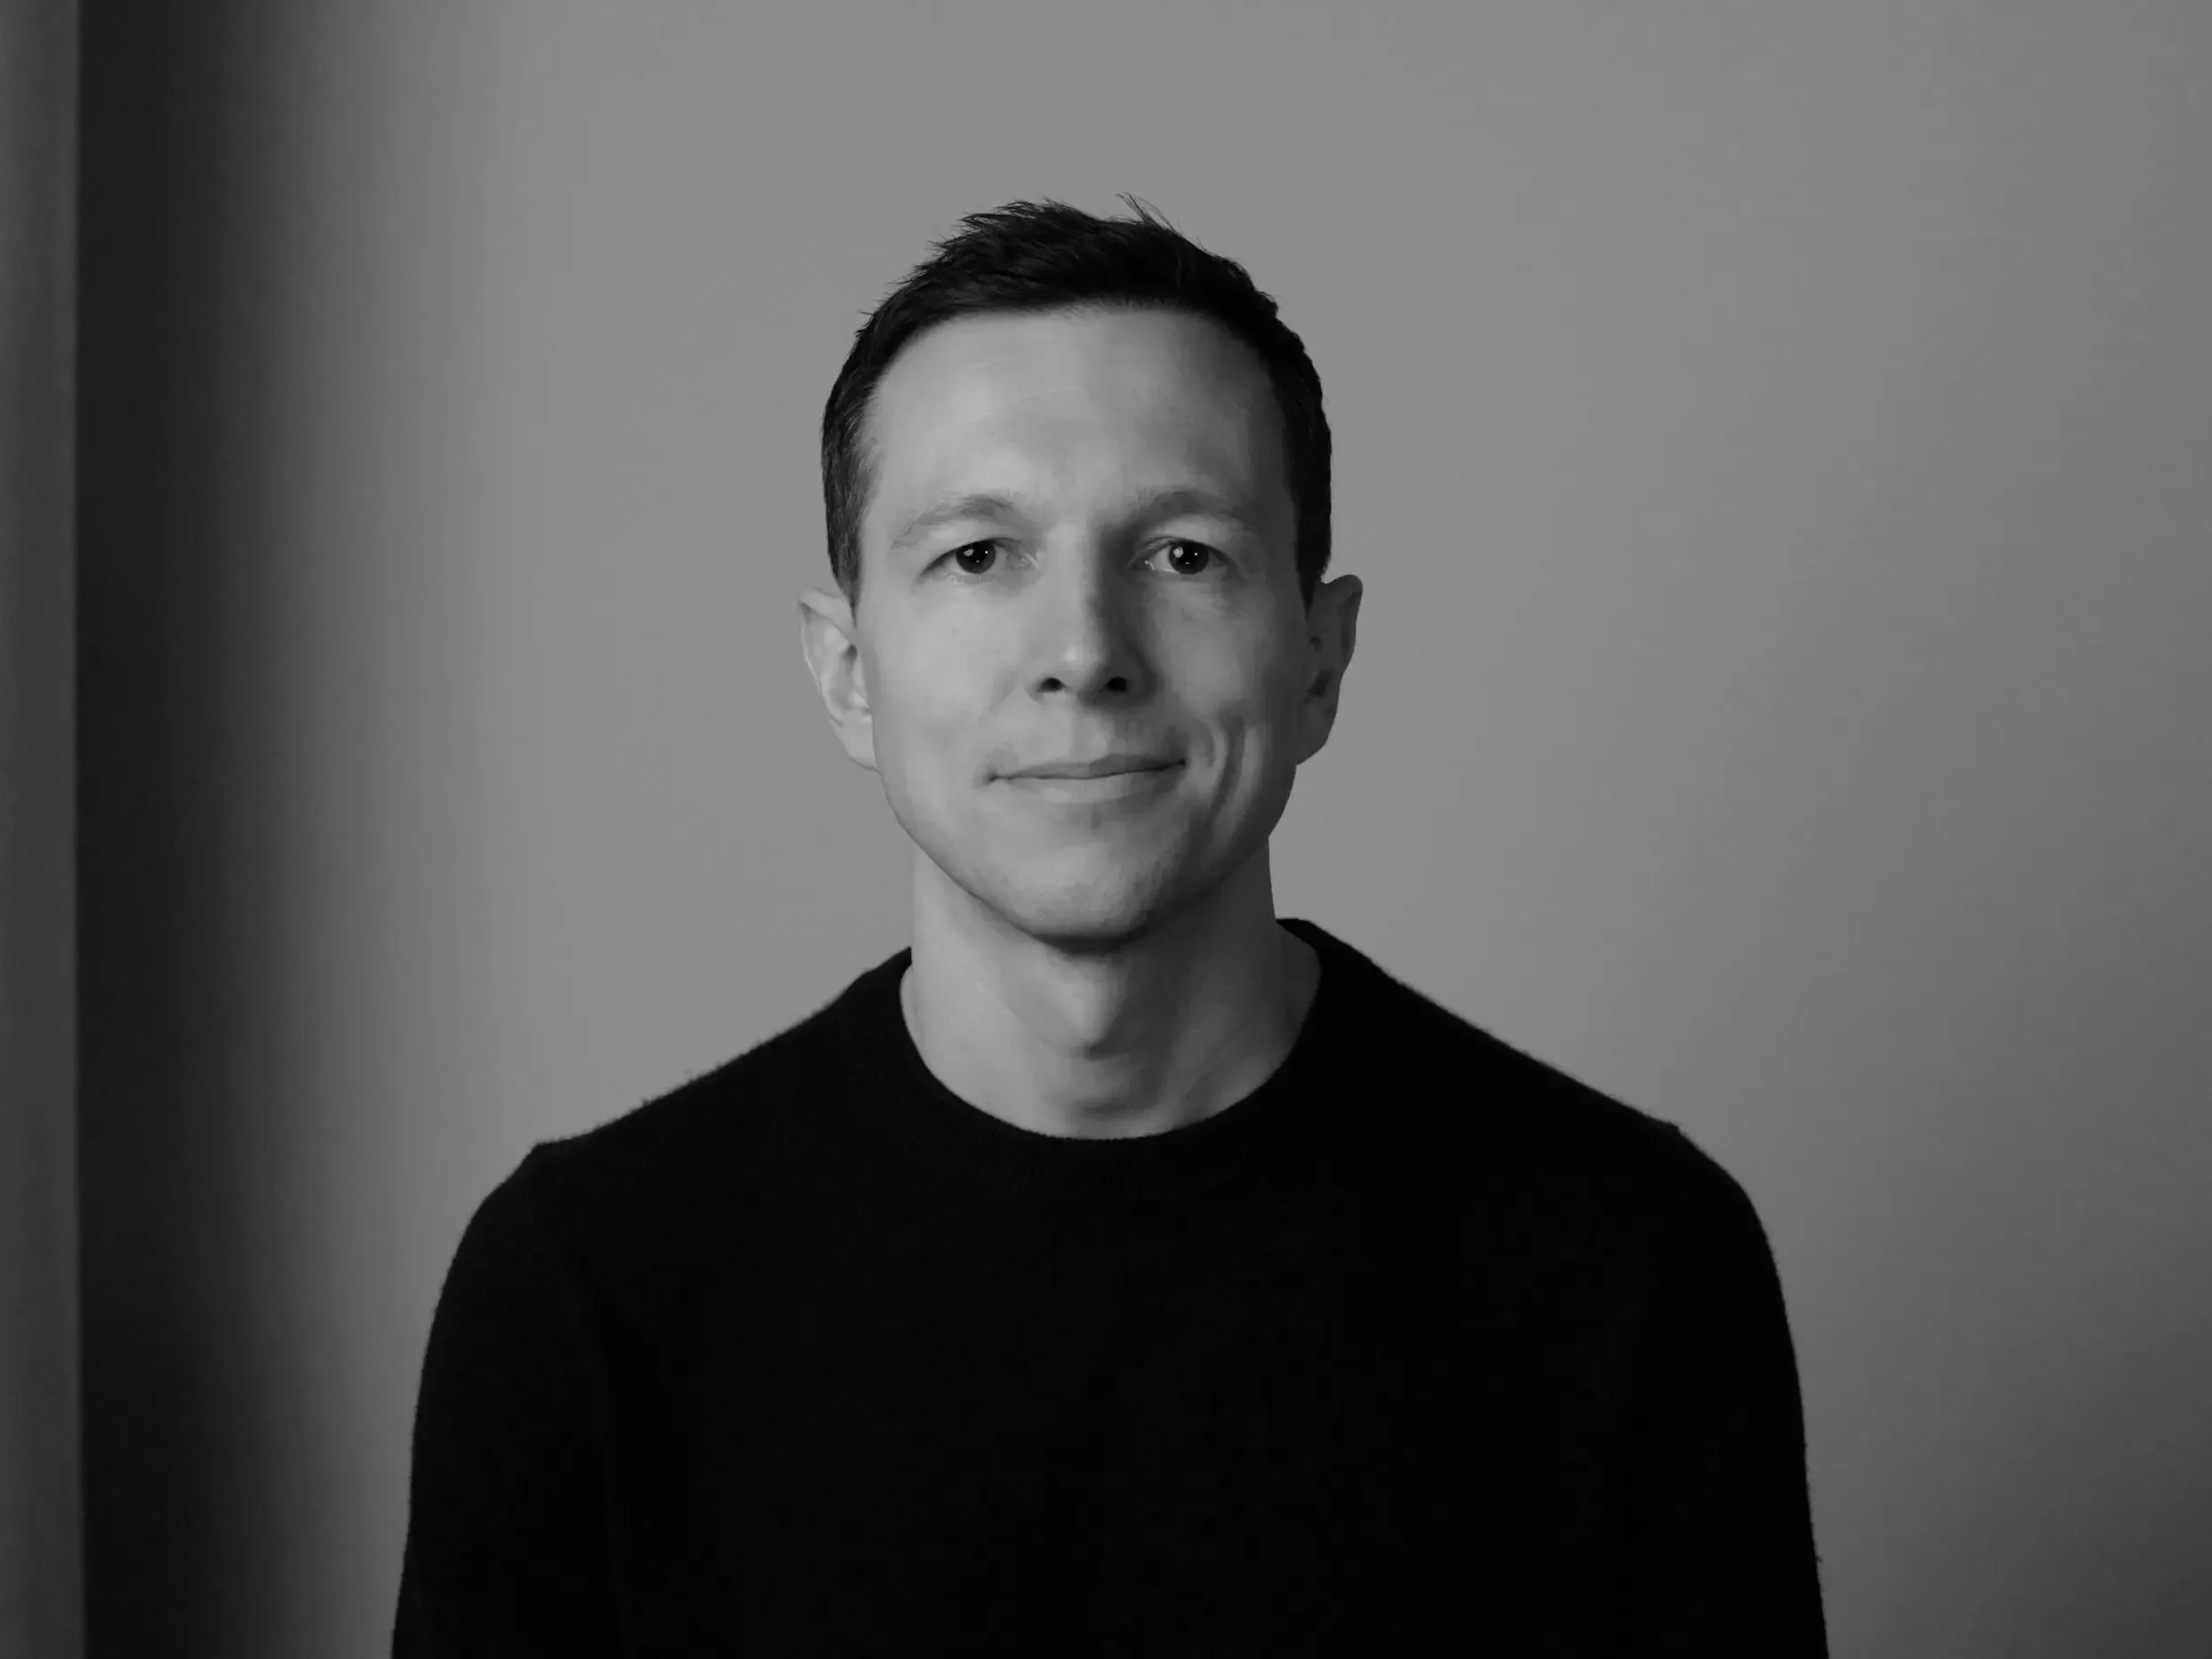
Director and Mortgage Adviser
Specialist mortgage broker for City professionals. David structures seven-figure mortgages for law firm partners, investment bankers, private equity and hedge fund professionals and senior executives, running the high street and private bank routes side by side and recommending the one the case actually needs.
High street large-loan desks vs private banks: which is right for you?
The most consequential decision in HNW lending is route selection. Both routes are available through our panel, and they suit very different client profiles.
Our philosophy is straightforward. Mainstream lenders now have capable large-loan teams and experienced underwriters, and for most files they are the cheaper route. There is no reason to pay a private bank premium for flexibility you could get on the high street. When the high street cannot accommodate your profile, because of income structure, LTV, asset-based affordability or the product flexibility you need, a private bank is the right answer.
We run both options where the case is close. For the definition of a private bank mortgage and a side-by-side comparison of the two routes, see What Is a Private Bank Mortgage (and Should You Consider One)?. For which route to start with at £1m and above, see our large loans guide.
How does HNW underwriting actually work?
Three different lenders, looking at the same high net worth borrower with the same income on the same day, can produce three materially different outcomes. The drivers are how they evidence affordability, how they treat each complex income component, and how much structural flexibility they offer around interest-only and exit. The worked example below shows the spread on one profile.
Please note: These figures are for illustrative purposes only. The actual amount you can borrow will depend upon your personal circumstances, credit profile, LTV, the lender's individual criteria and full affordability assessment.
Published criteria set the floor of what may be achievable. For the right profile, an established bonus history, a clean income story and well-prepared documentation, large-loan teams at many lenders have some flex above the published rules: bonuses accepted at 100% rather than the published cap, the latest year used rather than the lower of two, foreign currency haircuts eased for clients with strong UK ties. Knowing where that flex sits, and having the relationships to reach it, is part of what a specialist broker does at this level.
How is complex income treated for HNW affordability?
The income assessment is where many mainstream lenders lose HNW cases. Understanding how each component is treated, and which lenders handle each most favourably, is the starting point for any HNW application.
Bonus income
Many mainstream lenders may take the lower of the latest year or a two-year average. Some large-loan desks may use the latest year if higher, or accept 100% of a consistent bonus rather than discounting it. At private bank level, bonus income is often averaged over two to three years with supporting evidence, and underwriters can exercise discretion for strong, consistent earners.
Carried interest and co-investment
Many mainstream lenders exclude carried interest from affordability, treating it as too irregular and too difficult to evidence. Private banks are more familiar with it: they can average historic distributions and use fund documentation to build a credible picture. If carry is central to your wealth, the private bank route is often the realistic option. For more detail: Why Private Equity Income Often Needs Specialist Mortgage Structuring
RSUs and stock awards
Lenders that accept RSU income usually rely on vested and realised proceeds with a two-to-three-year pattern. Some may use unvested awards as background evidence without including them in the income calculation. Private banks can consider unvested RSUs as part of a wider wealth picture, particularly where vesting schedules are documented.
LLP and partnership drawings
Assessed on your share of taxable profit as it appears on the tax calculation (SA302), not on drawings. The lower of the latest year or a two-year average is again the common starting point. Treatment of fixed drawings against profit share varies considerably: a lender that separates the two can sometimes recognise more income than one treating it as a single self-employed figure.
Foreign currency income
Affordability usually includes a currency haircut, anything from nil to around 25% depending on the currency and the lender. Bank statements evidencing regular conversion to sterling are usually required. Some mainstream lenders may not accept foreign currency income at all; private banks are generally more comfortable with it. For a breakdown by currency: Which UK Lenders Accept Foreign Currency Income?
What structures are available, and which suits you?
The product structures available at HNW level go well beyond the standard repayment mortgage. Understanding the options matters before selecting a lender, because the structure drives the lender choice as much as the income does: not every lender offers every structure, and some are largely private bank territory.
Most common at HNW level
Interest-only (full and part-and-part)
Pay only the interest each month; capital is repaid separately through a credible repayment strategy such as an investment portfolio, the sale of another property, vested equity or a planned liquidity event. Part-and-part (a portion interest-only, a portion repayment) is widely used to balance flexibility with gradual capital reduction. Lenders want the repayment strategy evidenced up front; some accept investment portfolios, others restrict to property sale, and policy varies significantly.
Tax reserves and lumpy income
Offset mortgage
Links one or more savings accounts to your mortgage balance. Cash held in those accounts offsets the debt for interest purposes without paying it down. For HNW borrowers who hold significant liquid reserves (tax provisions, year-end allocations, bonus cash awaiting deployment) this can reduce interest while keeping every pound accessible. Most useful where cash balances are regularly six figures or above.
Private bank structure
Revolving credit / drawdown facility
A flexible credit line secured against your property: you draw what you need, repay it and draw again, and interest accrues only on the outstanding balance. Some private banks integrate this with your current account, creating a single facility across mortgage, liquidity and day-to-day banking. Useful for clients who want flexible access to equity without remortgaging. Rarely available on the high street; a private bank relationship is usually required.
Multiple property ownership
Multiple securities / cross-collateral
Pledging a second property as additional collateral alongside the primary purchase, reducing the headline LTV on the main loan and potentially unlocking better terms, a higher interest-only proportion, or lending that would not meet criteria on a single-security basis. More common at private bank level, where underwriting is relationship-led. Both properties need to be acceptable security to the same lender.
For when interest-only makes sense and how repayment strategies are assessed, see our interest-only mortgage guide. Where the constraint on a family purchase is affordability rather than the borrower's own wealth, a joint borrower, sole proprietor arrangement is sometimes the more useful structure than any of the above.
What does AUM mean, and do you always need it?
Assets under management (AUM) is the mechanism by which private banks deepen the relationship beyond the mortgage. You place an investment portfolio with the bank's wealth management arm; in return the bank may offer improved pricing, more flexible underwriting, or lending that would not otherwise be available.
AUM requirements vary considerably. Some private banks may require a minimum portfolio as a condition of lending, often a high six-figure or seven-figure sum depending on the institution. Others offer the same underwriting flexibility without it, particularly for high-earning professionals who represent a long-term banking relationship even without an initial AUM mandate. And for some cases, newly promoted partners or senior executives earlier in their wealth accumulation, a private bank may be comfortable lending on income alone with no AUM expectation.
The trade-off is real. AUM can unlock flexibility, but it ties your investments to a specific institution and may not be the best home for your capital. We model the total cost, rate, fees and the implied investment friction, side by side with the non-AUM alternative, so you can make an informed decision rather than defaulting to what the bank proposes.
Our default is mainstream if it fits. We recommend a private bank when it offers something the high street cannot, usually because mainstream criteria will not accommodate the income structure, the LTV target or the product flexibility needed. That is the bar we apply.
What do you need to prepare?
The evidence package for an HNW application is more extensive than a standard case, particularly for a private bank application, where know your customer (KYC) and source-of-wealth requirements are rigorous. Assembling everything before submission matters: a clean, complete file gets a clean decision, while a file with gaps triggers queries, and queries at this level can delay completion by weeks.
Identity and KYC
Passports, visas, proof of address and, where assets are moving, source-of-funds and source-of-wealth documentation. KYC checks at private banks are more detailed than on the high street. International clients or those with complex business structures should allow additional time.
Income pack
Payslips and P60s (or partnership accounts and tax calculations (SA302s)) for the last two years. Bonus confirmation letters and a history of variable pay. Carry or RSU schedules. An accountant's or employer's letter where income is complex or has recently changed.
Assets and liabilities
Portfolio statements for the last 12 months and custody letters from your investment manager. A liquidity breakdown showing what is accessible and on what timeline. A property schedule if multiple securities are involved. An estimate of tax on account if it bears on monthly commitments.
Property pack
A valuation-ready dossier: comparables, floorplan, lease, service charges, details of any planned works. At higher values the lender may instruct its own surveyor, and valuation panel fit matters, particularly for Prime Central London addresses where micro-market knowledge varies sharply.
Objectives
Target LTV, interest-only appetite, AUM comfort level, completion timeline, and any planned liquidity events that affect the structure. The clearer this is up front, the faster the right lender and structure can be identified.
Where do HNW borrowers go wrong?
Three patterns come up repeatedly when clients come to us after struggling elsewhere.
Going to their existing bank first. The assumption is that a longstanding relationship will translate into favourable lending terms. It rarely does. Your bank knows you as a current account or investment client; its mortgage team may treat your income under the same policy it applies to any self-employed or complex-income applicant. Familiarity with you as a client is not familiarity with how to structure your mortgage.
Submitting to the wrong lender without a complete file. A lender that cannot handle your income structure is likely to decline or significantly under-offer, however strong the profile. A lender that could handle it but receives an incomplete file is likely to raise underwriter queries that can drift for weeks. Lender selection and document preparation are the two most controllable variables in an HNW application.
Treating rate as the only metric. The total cost of a mortgage at this level includes fees, AUM implications, early repayment flexibility, the reversion rate, valuation costs and the friction of the lender relationship over the term. A private bank at a higher rate may be the better total outcome than a high street lender at a lower one, if the structure fits your wealth plan more precisely. The comparison needs to be on total cost, not the headline rate.
What does an HNW mortgage broker actually do?
An HNW mortgage broker maps your income and assets to the lenders whose models can read them, chooses the structure that fits how you are paid, and builds the file so that a large-loan desk or a credit committee can say yes first time. At this level the value is rarely in finding a rate. It is in knowing which lender recognises carried interest, which large-loan team has flex above its published multiple, which private bank may lend without AUM, and how each one wants the evidence presented.
In practice that means three things on every HNW case we take on. We model affordability across several lenders on both routes, so you see the real range rather than one bank's answer. We put the total cost and the terms side by side where a private bank is in play, including any AUM implications, so the decision is informed rather than defaulted. And we prepare the evidence pack to the standard the chosen underwriter expects, because at seven figures a clean file is the difference between an offer in weeks and queries that run for months.
We place cases with high street large-loan teams and private banks on our panel every week, and the reason to use a specialist rather than a generalist is that appetite at this level moves lender by lender and month by month. Knowing where it sits now is the job. If you want the high street view first, that is where we start; where the case needs a private bank, we say so and introduce it properly.
Part of a wider guide
This article sits within our large loans guide, which covers the two routes to borrowing £1m and above, how affordability works at that scale, and which route fits which profile.
Read the large loans guide →FAQs
There is no single definition in mortgage lending. In practice lenders start treating cases differently at loan sizes of £1m to £2m and above, particularly where income is complex. A working definition sometimes used is income above £300k or total assets above £3m, but the threshold varies by lender and complexity matters as much as scale.
Not always. High street large-loan desks can be both cheaper and faster for simpler income profiles and moderate LTVs, and we start there where the profile fits. A private bank becomes the right answer when the high street cannot accommodate your income structure, your LTV target or the product flexibility you need.
Not always. Some private banks price keenly without AUM; others ask for a portfolio to unlock flexibility or as a condition of lending. We model the total cost, rate, fees and investment friction, against the non-AUM alternative so you can choose on what matters to your situation.
Often yes, at lower LTVs and with a credible capital repayment plan in place. Common repayment strategies include investment portfolios, planned liquidity events, the sale of another property or vested equity. Some lenders accept investment portfolios as the repayment vehicle and others restrict to property sale, so this is one of the areas where lender selection matters most.
Many mainstream lenders exclude it entirely, treating it as too irregular and difficult to evidence. Private banks are more comfortable with it and can average historic distributions using fund documentation. If carried interest is a significant part of your compensation, a private bank is often where the case ends up.
Yes, with the right lender. Mainstream lenders that accept foreign currency income may apply a haircut of anything from nil to around 25% depending on the currency, and usually want bank statements evidencing regular conversion to sterling. Some mainstream lenders may not accept it at all, while private banks are generally more comfortable with multi-currency income.
Many mainstream lenders on our panel accommodate loans above £1m, with LTV bands tightening at higher loan sizes, and some may extend to £5m or above; at least one may go to around £7.5m at 65% LTV. Above £5m, private bank placement is more common. Manual underwriting begins at different thresholds across lenders, so early lender engagement matters on the largest loans.
There is no fixed league table: appetite for loan size, LTV, income type and currency differs bank by bank and changes over time, and many private banks lend mainly through intermediaries rather than advertising. The useful question is which bank fits your profile now, which an HNW mortgage broker who places these cases regularly can answer, and whether a mainstream large-loan team could do the same job for less.
Related Articles
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
Approved by The Openwork Partnership on 24/09/2026