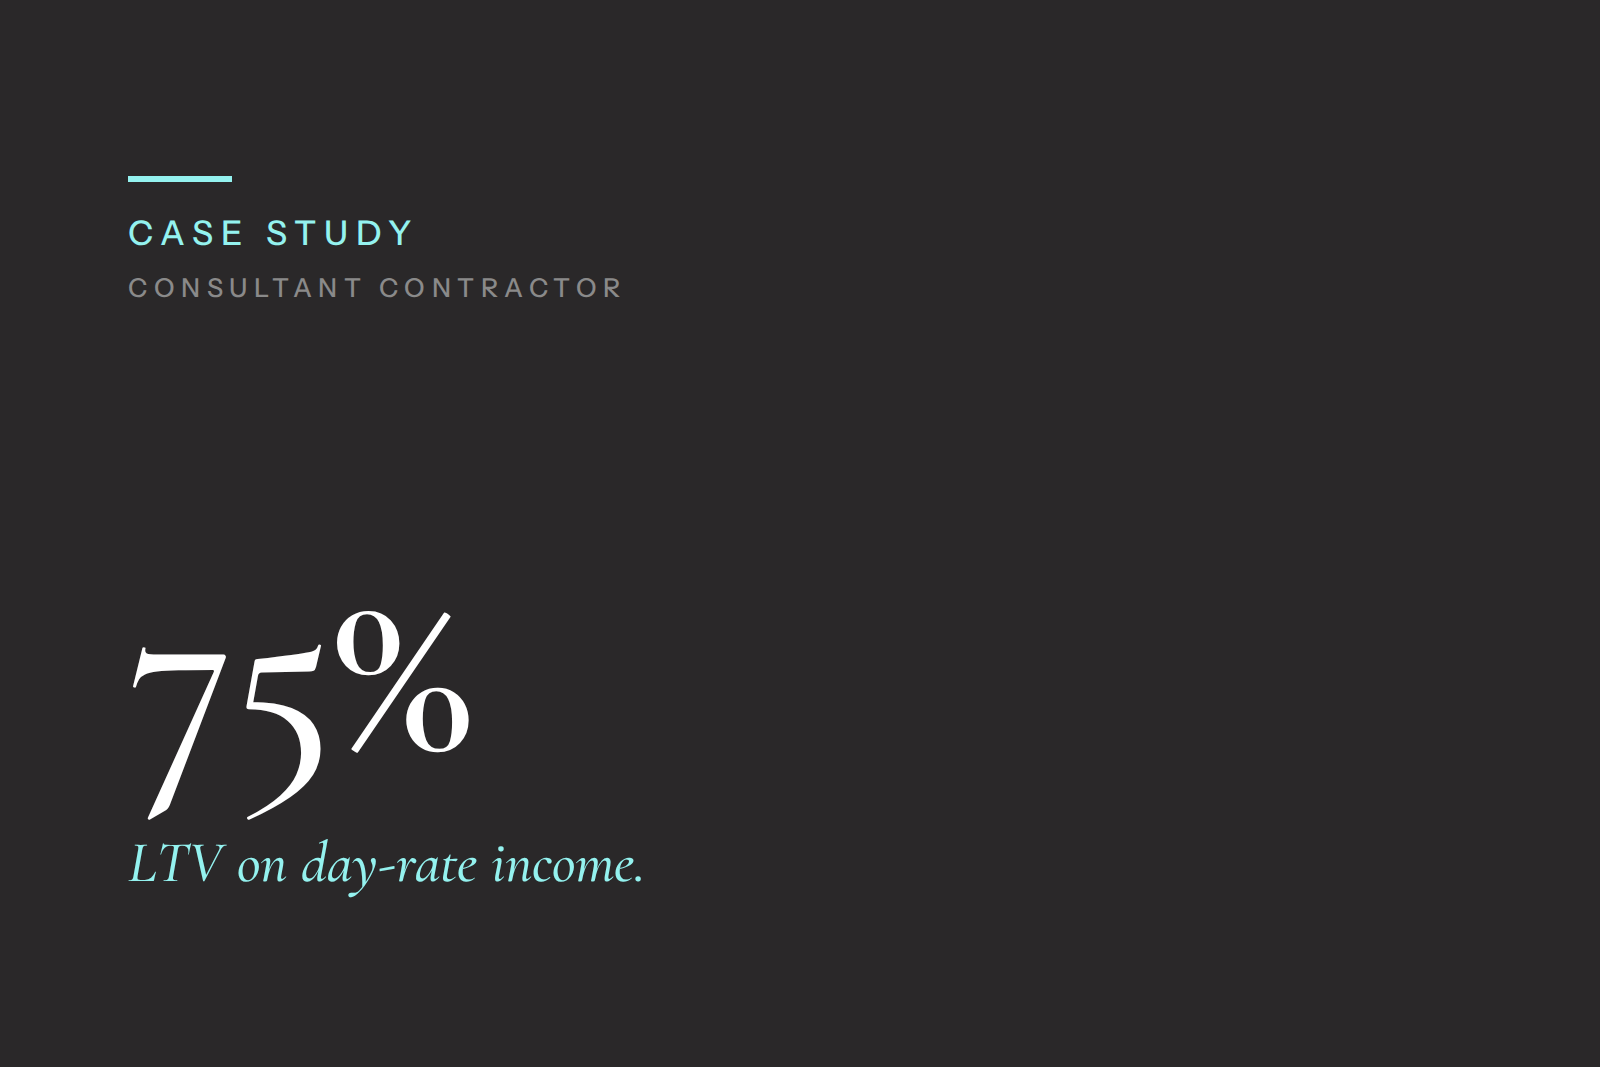
Consultant Contractor Secures £1.1m Purchase Using Day-Rate Assessment at 75% LTV
A management consultant operating via a personal service company secured a £1.1m residential purchase using day-rate assessment, despite a recent contract gap and IR35 scrutiny.
Client Snapshot
Profession: Management consultant (PSC contractor)
Location: England (UK)
Property Type: Residential house
Purchase Price: £1,100,000
Day Rate: £650 per day
Deposit: 25%
Loan-to-Value: 75%
Key Considerations:
Two-month contract gap in the previous year
IR35 and umbrella deductions
Mainstream lender required
Context
The client was an experienced management consultant working on a day-rate basis through a personal service company. Income was strong and consistent over time, but contracting naturally involved periodic gaps between assignments.
The objective was to secure a mainstream residential mortgage using day-rate assessment, rather than relying on salary and dividends, while ensuring the application reflected continuity of work and current trading position.
The Challenge
Many lenders apply strict rules around acceptable contract gaps, often limiting them to short periods unless clearly explained. In this case, a two-month break in the previous year required careful positioning.
In addition, the application needed to satisfy IR35-related scrutiny and ensure that umbrella or PSC deductions were not double-counted when assessing affordability.
Without precise lender selection and clear evidence of continuity, the case risked being down-weighted or declined.
Lender Strategy
Lenders were assessed based on their treatment of day-rate contractors, acceptable gap policies, and experience with IR35 considerations.
Affordability was modelled using a standard day-rate methodology aligned with mainstream policies, while alternative calculations were sense-checked where lender multipliers vary. The contract gap was documented as a planned pause between assignments, supported by historic contracts and current engagement evidence.
The selected lender was comfortable assessing contractors with short historic gaps and had a clear framework for reviewing IR35 status and deductions without penalising sustainable income.
Several lenders were ruled out early due to rigid gap limits or inflexible treatment of contractor income.
What We Can Do for You
Structure day-rate affordability clearly for lender assessment
Position contract gaps in line with lender policy
Navigate IR35 and umbrella considerations upfront
Package contractor applications to minimise underwriting queries
The Result
A mortgage was approved with a mainstream lender at 75% LTV, supporting the £1.1m purchase. The application progressed smoothly with no re-work required following initial submission.
Why This Matters for Similar Clients
Contractors often assume that recent gaps or IR35 scrutiny will restrict their borrowing options. In practice, lender selection and how continuity is evidenced are far more important than the presence of short breaks between contracts.
Request your fee free mortgage consultation today. No obligation, just sound advice.
FAQs
-
Commonly day rate ×5 ×46 weeks; some lenders vary the week count. Evidence usually includes your contract and bank statements.
-
Short gaps are often acceptable; beyond 4–6 weeks some lenders pro-rate income or require extra context. Others accept up to 8 weeks as standard.
-
Often yes—many lenders accept umbrella/inside-IR35 cases with the right evidence and deduction treatment.
Related Case Studies
An American VP on a Skilled Worker visa, 18 months into a London posting, needed £900,000 for a £1.2m house. A large international bank whose criteria let income override residency recognised £238,400 including his USD bonus; completed at 75% LTV.
A PE Partner refinancing £2.4m on a £3.2m home saw mainstream calculators read his carry as zero. A holistic underwrite credited a smoothed share of four years of distributions and the refinance completed interest-only at 4.8x recognised income.
A macro trader earning a £200k base with a bonus that swung between £180k and £420k needed £1.7m for a £2.3m family home. A clearing bank averaging three full years recognised £386,000 of income and agreed the loan interest-only at roughly 4.4x.
A hedge fund analyst on a £150k base needed £1.1m for a £1.4m home after his bonus fell to £120k from £270k. A lender applying 60% of a two-year average recognised £267,000 of income, and the loan completed at roughly 4.1x with the deposit unchanged.
An operating partner at a mid-market buyout firm needed £1.3m on a £1.7m home, with income spread across fixed drawings, board fees and a volatile profit share. Built on the stable layers at roughly 4.4x, it completed on mainstream large-loan terms.
A mid-market PE director needed £1.6m for a £2.1m home; salary and bonus reached £1,425,000 at most. A private bank recognised three years of crystallised co-investment gains, taking recognised income to £375,000 and the loan to roughly 4.3x.
A sole director drawing £90k while his company retained its profit needed £1.2m of borrowing. A lender assessing salary plus share of net profit after corporation tax recognised £267,570 of income, and the loan completed at just under 4.5x with no change to his dividends.
An investment banking Director secured a £990k mortgage on a £1.1m London flat at 90% LTV using multi-year bonus income. This case study shows how bonus averaging supported borrowing while retaining funds for property works.
A private equity VP secured a £1.9m mortgage on a £2.4m family home using salary and bonus income. This case study shows how part interest-only structuring and a five-year product aligned borrowing with future carry payments.
A UK-based employee of a US technology firm secured a £2.58m remortgage using USD salary, bonus, and RSUs. This case study explains how equity compensation and foreign currency income were assessed through a private banking solution.
An equity partner at a City law firm secured a £1.55m mortgage on a £1.85m family home using LLP income. This case study shows how part interest-only structuring supported affordability during a period of higher household costs.
A fixed-income trader secured a £1.5m mortgage on a £2.1m purchase using bonus-led income. This case study explains how lender selection and income structuring supported affordability despite restrictive bonus caps.
A senior finance professional returning from Singapore secured a £950k UK mortgage on a £1.45m London apartment using overseas USD income. This case study explains how foreign currency income was assessed ahead of UK relocation.
An established equity partner at a UK law firm secured a £2.25m family home using fixed drawings and partnership profit share. This case shows how lender selection and part interest-only structuring supported uneven income and long-term affordability.
HNW client, strong liquid assets but modest declared income, needed £3m for a £5m townhouse. We placed assets under management, built an asset-based underwrite and used an investment portfolio as the repayment plan—securing a bespoke interest-only facility at 60% LTV.
Newly qualified solicitor on £110k, buying a £750k flat while in probation. We targeted a lender that may accept a signed contract and start date, leveraged a strong deposit, and packaged the case cleanly—securing an offer before probation completed.
Locum consultant doctor with £140k mixed NHS/private income secured a £770k mortgage on a £1.2m home. We used 12–24 month averaging, full contract history and locum-friendly criteria to align with a mainstream lender—delivering a clean, timely approval.
Director–shareholder, £60k salary and £120k retained profits, needed £1m borrowing without ramping dividends. We targeted a lender that may use salary + share of net profit, evidenced sustainability, and explained a one-off expense—achieving approval at an effective 5× multiple.
Management consultant contractor on £650/day (PSC), two-month gap, and IR35 scrutiny. We used day-rate modelling, a credible gap narrative, and an accountant’s letter to align with mainstream policy—achieving approval at 75% LTV on a £1.1m home.
Returning British expat paid in USD, thin UK credit, and a 60-day deadline. We secured a lender that accepts foreign income with a haircut, used a US credit report, and ran a pre-arrival application—agreeing the mortgage at 65% LTV on a £1.6m home.
Skilled Worker and Spouse visa clients, £160k income, <18 months in the UK, needed a fast new-build purchase at £800k. We shortlisted a lender comfortable with shorter residency, secured a rapid AIP, perfected the AML trail—and achieved a full offer inside 10 working days.
A senior software engineer on £95k with quarterly RSU vesting bought a £900k house. By averaging 12–24 months of vested RSUs and packaging award letters, brokerage statements and payslips, we evidenced sustainable equity income—resulting in approval with a part interest-only structure.
An investment banking associate on £120k base with a USD bonus needed 75% LTV on a £1.25m flat. We used a two-year average bonus, applied a foreign currency haircut, and built a strong evidence pack—resulting in c.5.2× income and a successful offer.
A City lawyer and LLP partner with £420k variable profit share bought a £2.1m London family home at 60% LTV. We targeted a lender that may average three years’ profits, clarified the capital account, and structured part interest-only with an evidenced repayment plan.
With renewals and short gaps, this IT contractor needed day‑rate treatment. We evidenced continuity, explained the gaps, and matched them with a lender that assesses on day‑rate—securing borrowing aligned to realistic annualised earnings.
A newly qualified solicitor with limited employment history needed clarity and pace. We used her offer letter and first payslips, applied professional‑criteria know‑how, and packaged a clean, conservative case—helping a mainstream lender say yes without over‑promising.
Briefs, arrears, and variable fee sheets—this barrister’s earnings were anything but tidy. We evidenced sustainability and secured a suitable mortgage at pace—without over‑promising.
A senior partner had to choose between a private bank and a high‑street lender for £2m. The private bank’s full interest‑only structure won—keeping monthly payments steady and letting annual profit share reduce the balance without hassle.
A newly made‑up equity partner needed a high‑value mortgage against uneven drawings and profit share. We evidenced sustainability, clarified tax and capital contributions, and matched them with a lender that considers partner income—without overstretching.
An IT Sales Director and Teacher with two children needed £800k to upsize to a £1.2m home. We secured 5.5x income using 100% of bonuses and structured part of the loan on interest-only — keeping monthly payments affordable with a plan to reduce the balance using future bonuses.
3 Feb - Written By David Walsh
YOUR HOME MAY BE REPOSESSED IF YOU DON’T KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
APPROVED BY THE OPENWORK PARTNERSHIP ON 24/09/2025