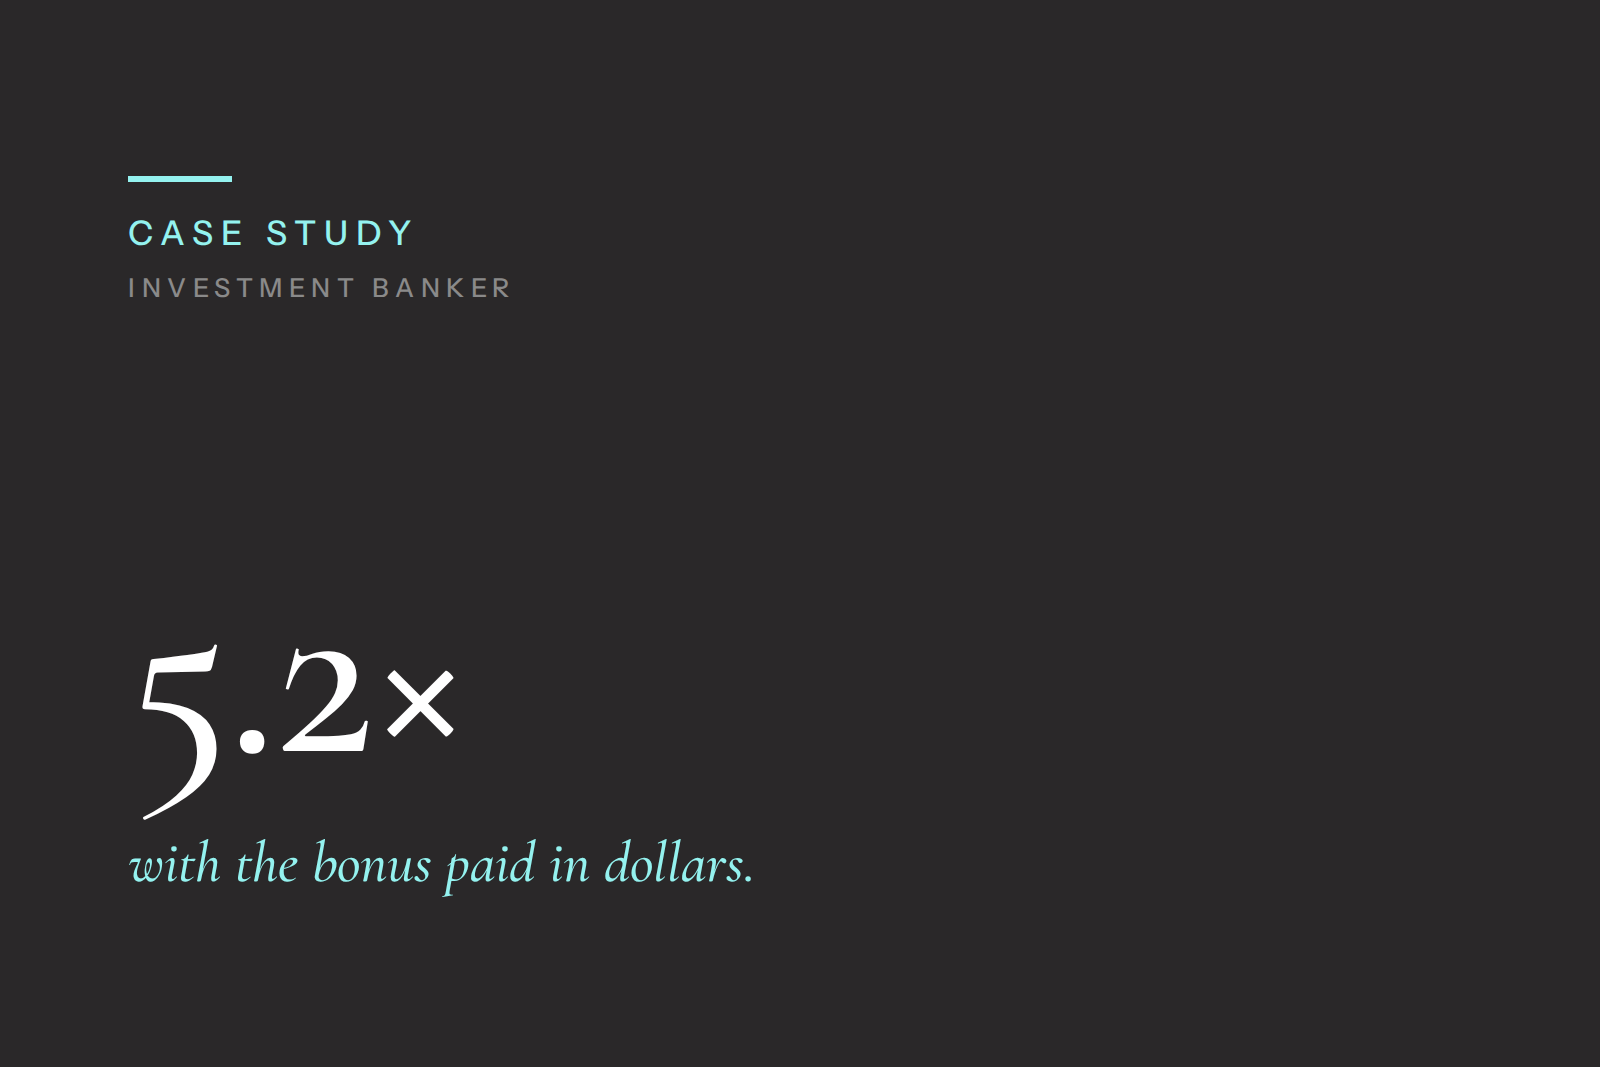First-Time Buyer Legal Associate Uses Bonus to Boost Borrowing by £175k
DIRECTOR AND MORTGAGE ADVISER
Specialist broker for high-earning professionals and complex income cases.
Request your fee free mortgage consultation today. No obligation, just sound advice.
Overview
Our client, a newly qualified legal associate, was buying their first home with their partner. Initially, they believed they could only borrow against their basic income, which would have limited their search significantly. However, by utilising their bonus income, they were able to transform their options.
The Challenge
The couple faced several challenges:
First-time buyers: They were unfamiliar with the complexities of income-based borrowing.
Bonus income: The associate had only received one bonus in their current role.
Conservative lender advice: Many lenders wanted two years of bonus history or wouldn’t include it at all.
Without including bonus income, their borrowing power would have been severely restricted.
Speak To An Expert Today
Whatever it is, the way you tell your story online can make all the difference.
Our Solution
We used our expertise in professional mortgages to:
Identify a lender willing to use 60% of the associate’s single year bonus — rather than requiring a two-year track record.
Increase their borrowing capacity by £175k, transforming their budget and widening their choice of properties.
Guide them through the process as first-time buyers, ensuring they understood each step and felt confident in their purchase.
The Outcome
By including bonus income, the couple could borrow an additional £175k — allowing them to purchase a flat with a second bedroom and a garden. This was a significant upgrade from what they initially thought they could afford based solely on basic salary.
What We Can Do for You
If you’re a newly qualified professional or first-time buyer, don’t assume you’re limited to borrowing against your basic salary. With the right advice and lender, bonus income can make a major difference in what you can afford.
Request your fee free mortgage consultation today. No obligation, just sound advice.
Related Case Studies
An American VP on a Skilled Worker visa, 18 months into a London posting, needed £900,000 for a £1.2m house. A large international bank whose criteria let income override residency recognised £238,400 including his USD bonus; completed at 75% LTV.
A PE Partner refinancing £2.4m on a £3.2m home saw mainstream calculators read his carry as zero. A holistic underwrite credited a smoothed share of four years of distributions and the refinance completed interest-only at 4.8x recognised income.
A macro trader earning a £200k base with a bonus that swung between £180k and £420k needed £1.7m for a £2.3m family home. A clearing bank averaging three full years recognised £386,000 of income and agreed the loan interest-only at roughly 4.4x.
A hedge fund analyst on a £150k base needed £1.1m for a £1.4m home after his bonus fell to £120k from £270k. A lender applying 60% of a two-year average recognised £267,000 of income, and the loan completed at roughly 4.1x with the deposit unchanged.
An operating partner at a mid-market buyout firm needed £1.3m on a £1.7m home, with income spread across fixed drawings, board fees and a volatile profit share. Built on the stable layers at roughly 4.4x, it completed on mainstream large-loan terms.
A mid-market PE director needed £1.6m for a £2.1m home; salary and bonus reached £1,425,000 at most. A private bank recognised three years of crystallised co-investment gains, taking recognised income to £375,000 and the loan to roughly 4.3x.
A sole director drawing £90k while his company retained its profit needed £1.2m of borrowing. A lender assessing salary plus share of net profit after corporation tax recognised £267,570 of income, and the loan completed at just under 4.5x with no change to his dividends.
An investment banking Director secured a £990k mortgage on a £1.1m London flat at 90% LTV using multi-year bonus income. This case study shows how bonus averaging supported borrowing while retaining funds for property works.
A private equity VP secured a £1.9m mortgage on a £2.4m family home using salary and bonus income. This case study shows how part interest-only structuring and a five-year product aligned borrowing with future carry payments.
A UK-based employee of a US technology firm secured a £2.58m remortgage using USD salary, bonus, and RSUs. This case study explains how equity compensation and foreign currency income were assessed through a private banking solution.
An equity partner at a City law firm secured a £1.55m mortgage on a £1.85m family home using LLP income. This case study shows how part interest-only structuring supported affordability during a period of higher household costs.
A fixed-income trader secured a £1.5m mortgage on a £2.1m purchase using bonus-led income. This case study explains how lender selection and income structuring supported affordability despite restrictive bonus caps.
A senior finance professional returning from Singapore secured a £950k UK mortgage on a £1.45m London apartment using overseas USD income. This case study explains how foreign currency income was assessed ahead of UK relocation.
An established equity partner at a UK law firm secured a £2.25m family home using fixed drawings and partnership profit share. This case shows how lender selection and part interest-only structuring supported uneven income and long-term affordability.
HNW client, strong liquid assets but modest declared income, needed £3m for a £5m townhouse. We placed assets under management, built an asset-based underwrite and used an investment portfolio as the repayment plan—securing a bespoke interest-only facility at 60% LTV.
Newly qualified solicitor on £110k, buying a £750k flat while in probation. We targeted a lender that may accept a signed contract and start date, leveraged a strong deposit, and packaged the case cleanly—securing an offer before probation completed.
Locum consultant doctor with £140k mixed NHS/private income secured a £770k mortgage on a £1.2m home. We used 12–24 month averaging, full contract history and locum-friendly criteria to align with a mainstream lender—delivering a clean, timely approval.
Director–shareholder, £60k salary and £120k retained profits, needed £1m borrowing without ramping dividends. We targeted a lender that may use salary + share of net profit, evidenced sustainability, and explained a one-off expense—achieving approval at an effective 5× multiple.
Management consultant contractor on £650/day (PSC), two-month gap, and IR35 scrutiny. We used day-rate modelling, a credible gap narrative, and an accountant’s letter to align with mainstream policy—achieving approval at 75% LTV on a £1.1m home.
Returning British expat paid in USD, thin UK credit, and a 60-day deadline. We secured a lender that accepts foreign income with a haircut, used a US credit report, and ran a pre-arrival application—agreeing the mortgage at 65% LTV on a £1.6m home.
Skilled Worker and Spouse visa clients, £160k income, <18 months in the UK, needed a fast new-build purchase at £800k. We shortlisted a lender comfortable with shorter residency, secured a rapid AIP, perfected the AML trail—and achieved a full offer inside 10 working days.
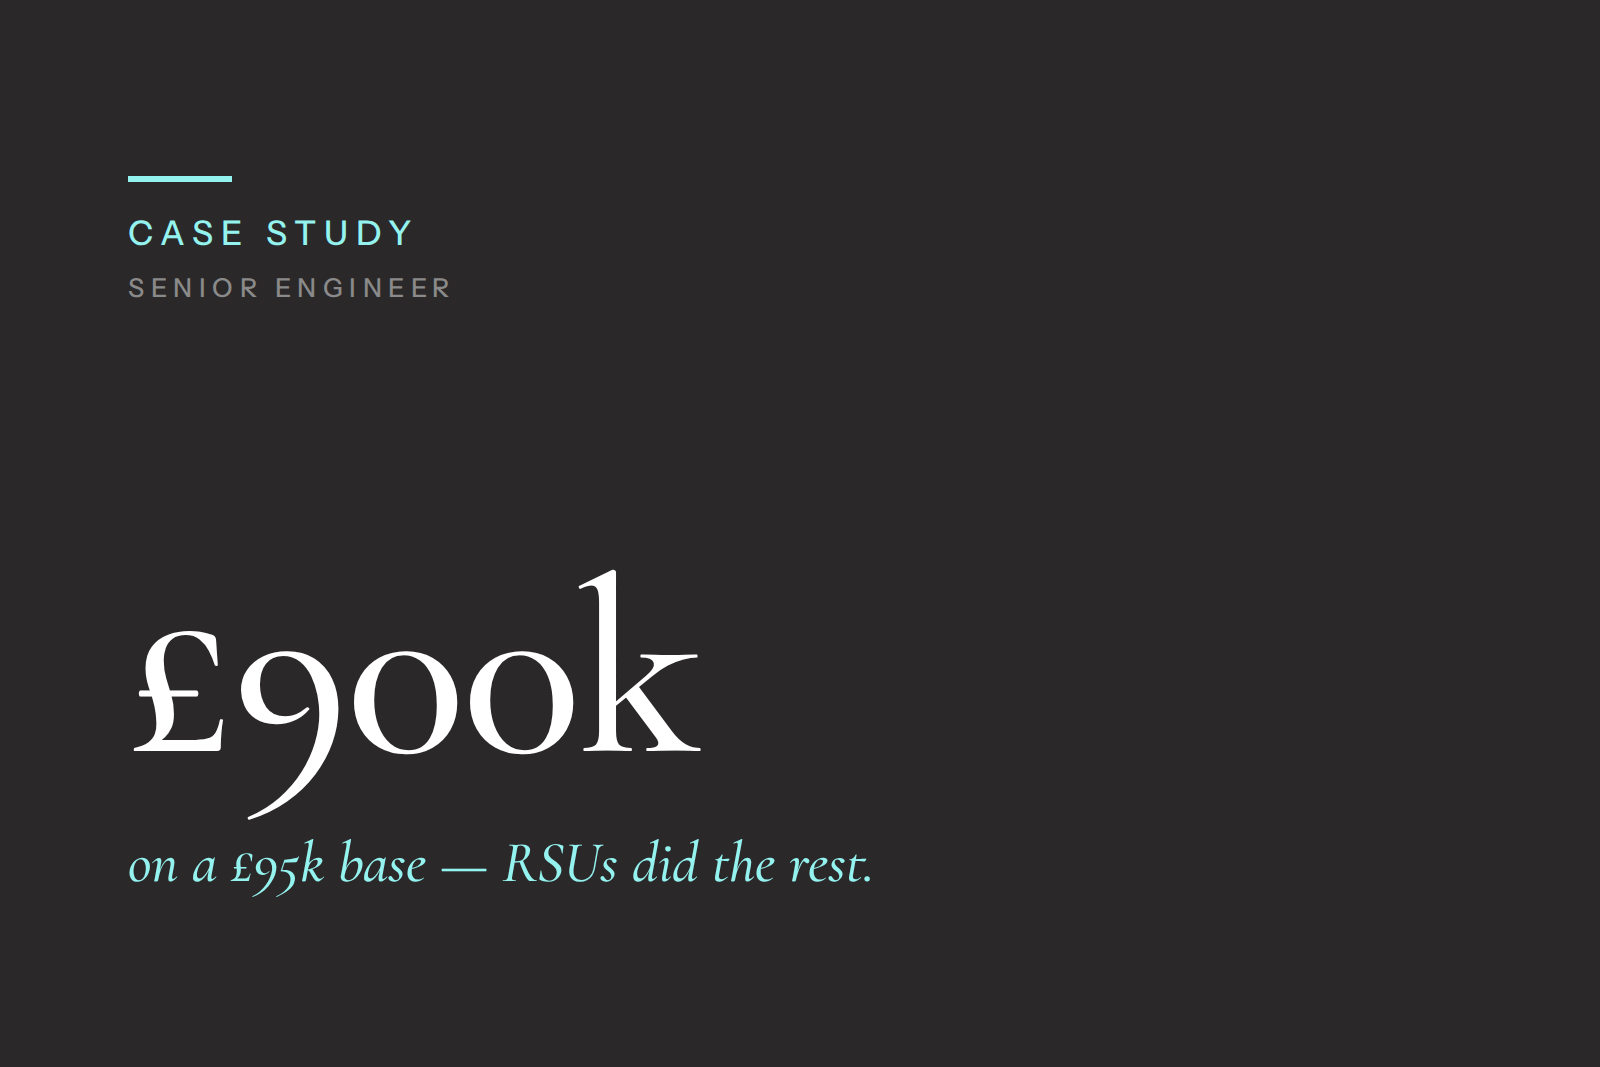
A senior software engineer on £95k with quarterly RSU vesting bought a £900k house. By averaging 12–24 months of vested RSUs and packaging award letters, brokerage statements and payslips, we evidenced sustainable equity income—resulting in approval with a part interest-only structure.
An investment banking associate on £120k base with a USD bonus needed 75% LTV on a £1.25m flat. We used a two-year average bonus, applied a foreign currency haircut, and built a strong evidence pack—resulting in c.5.2× income and a successful offer.
A City lawyer and LLP partner with £420k variable profit share bought a £2.1m London family home at 60% LTV. We targeted a lender that may average three years’ profits, clarified the capital account, and structured part interest-only with an evidenced repayment plan.
With renewals and short gaps, this IT contractor needed day‑rate treatment. We evidenced continuity, explained the gaps, and matched them with a lender that assesses on day‑rate—securing borrowing aligned to realistic annualised earnings.
A newly qualified solicitor with limited employment history needed clarity and pace. We used her offer letter and first payslips, applied professional‑criteria know‑how, and packaged a clean, conservative case—helping a mainstream lender say yes without over‑promising.
Briefs, arrears, and variable fee sheets—this barrister’s earnings were anything but tidy. We evidenced sustainability and secured a suitable mortgage at pace—without over‑promising.
A senior partner had to choose between a private bank and a high‑street lender for £2m. The private bank’s full interest‑only structure won—keeping monthly payments steady and letting annual profit share reduce the balance without hassle.
A newly made‑up equity partner needed a high‑value mortgage against uneven drawings and profit share. We evidenced sustainability, clarified tax and capital contributions, and matched them with a lender that considers partner income—without overstretching.
An IT Sales Director and Teacher with two children needed £800k to upsize to a £1.2m home. We secured 5.5x income using 100% of bonuses and structured part of the loan on interest-only — keeping monthly payments affordable with a plan to reduce the balance using future bonuses.
YOUR HOME MAY BE REPOSESSED IF YOU DON’T KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
APPROVED BY THE OPENWORK PARTNERSHIP ON 12/08/2025