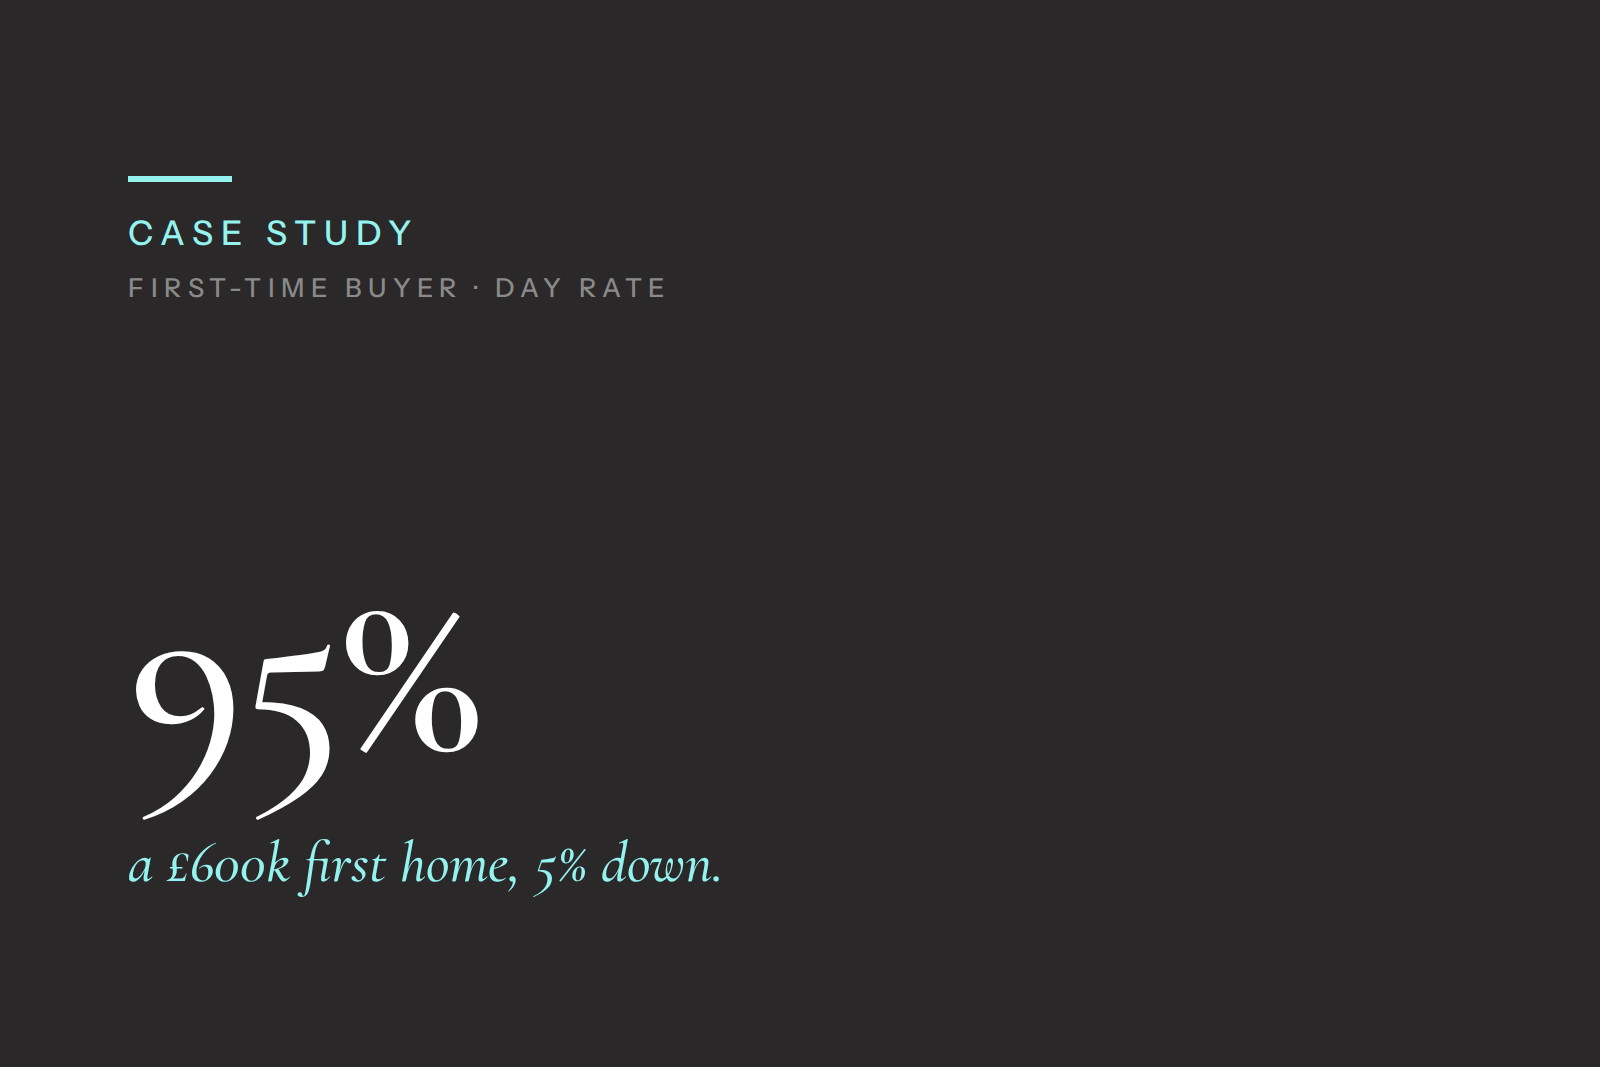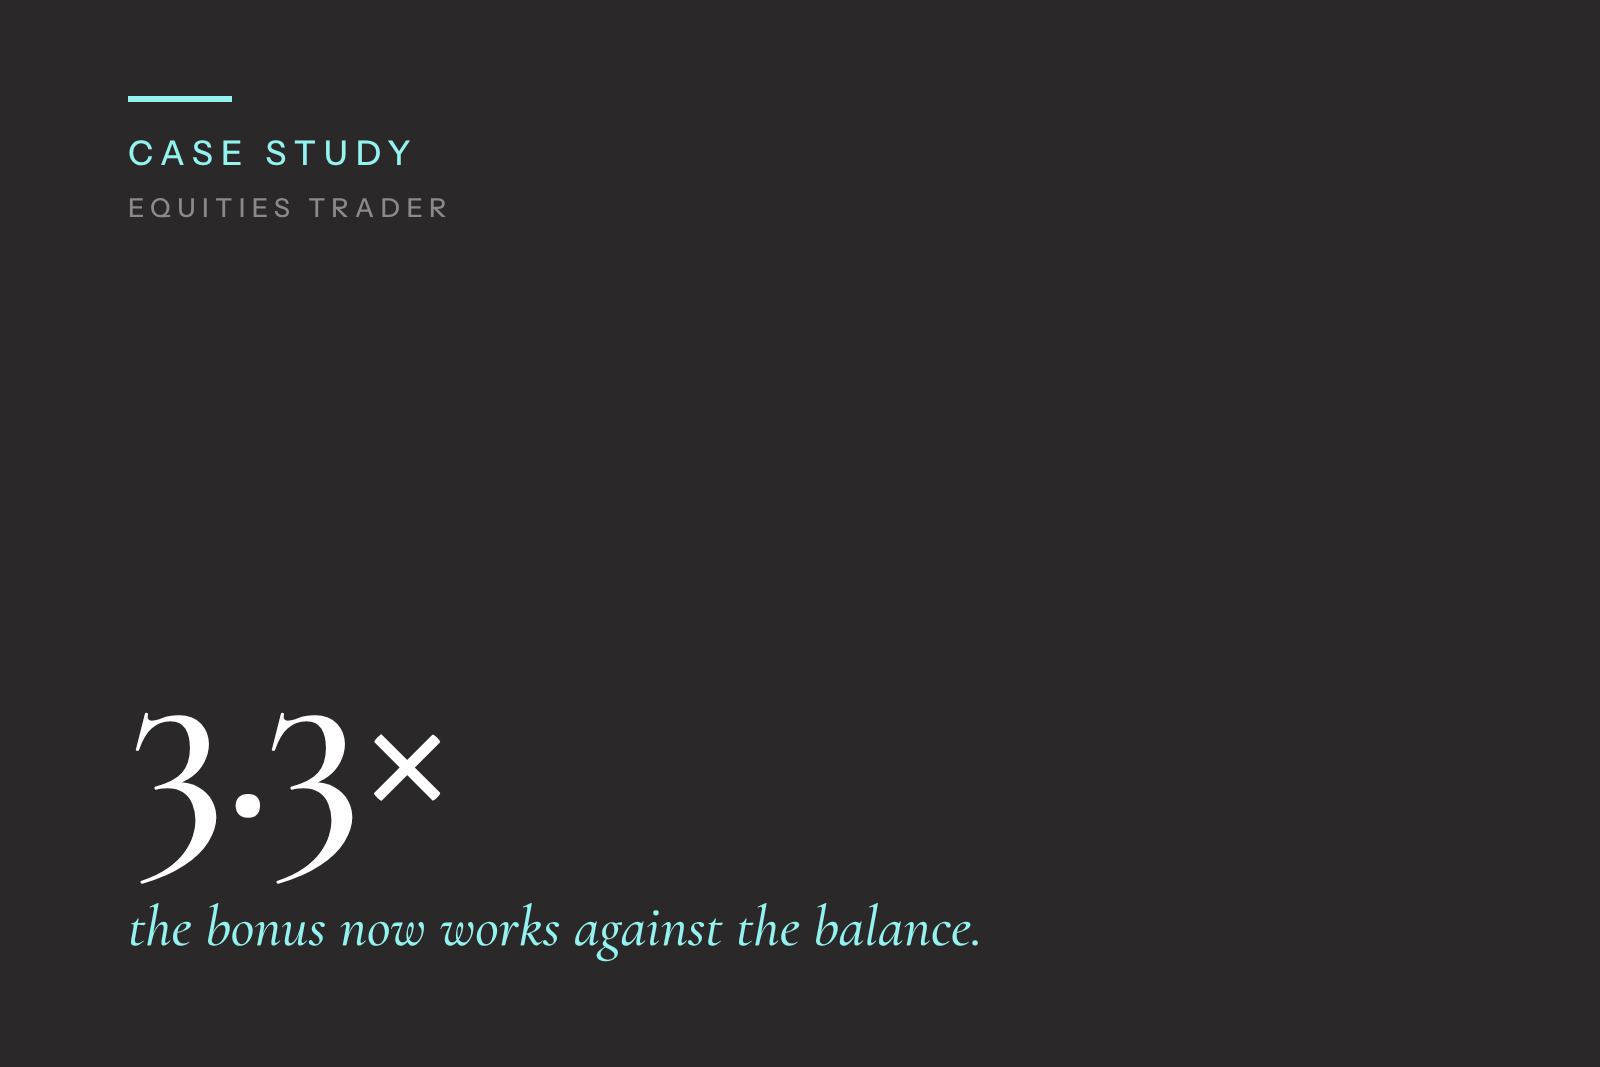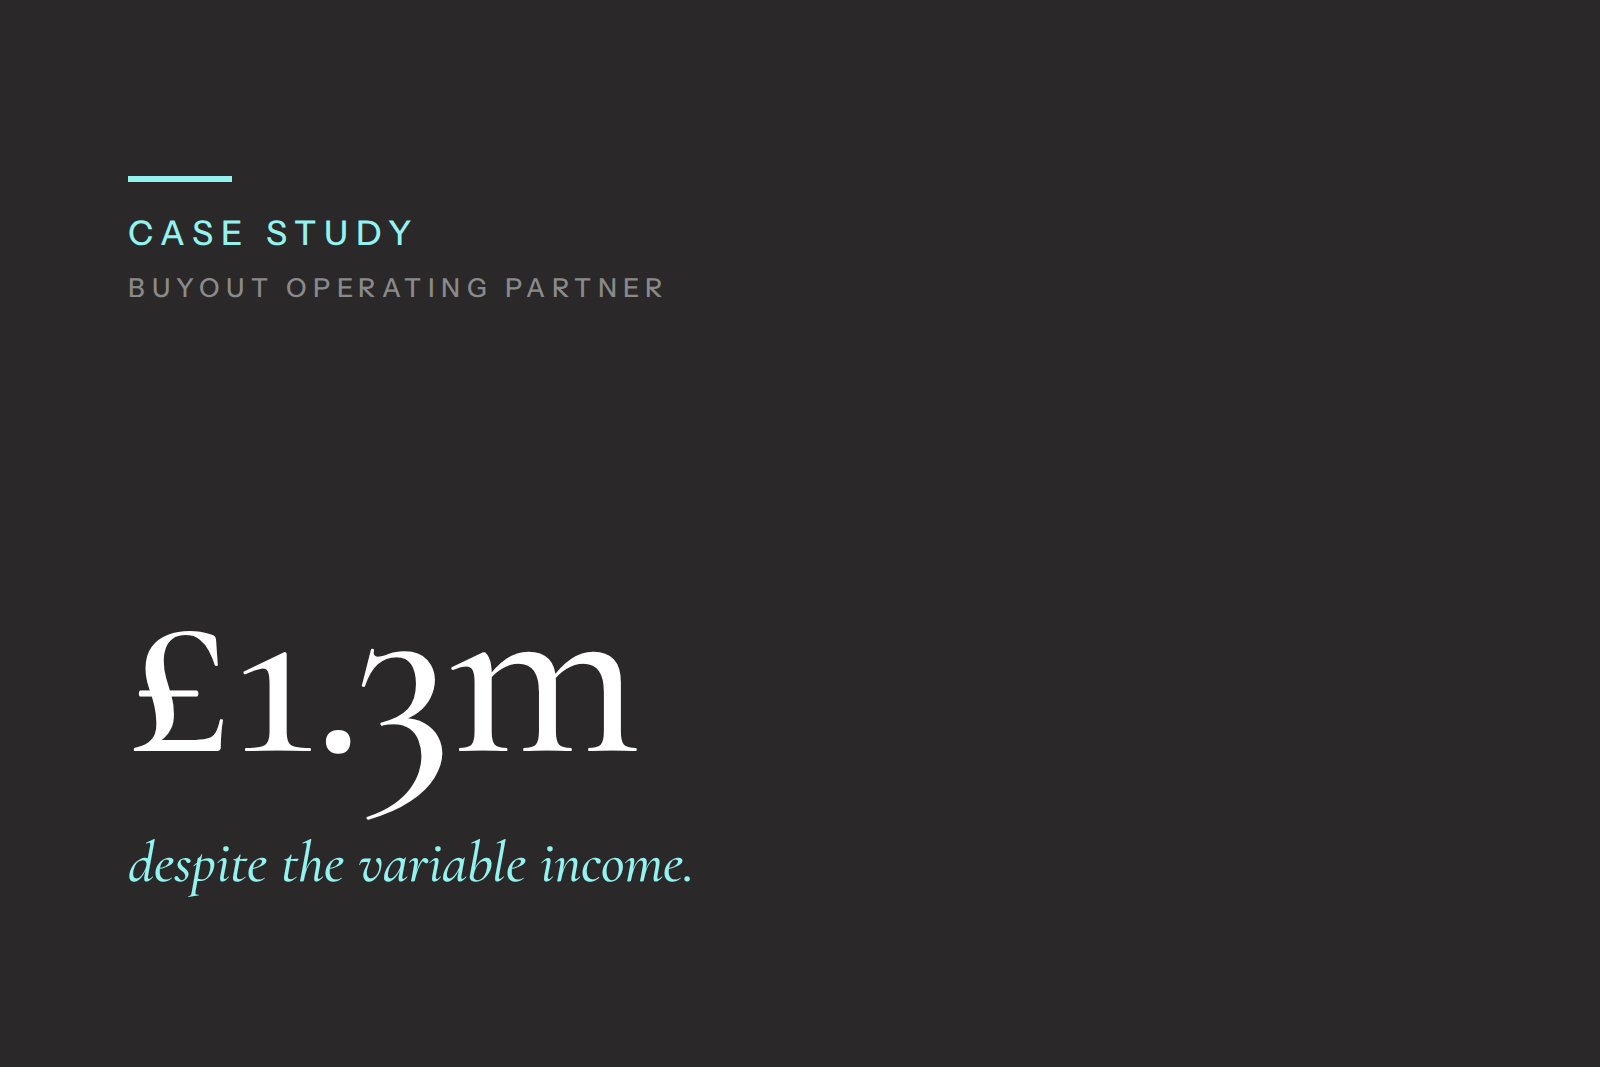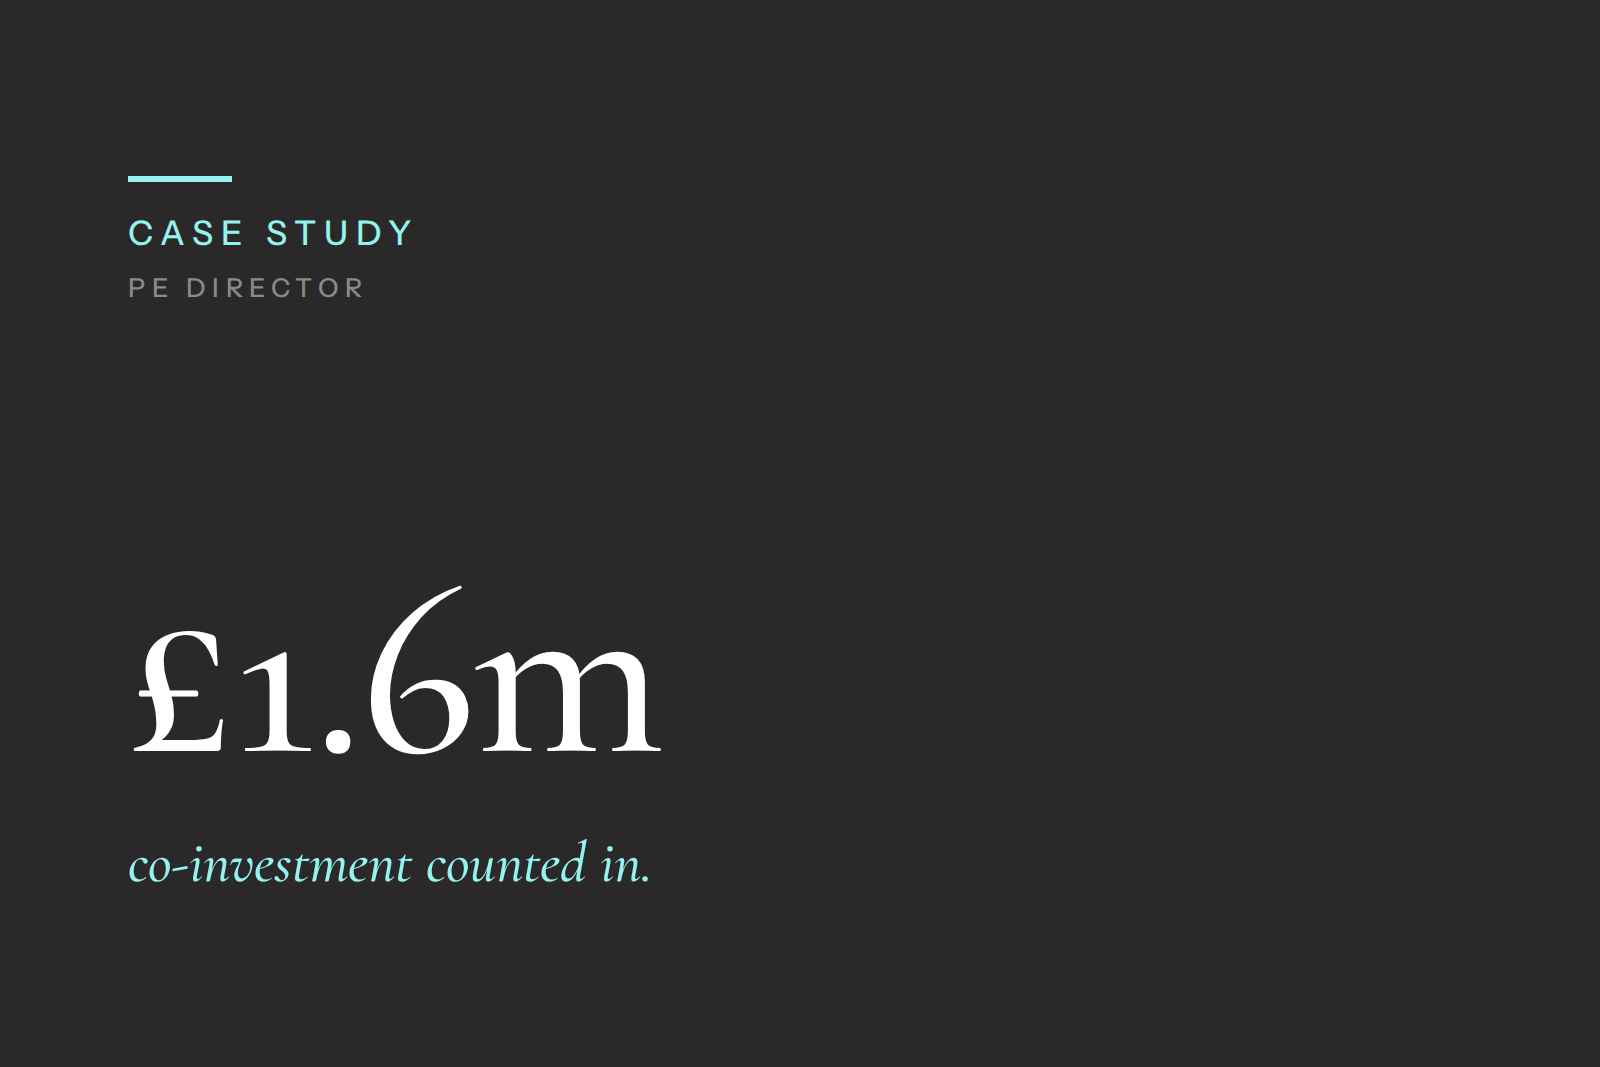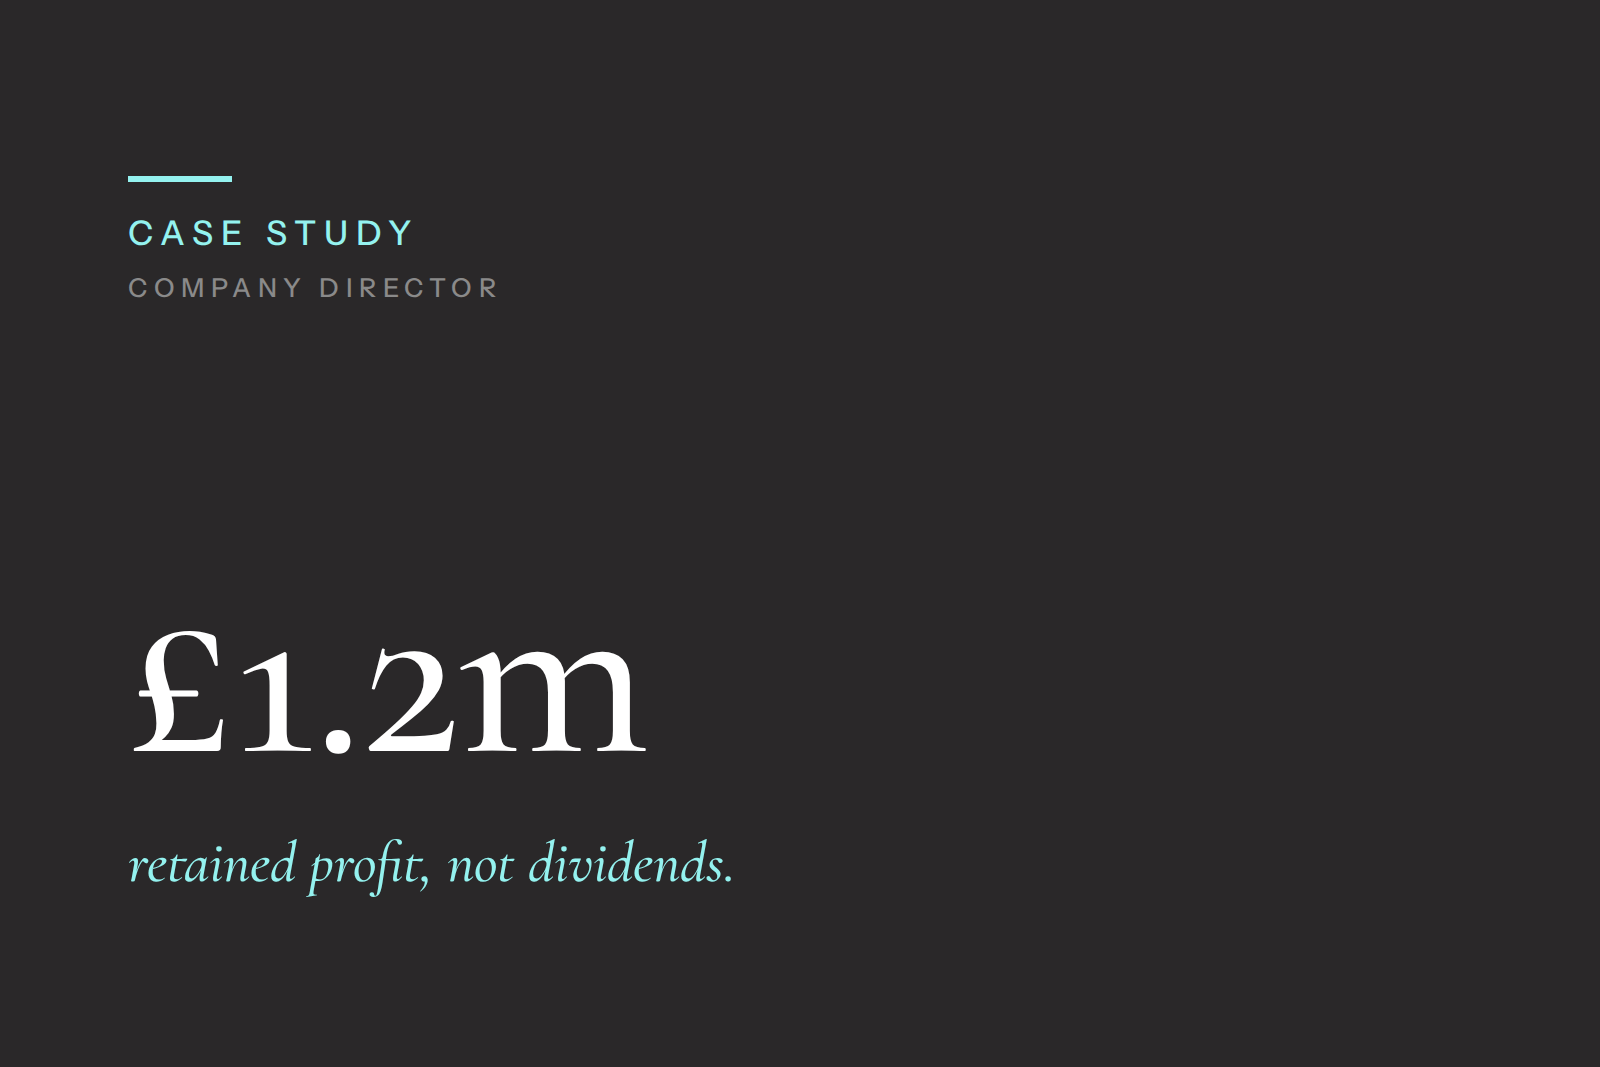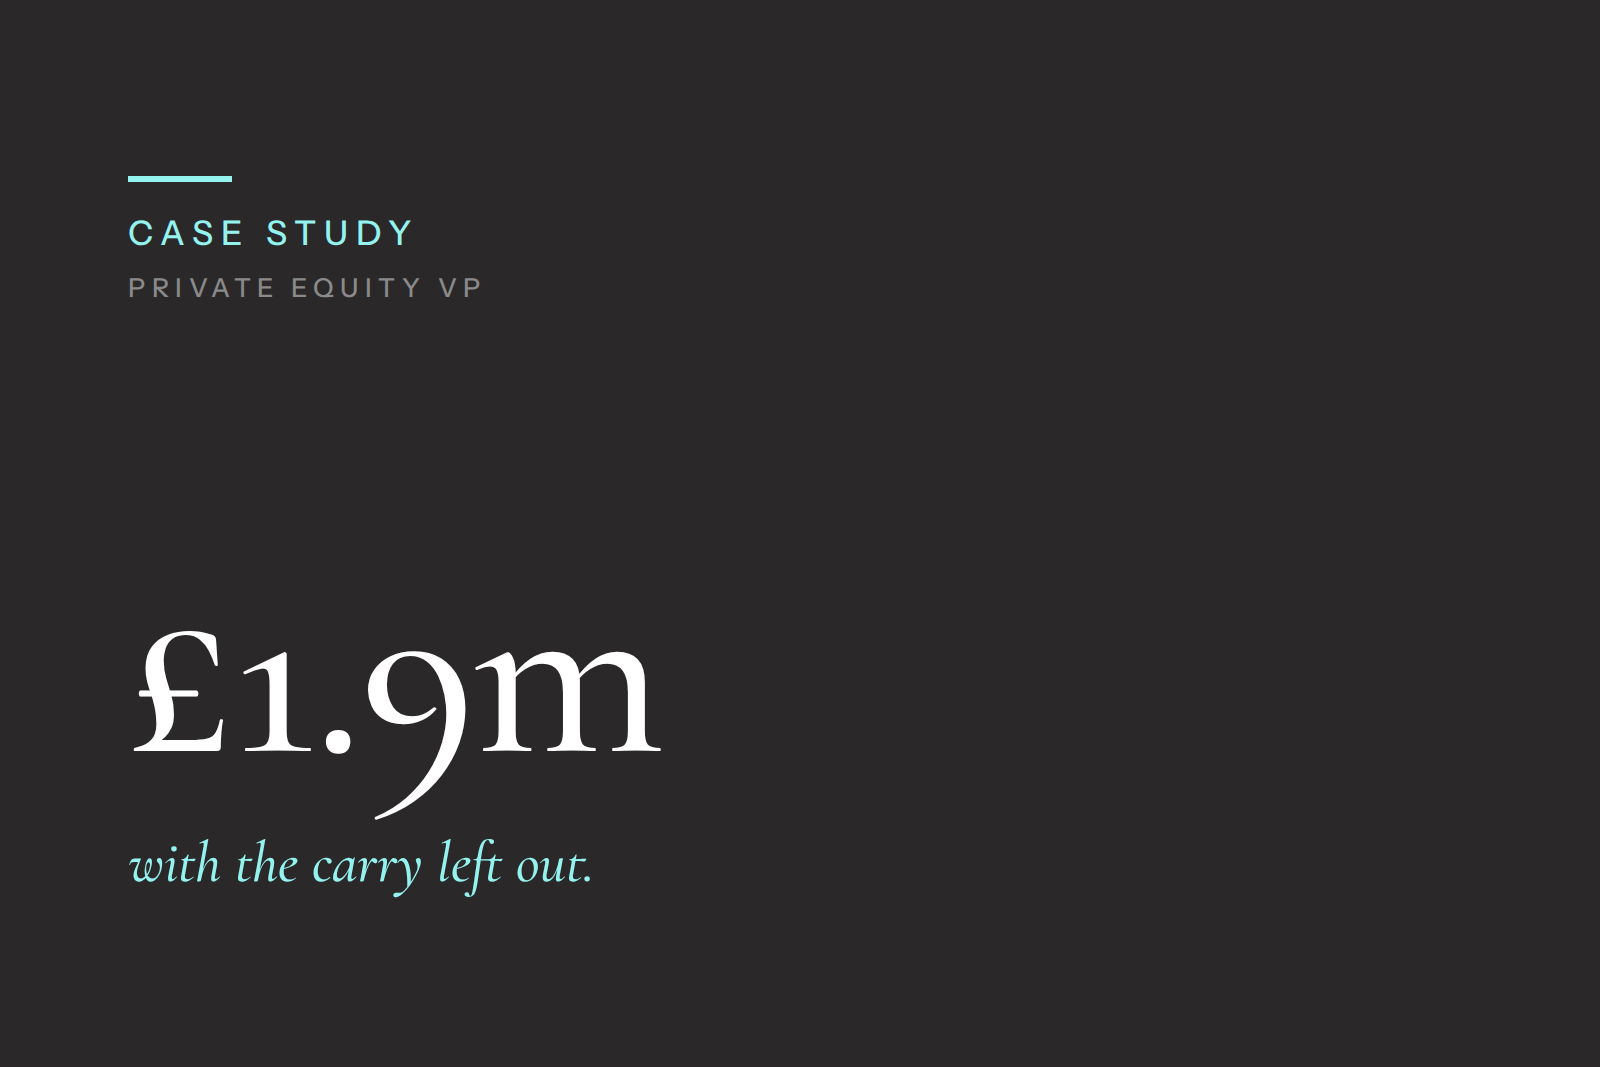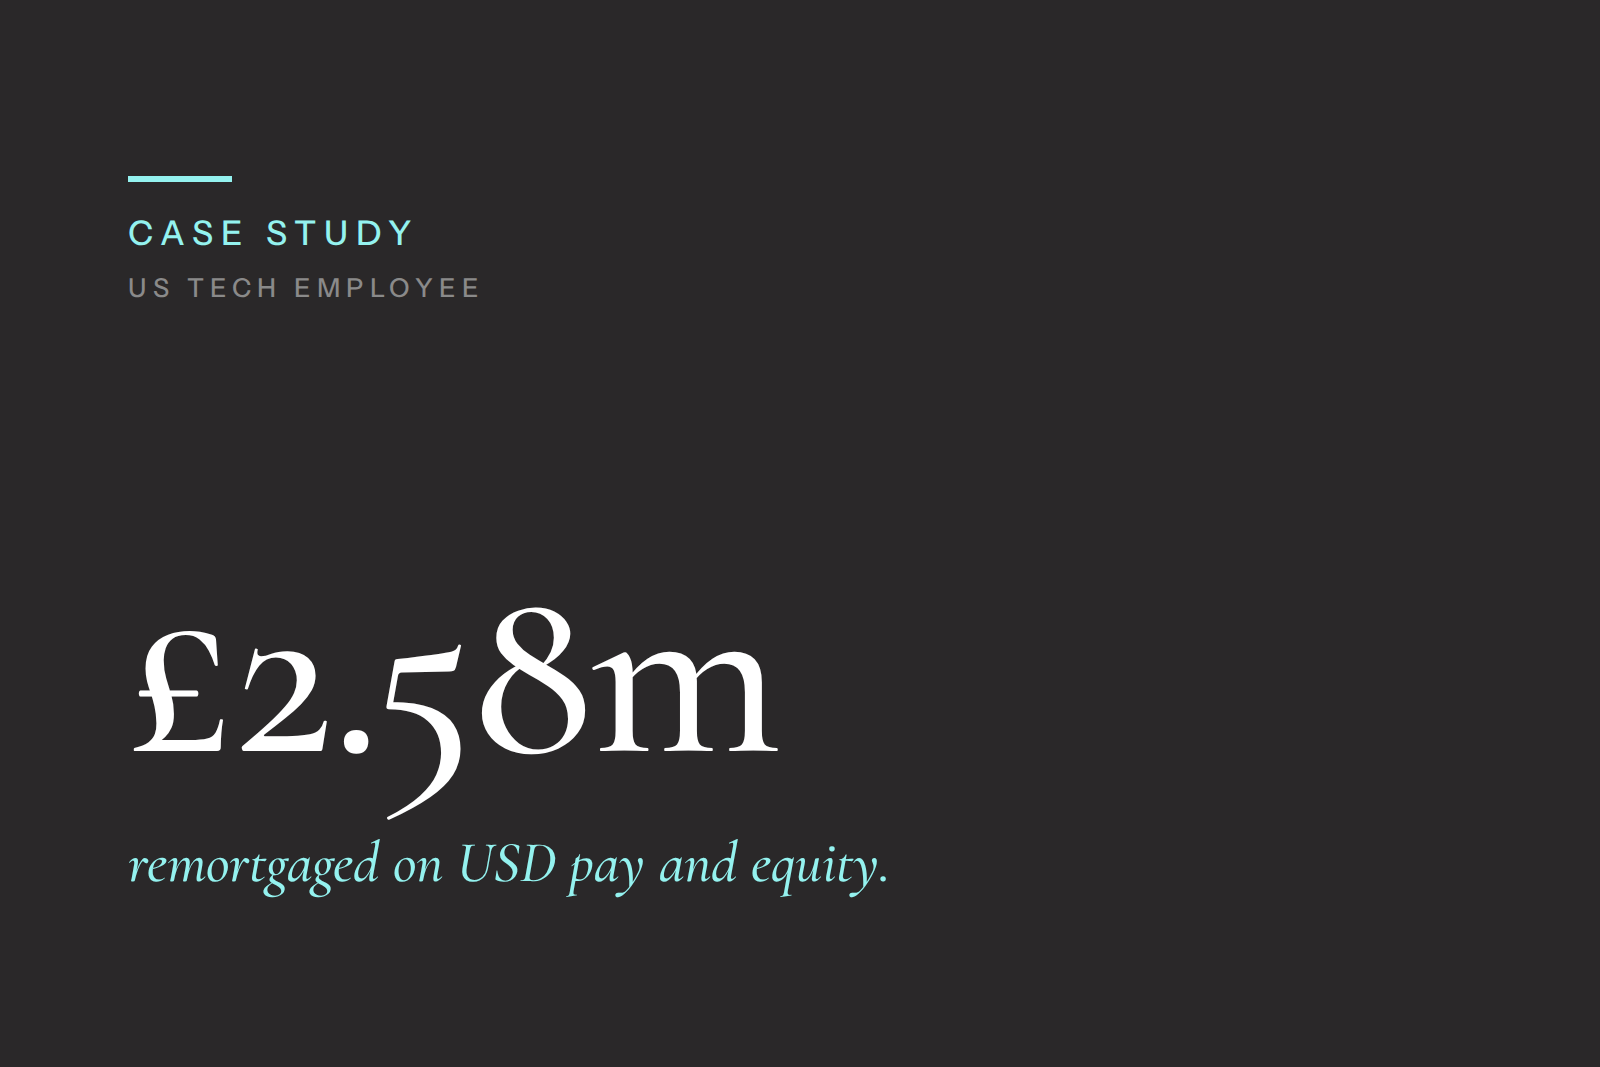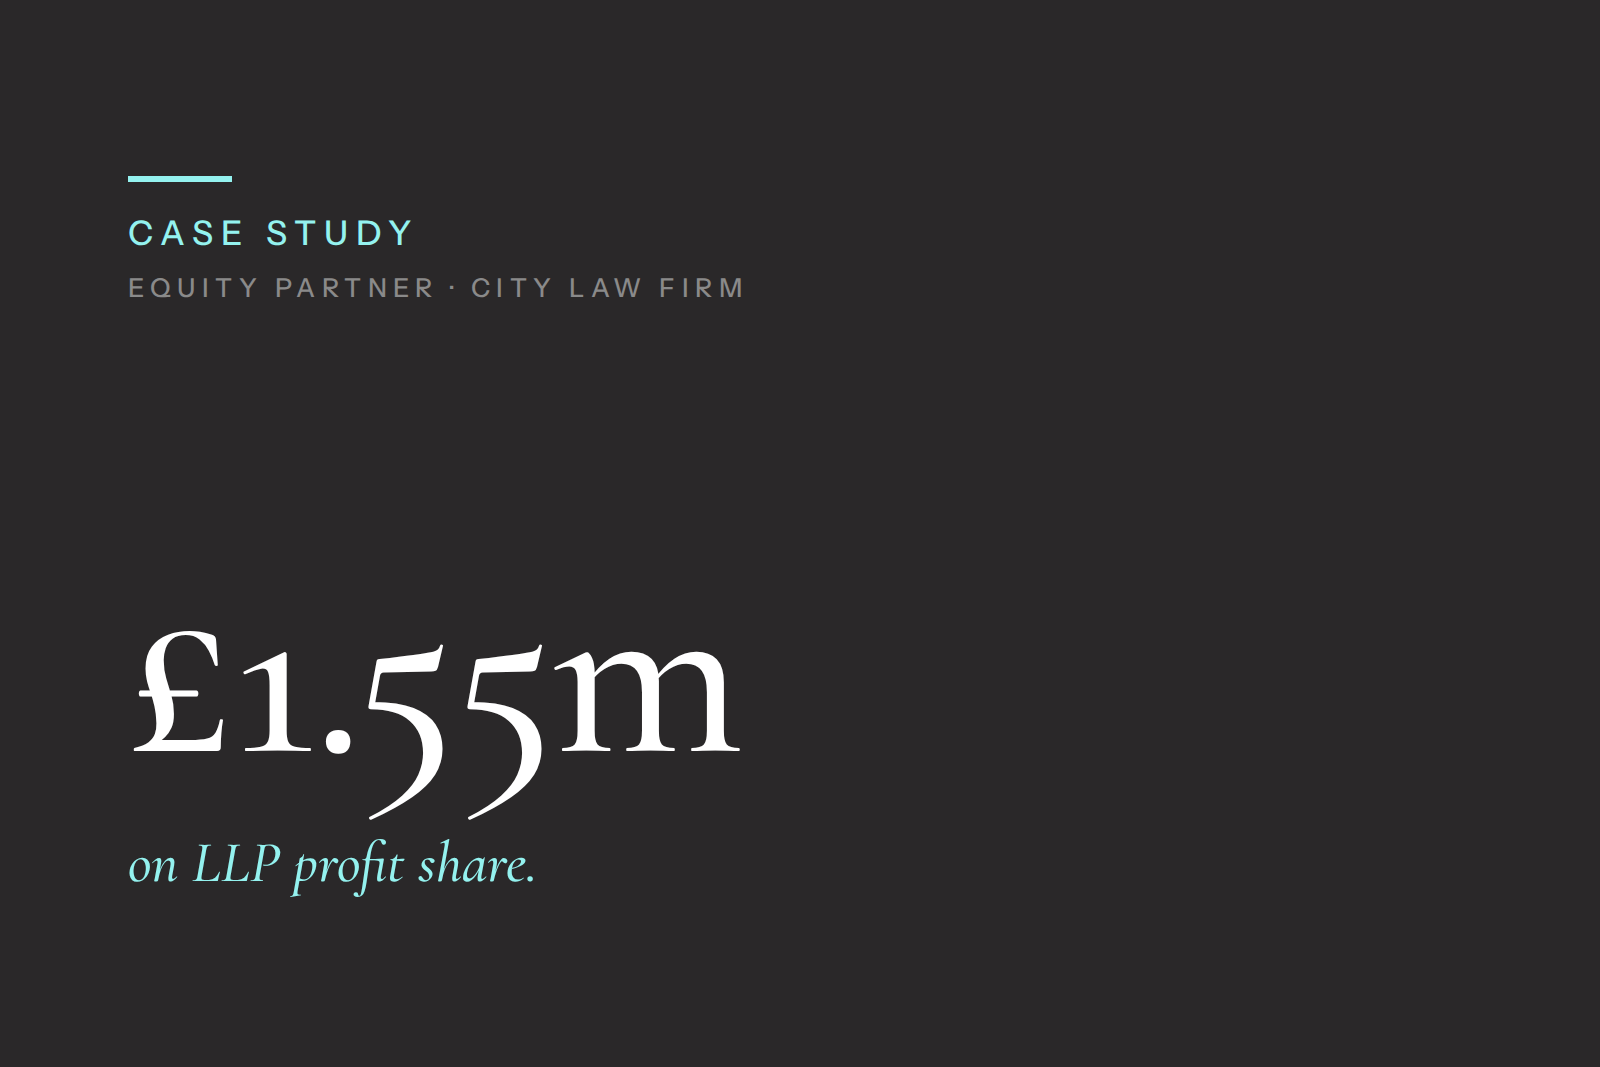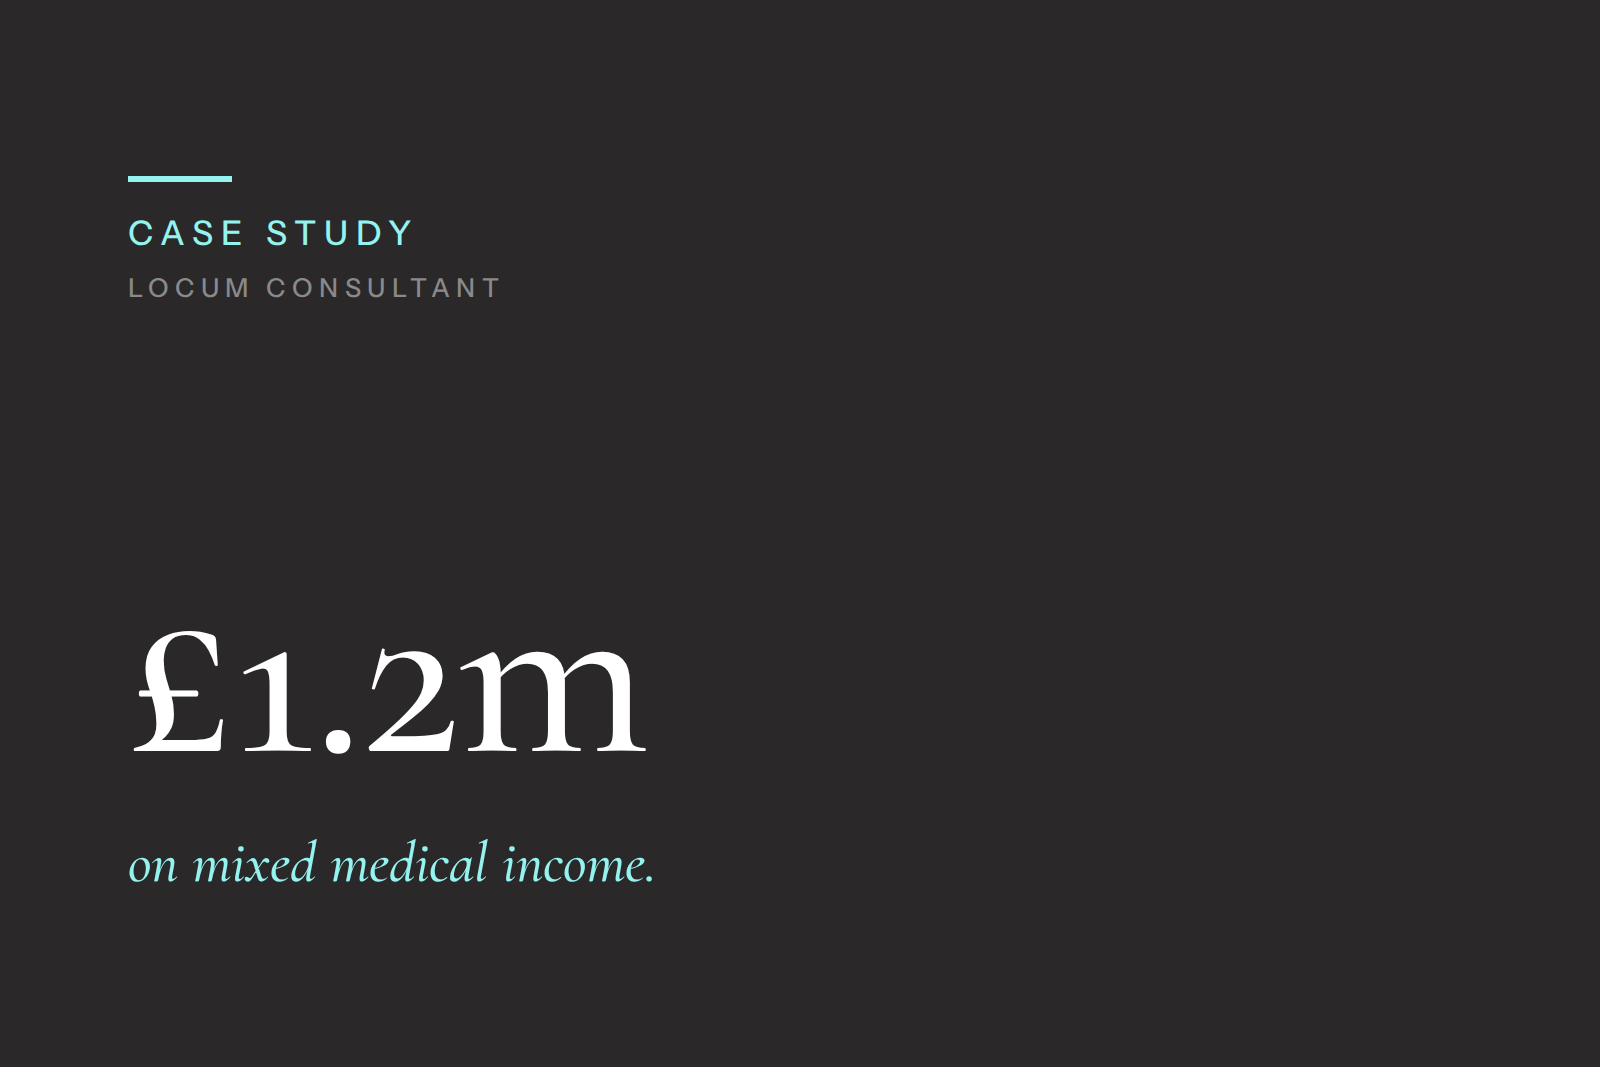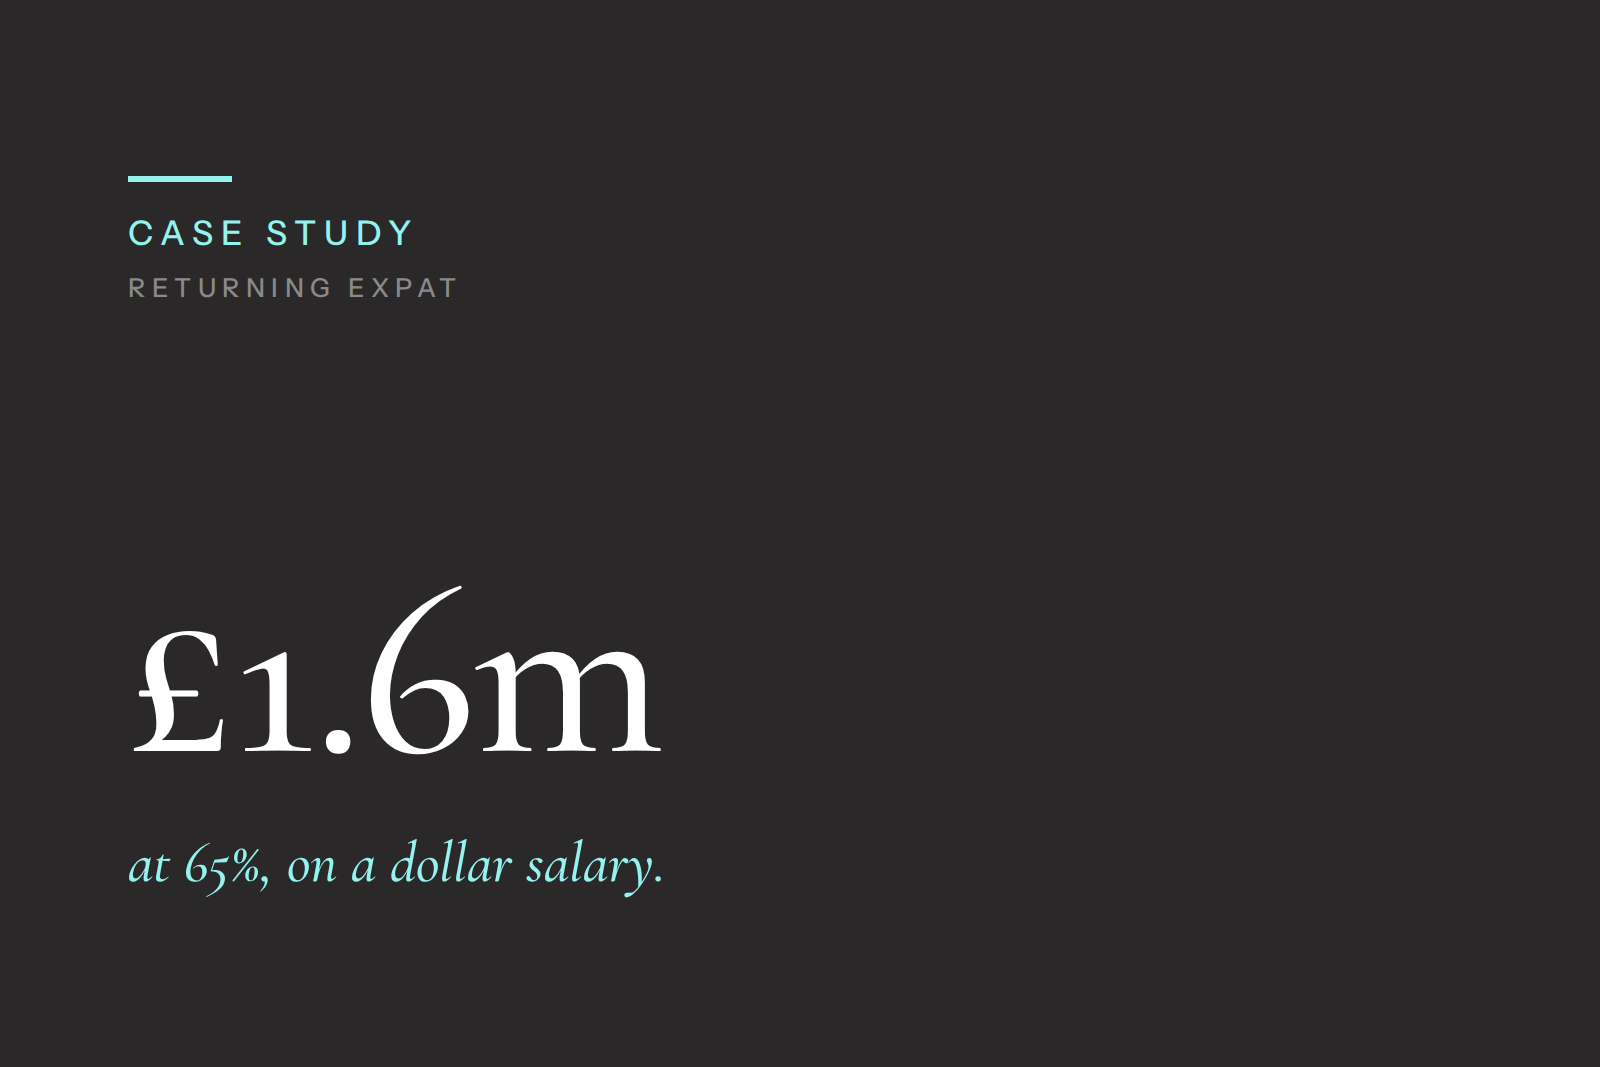High Loan-to-Income Refinance Using Latest Bonus Income
DIRECTOR AND MORTGAGE ADVISER
Specialist broker for high-earning professionals and complex income cases.
Request your fee free mortgage consultation today. No obligation, just sound advice.
Overview
An associate at a London law firm approached us looking to refinance his existing property in order to buy out his former partner. His income included a basic salary and substantial annual performance-related bonuses. With no dependants and strong affordability, the client needed to maximise borrowing and utilise his latest bonus income to remain in the property.
The Challenge
Many lenders calculate bonus income based on a two-year average, which would have significantly reduced the client’s borrowing potential. To buy out his former partner, he needed to stretch both loan-to-income and affordability. A high loan amount in his sole name was essential, and preserving the home was a priority—to avoid moving, incurring stamp duty, and additional legal and estate agent fees.
Speak To An Expert Today
Get in touch for a fee free, no-obligation chat about how we might be able to help you.
Our Solution
We sourced a lender willing to use the most recent bonus alone—rather than averaging over two years—which reflected the client’s current income trajectory and increased borrowing capacity. The lender also offered an income multiple of 5.5 times salary and accepted full use of his bonus income thanks to his strong financial profile. To manage ongoing repayments, we structured the loan over a longer term while selecting a product with a generous overpayment allowance, allowing the client to reduce the effective term using future bonuses.
The Outcome
The client was able to refinance the property into his sole name, securing a loan large enough to buy out his ex-partner and remain in the home. With flexible repayment terms and the ability to reduce the loan balance over time, this solution gave him control over his financial future while avoiding unnecessary moving costs.
What We Can Do for You
Complex income structures, partnership splits, and refinancing challenges don’t have to mean starting over. We know how to make lender criteria work in your favour—especially when income is made up of variable elements like bonuses. If you're looking to retain your home and need to borrow more than standard routes allow, we’re here to help.
Read our full guide to mortgages for newly promoted partners →
Request your fee free mortgage consultation today. No obligation, just sound advice.
Related Case Studies
Half his deposit was a developer incentive and he had received one bonus. A high street lender accepted both — £157,500 of recognised income, £675,000 at 90% LTV, roughly 4.3x, with a new-build offer that flexes to the completion date.
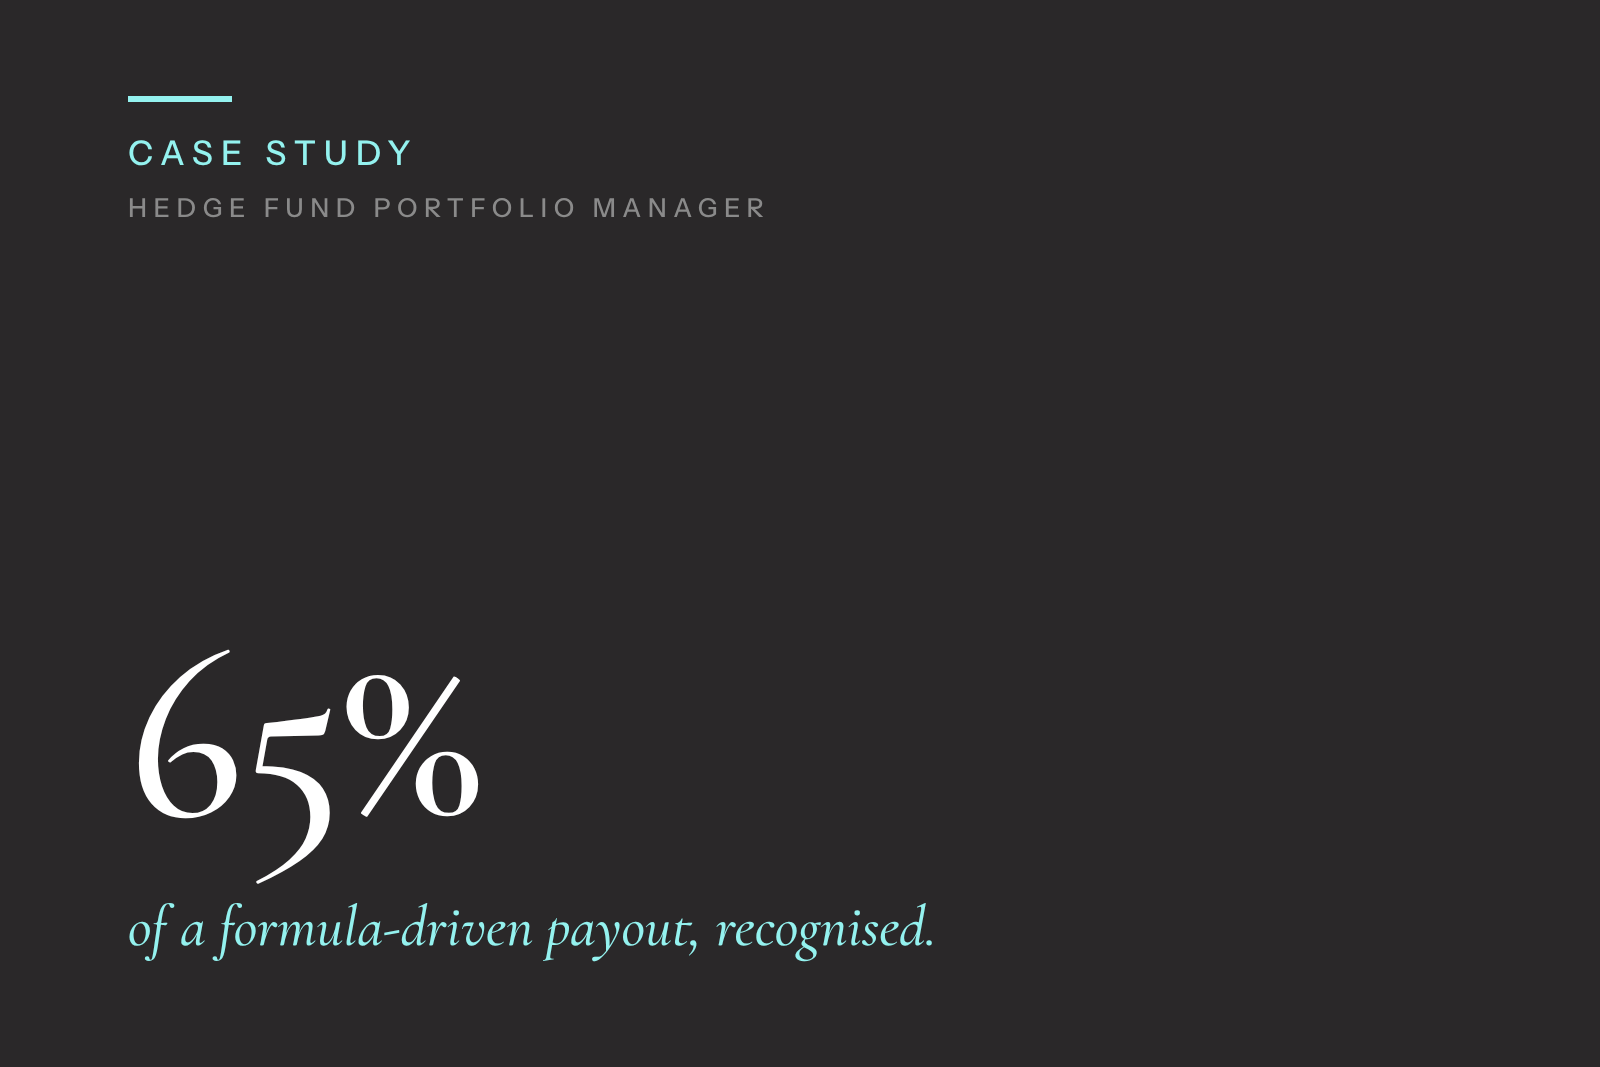
A hedge fund portfolio manager on a £180k base, paid a fixed share of his book’s performance fees, needed £2.4m interest-only on a £3.25m home. A clearing bank’s large-loan team recognised £453,000 of income and lent at roughly 5.3x.
Told to wait two years for accounts, a software developer on a £575 day rate bought his first home instead. A high street contractor policy annualised the rate to £132,250 and lent £570,000 at 95% LTV, roughly 4.3x, with his renovation fund intact.
An equities trader on a £160k base and a £200k average annual bonus was ending a fix on an £850k mortgage against his £1.2m London home. A remortgage to a clearing-bank offset product recognised £260,000 of income at roughly 3.3x — and each bonus now works against the balance from the day it lands.
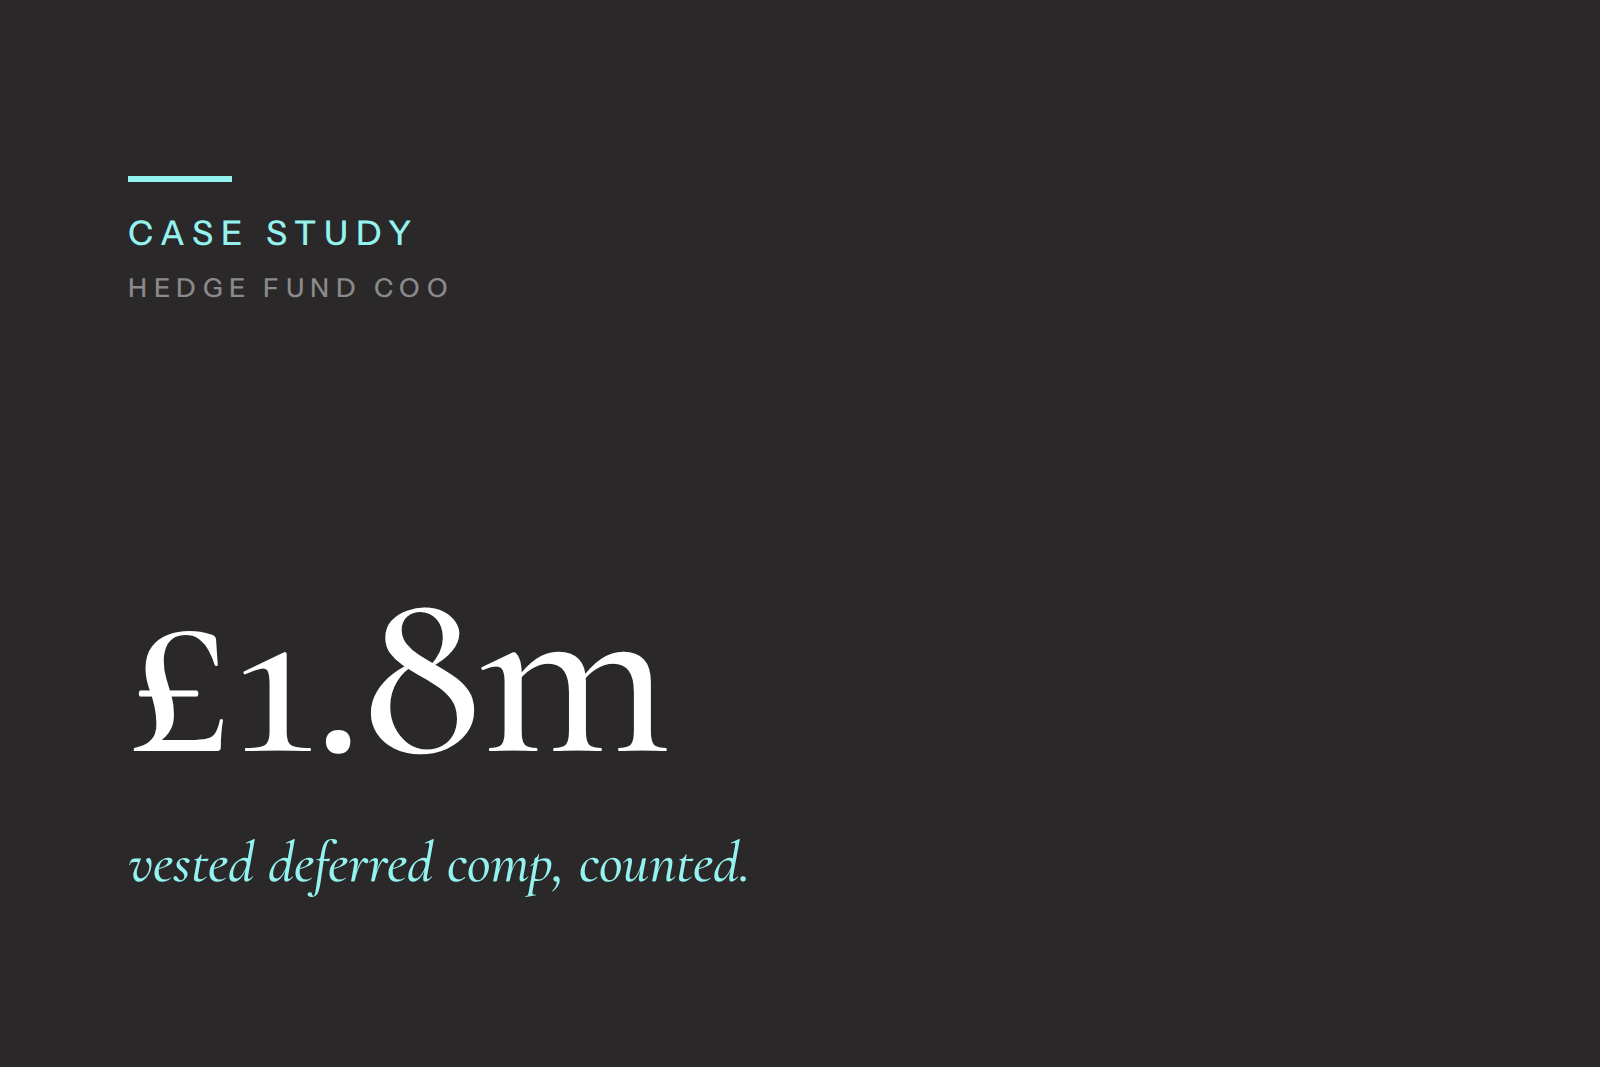
A hedge fund COO with half his bonus deferred needed to refinance £1.8m on a £2.5m home before his fix expired. A clearing bank counted the vested tranches paid through payroll, recognising £400,000 of income, and the remortgage completed at 4.5x.
An American VP on a Skilled Worker visa, 18 months into a London posting, needed £900,000 for a £1.2m house. A large international bank whose criteria let income override residency recognised £238,400 including his USD bonus; completed at 75% LTV.
A PE Partner refinancing £2.4m on a £3.2m home saw mainstream calculators read his carry as zero. A holistic underwrite credited a smoothed share of four years of distributions and the refinance completed interest-only at 4.8x recognised income.
A macro trader earning a £200k base with a bonus that swung between £180k and £420k needed £1.7m for a £2.3m family home. A clearing bank averaging three full years recognised £386,000 of income and agreed the loan interest-only at roughly 4.4x.
A hedge fund analyst on a £150k base needed £1.1m for a £1.4m home after his bonus fell to £120k from £270k. A lender applying 60% of a two-year average recognised £267,000 of income, and the loan completed at roughly 4.1x with the deposit unchanged.
An operating partner at a mid-market buyout firm needed £1.3m on a £1.7m home, with income spread across fixed drawings, board fees and a volatile profit share. Built on the stable layers at roughly 4.4x, it completed on mainstream large-loan terms.
A mid-market PE director needed £1.6m for a £2.1m home; salary and bonus reached £1,425,000 at most. A private bank recognised three years of crystallised co-investment gains, taking recognised income to £375,000 and the loan to roughly 4.3x.
A sole director drawing £90k while his company retained its profit needed £1.2m of borrowing. A lender assessing salary plus share of net profit after corporation tax recognised £267,570 of income, and the loan completed at just under 4.5x with no change to his dividends.
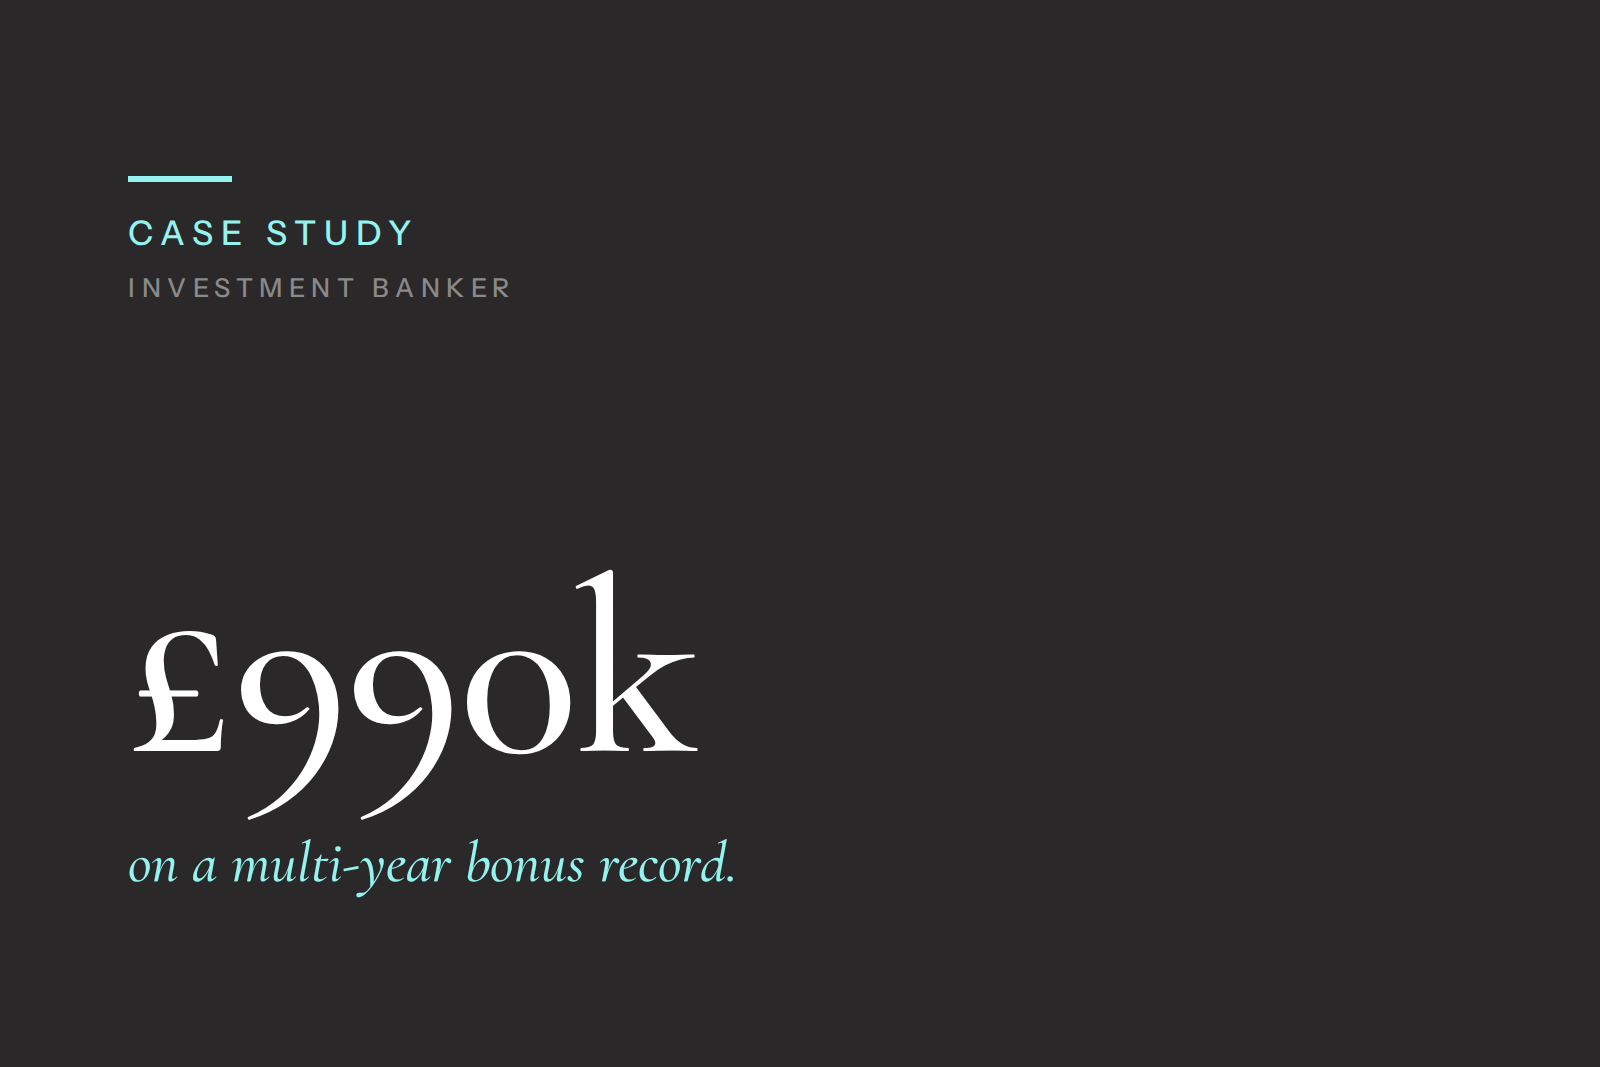
An investment banking Director secured a £990k mortgage on a £1.1m London flat at 90% LTV using multi-year bonus income. This case study shows how bonus averaging supported borrowing while retaining funds for property works.
A private equity VP secured a £1.9m mortgage on a £2.4m family home using salary and bonus income. This case study shows how part interest-only structuring and a five-year product aligned borrowing with future carry payments.
A UK-based employee of a US technology firm secured a £2.58m remortgage using USD salary, bonus, and RSUs. This case study explains how equity compensation and foreign currency income were assessed through a private banking solution.
An equity partner at a City law firm secured a £1.55m mortgage on a £1.85m family home using LLP income. This case study shows how part interest-only structuring supported affordability during a period of higher household costs.
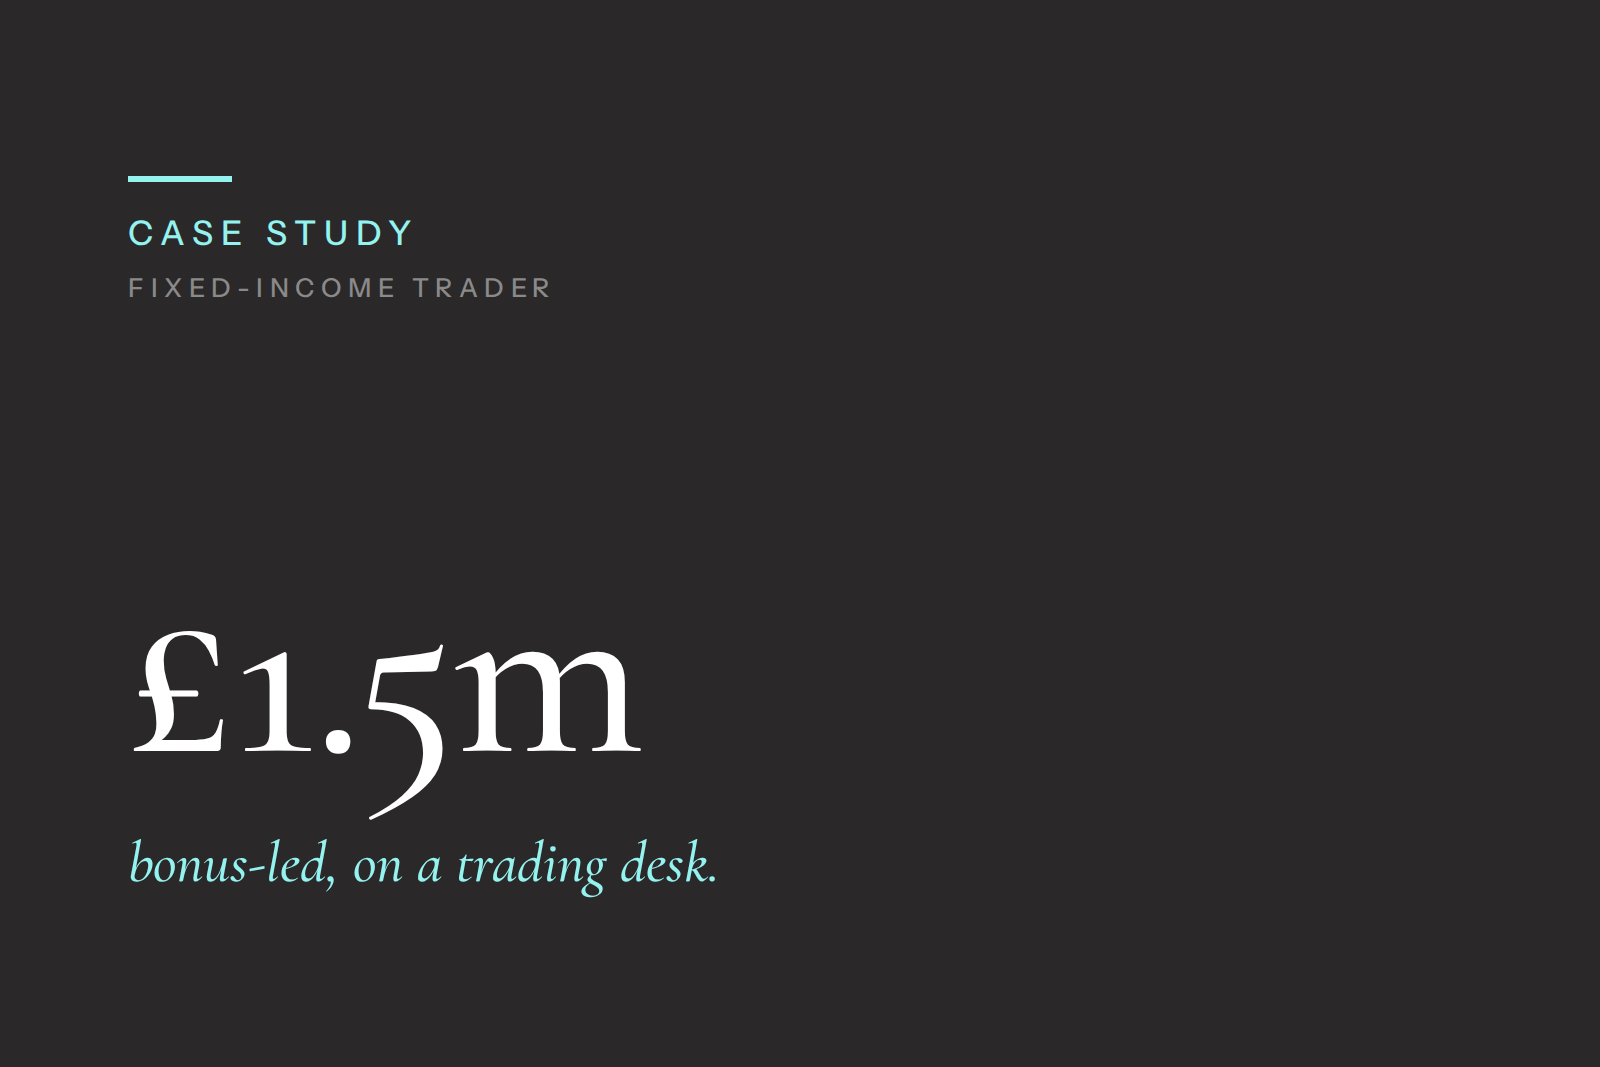
A fixed-income trader secured a £1.5m mortgage on a £2.1m purchase using bonus-led income. This case study explains how lender selection and income structuring supported affordability despite restrictive bonus caps.
A senior finance professional returning from Singapore secured a £950k UK mortgage on a £1.45m London apartment using overseas USD income. This case study explains how foreign currency income was assessed ahead of UK relocation.
An established equity partner at a UK law firm secured a £2.25m family home using fixed drawings and partnership profit share. This case shows how lender selection and part interest-only structuring supported uneven income and long-term affordability.
HNW client, strong liquid assets but modest declared income, needed £3m for a £5m townhouse. We placed assets under management, built an asset-based underwrite and used an investment portfolio as the repayment plan—securing a bespoke interest-only facility at 60% LTV.
Newly qualified solicitor on £110k, buying a £750k flat while in probation. We targeted a lender that may accept a signed contract and start date, leveraged a strong deposit, and packaged the case cleanly—securing an offer before probation completed.
Locum consultant doctor with £140k mixed NHS/private income secured a £770k mortgage on a £1.2m home. We used 12–24 month averaging, full contract history and locum-friendly criteria to align with a mainstream lender—delivering a clean, timely approval.
Director–shareholder, £60k salary and £120k retained profits, needed £1m borrowing without ramping dividends. We targeted a lender that may use salary + share of net profit, evidenced sustainability, and explained a one-off expense—achieving approval at an effective 5× multiple.
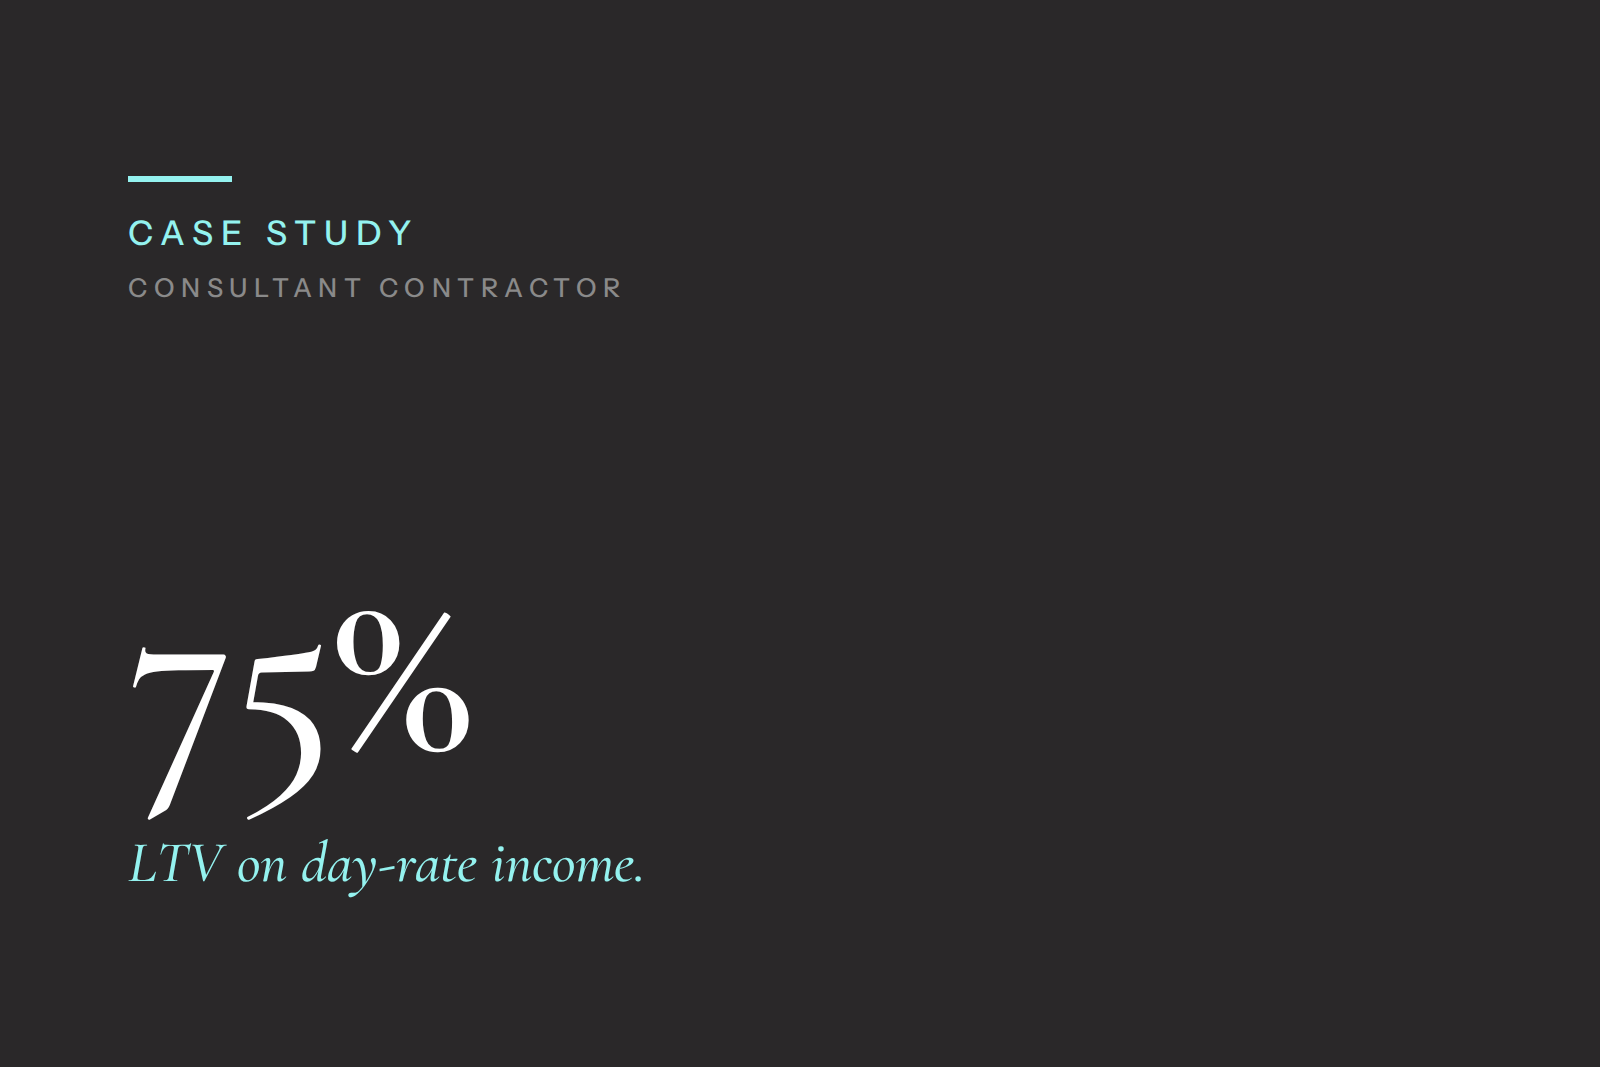
Management consultant contractor on £650/day (PSC), two-month gap, and IR35 scrutiny. We used day-rate modelling, a credible gap narrative, and an accountant’s letter to align with mainstream policy—achieving approval at 75% LTV on a £1.1m home.
Returning British expat paid in USD, thin UK credit, and a 60-day deadline. We secured a lender that accepts foreign income with a haircut, used a US credit report, and ran a pre-arrival application—agreeing the mortgage at 65% LTV on a £1.6m home.
Skilled Worker and Spouse visa clients, £160k income, <18 months in the UK, needed a fast new-build purchase at £800k. We shortlisted a lender comfortable with shorter residency, secured a rapid AIP, perfected the AML trail—and achieved a full offer inside 10 working days.
A senior software engineer on £95k with quarterly RSU vesting bought a £900k house. By averaging 12–24 months of vested RSUs and packaging award letters, brokerage statements and payslips, we evidenced sustainable equity income—resulting in approval with a part interest-only structure.
An investment banking associate on £120k base with a USD bonus needed 75% LTV on a £1.25m flat. We used a two-year average bonus, applied a foreign currency haircut, and built a strong evidence pack—resulting in c.5.2× income and a successful offer.
A City lawyer and LLP partner with £420k variable profit share bought a £2.1m London family home at 60% LTV. We targeted a lender that may average three years’ profits, clarified the capital account, and structured part interest-only with an evidenced repayment plan.
With renewals and short gaps, this IT contractor needed day‑rate treatment. We evidenced continuity, explained the gaps, and matched them with a lender that assesses on day‑rate—securing borrowing aligned to realistic annualised earnings.
YOUR HOME MAY BE REPOSESSED IF YOU DON’T KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
APPROVED BY THE OPENWORK PARTNERSHIP ON 27/06/2025