
Returning Expat Secures £950k UK Mortgage on £1.45m Purchase Using Foreign Currency Income
A senior finance professional returning to the UK secured a residential mortgage before relocation, using overseas employment income paid in USD. The mortgage was structured to support a £1.45m London purchase ahead of the client’s return.
Client Snapshot
Profession: Senior finance professional
Location: Returning to the UK from Singapore
Property Type: London city apartment
Purchase Price: £1,450,000
Mortgage Amount: £950,000
Loan-to-Value: 65%
Income Structure: Overseas employment income paid in USD (base + bonus)
Employment Status: Employed overseas, returning to UK
Context
The client was in the process of relocating from Singapore to London following a senior career move. The objective was to secure a permanent UK home prior to arrival, avoiding short-term accommodation and multiple moves once back in the UK.
Although income was strong and stable, it was earned overseas and paid in foreign currency. The mortgage therefore needed to be approved before UK employment commenced, while ensuring affordability was assessed realistically and conservatively.
The Challenge
UK mortgage lenders vary significantly in their treatment of:
Overseas employment
Foreign currency income
Pre-return applications
Many lenders require applicants to be UK-based or already paid in sterling, while others apply heavy discounts to foreign income or insist on a confirmed UK contract before proceeding.
In this case, the client’s income was denominated in USD and paid overseas, and the application needed to be assessed ahead of physical relocation, creating potential friction around income sustainability and currency risk.
Without careful lender selection, borrowing options would have been severely restricted or delayed.
Lender Strategy
Lenders were assessed based on their approach to returning expatriates, foreign currency income, and pre-arrival applications.
Income was positioned using a conservative exchange-rate approach, with affordability modelled on sustainable base earnings and supported by bonus history where appropriate. The client’s seniority, employment continuity, and planned UK relocation timeline were clearly documented.
Several lenders were ruled out early due to rigid requirements around UK payroll or sterling-only income. A lender with an established framework for returning expatriates and overseas-paid professionals was selected, allowing the application to proceed without requiring UK employment to have formally commenced.
What We Can Do for You
Structure foreign currency income for UK lender assessment
Support mortgage applications before physical relocation
Navigate lender policy differences for returning expatriates
Package complex income clearly to minimise underwriting friction
The Result
A residential mortgage of £950,000 was approved at 65% loan-to-value, supporting the purchase of a £1.45m London apartment ahead of the client’s return to the UK.
The application progressed smoothly, allowing the client to secure a long-term home without relying on temporary accommodation or delaying the purchase until after relocation.
Why This Matters for Similar Clients
Returning expatriates often assume that a UK mortgage cannot be secured until they are back in the country or paid in sterling. In practice, lender selection and how overseas income is presented are far more important than physical location at the time of application.
With the right structure, foreign currency income can be assessed sensibly, allowing purchases to proceed before relocation rather than being deferred.
Request your fee free mortgage consultation today. No obligation, just sound advice.
FAQs
-
Yes, some lenders will consider foreign currency income, often applying conservative exchange-rate assumptions and focusing on sustainability rather than headline earnings.
-
Not always. Certain lenders are comfortable assessing applications pre-arrival, provided relocation plans and employment continuity are clearly evidenced.
-
Approaches vary. Some lenders will include bonuses subject to history and consistency, while others focus primarily on base income.
-
This depends on lender policy. Some lenders require a UK contract, while others are comfortable relying on existing overseas employment if a return is planned.
Related Case Studies
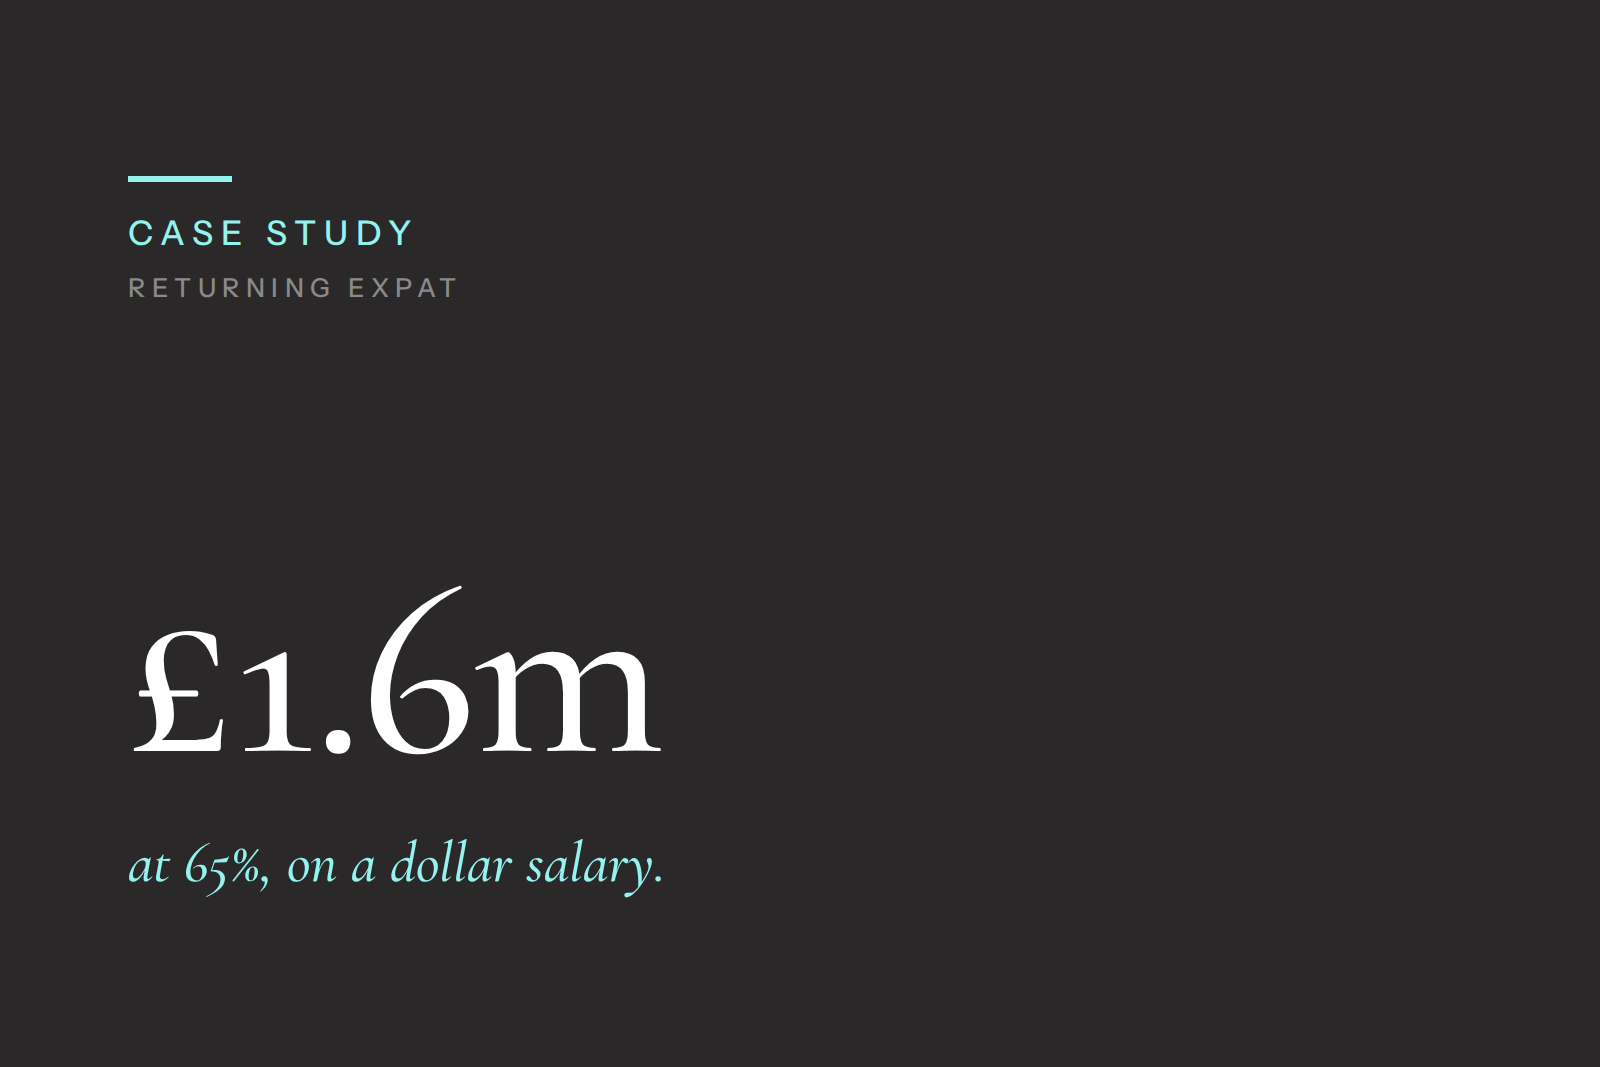
17 Mar - Written By David Walsh
YOUR HOME MAY BE REPOSESSED IF YOU DON’T KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
APPROVED BY THE OPENWORK PARTNERSHIP ON 02/02/2026