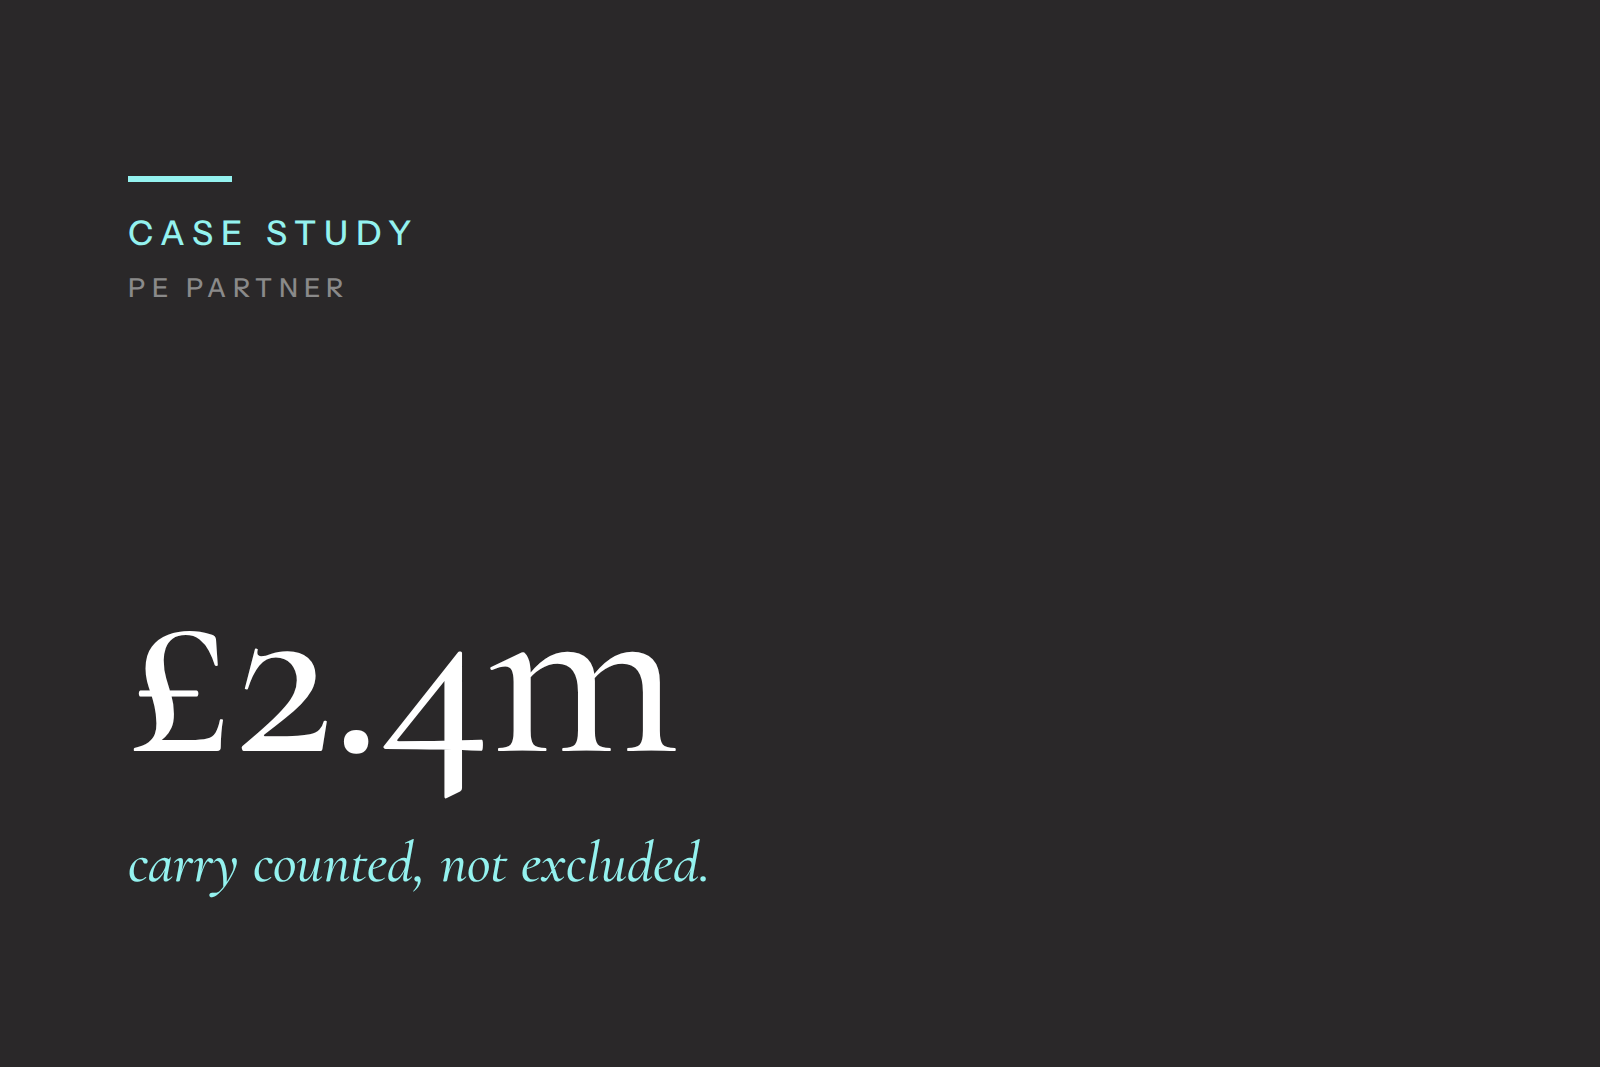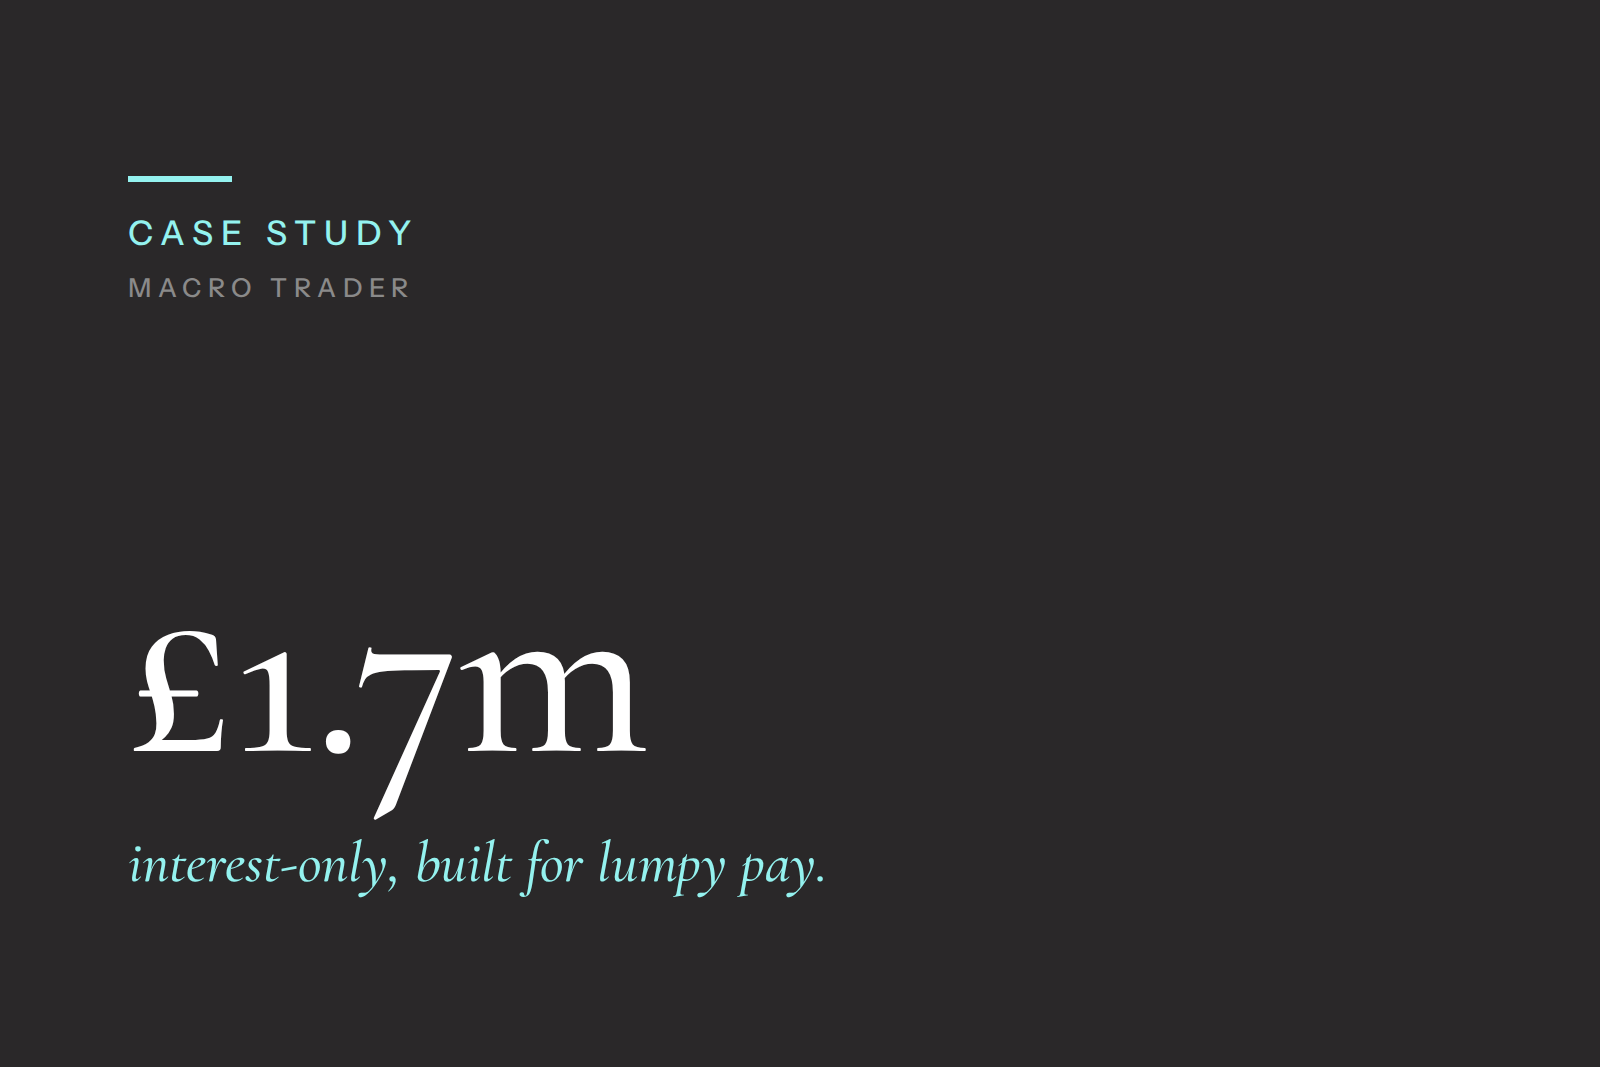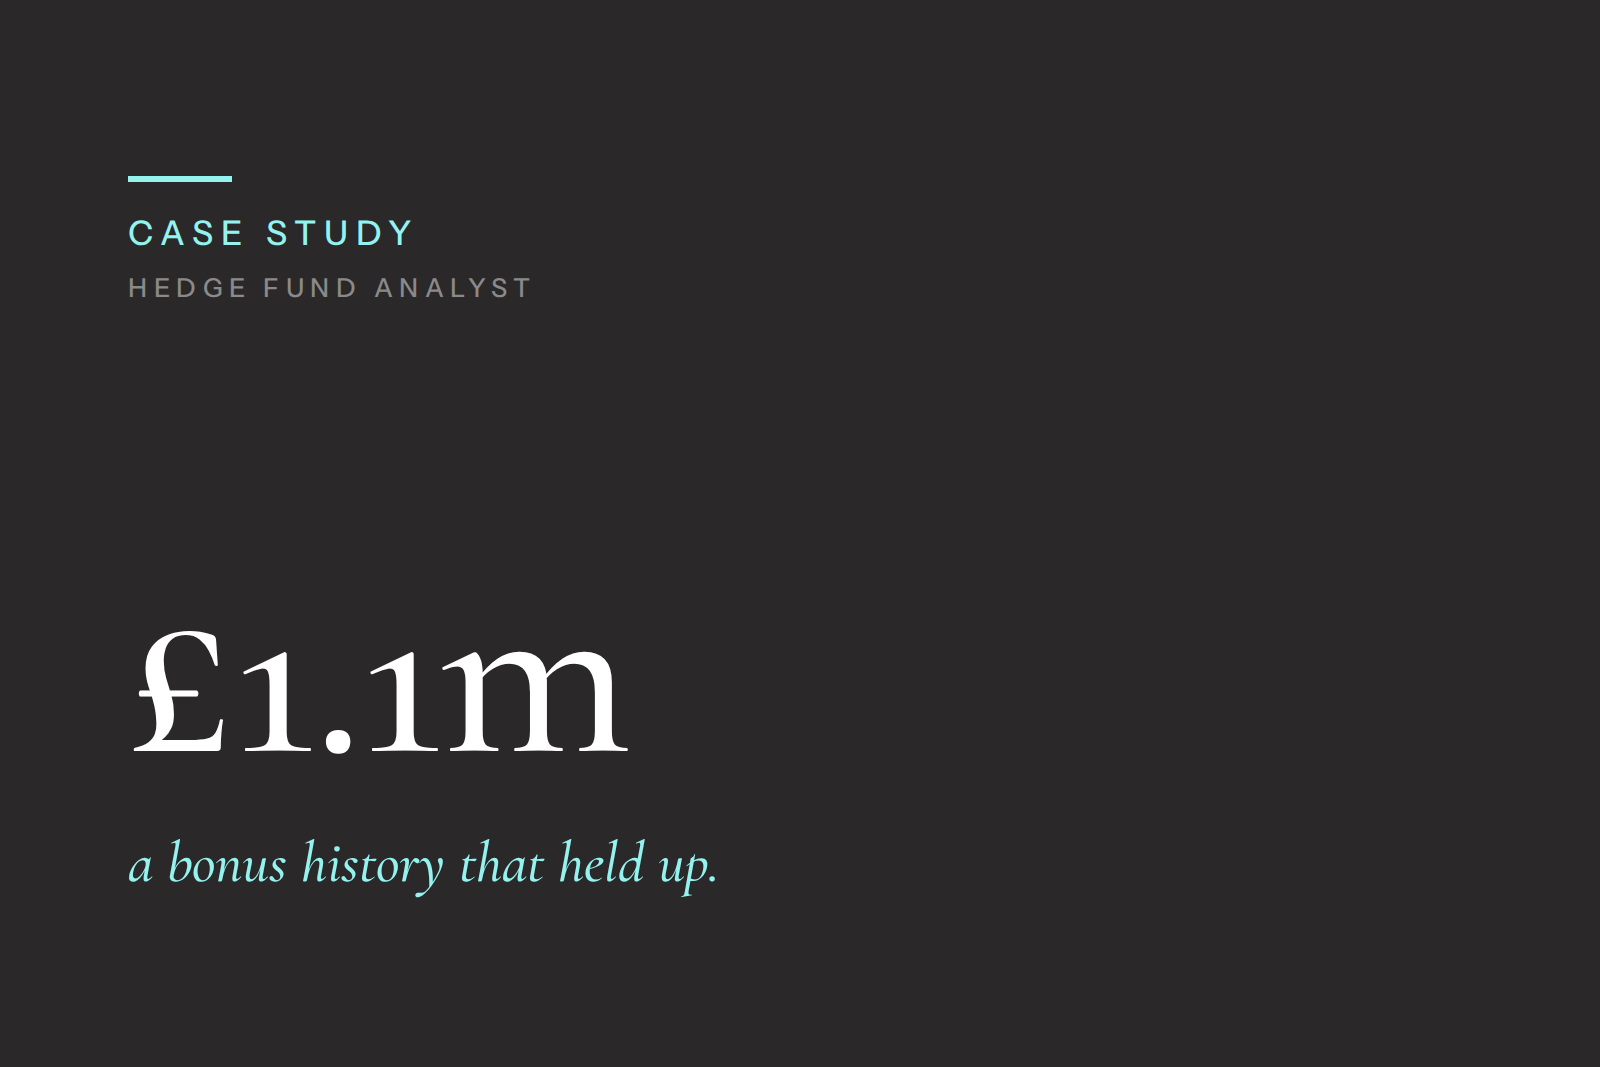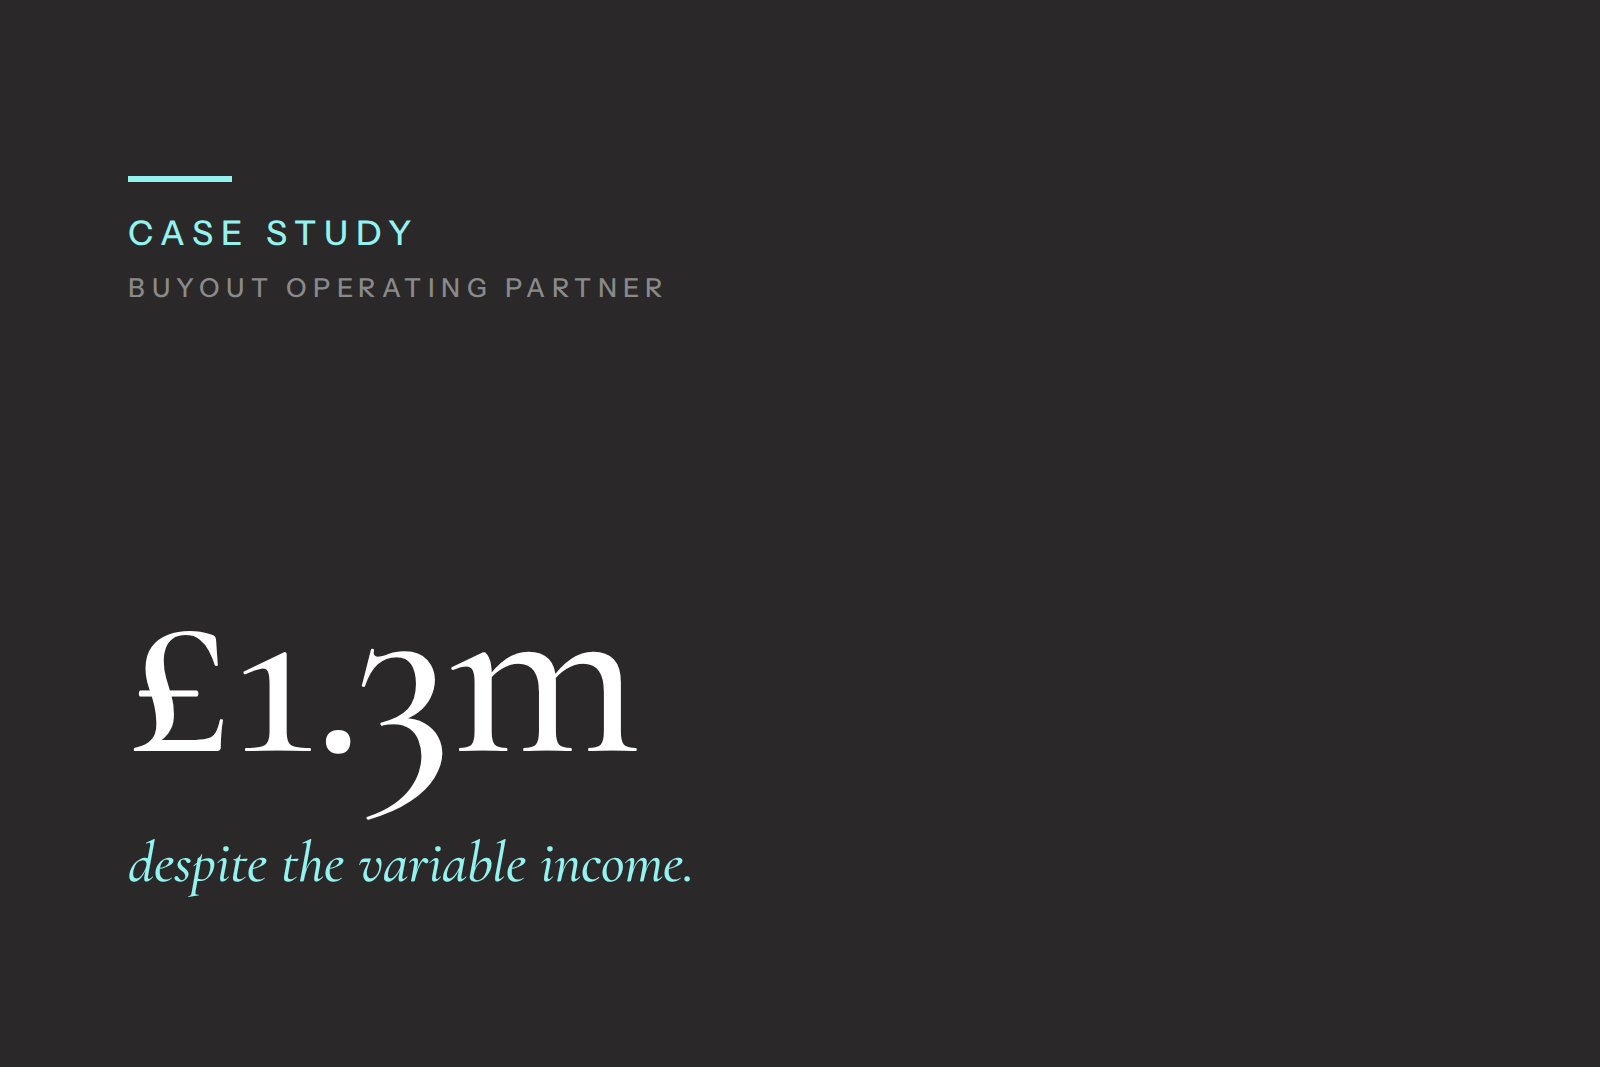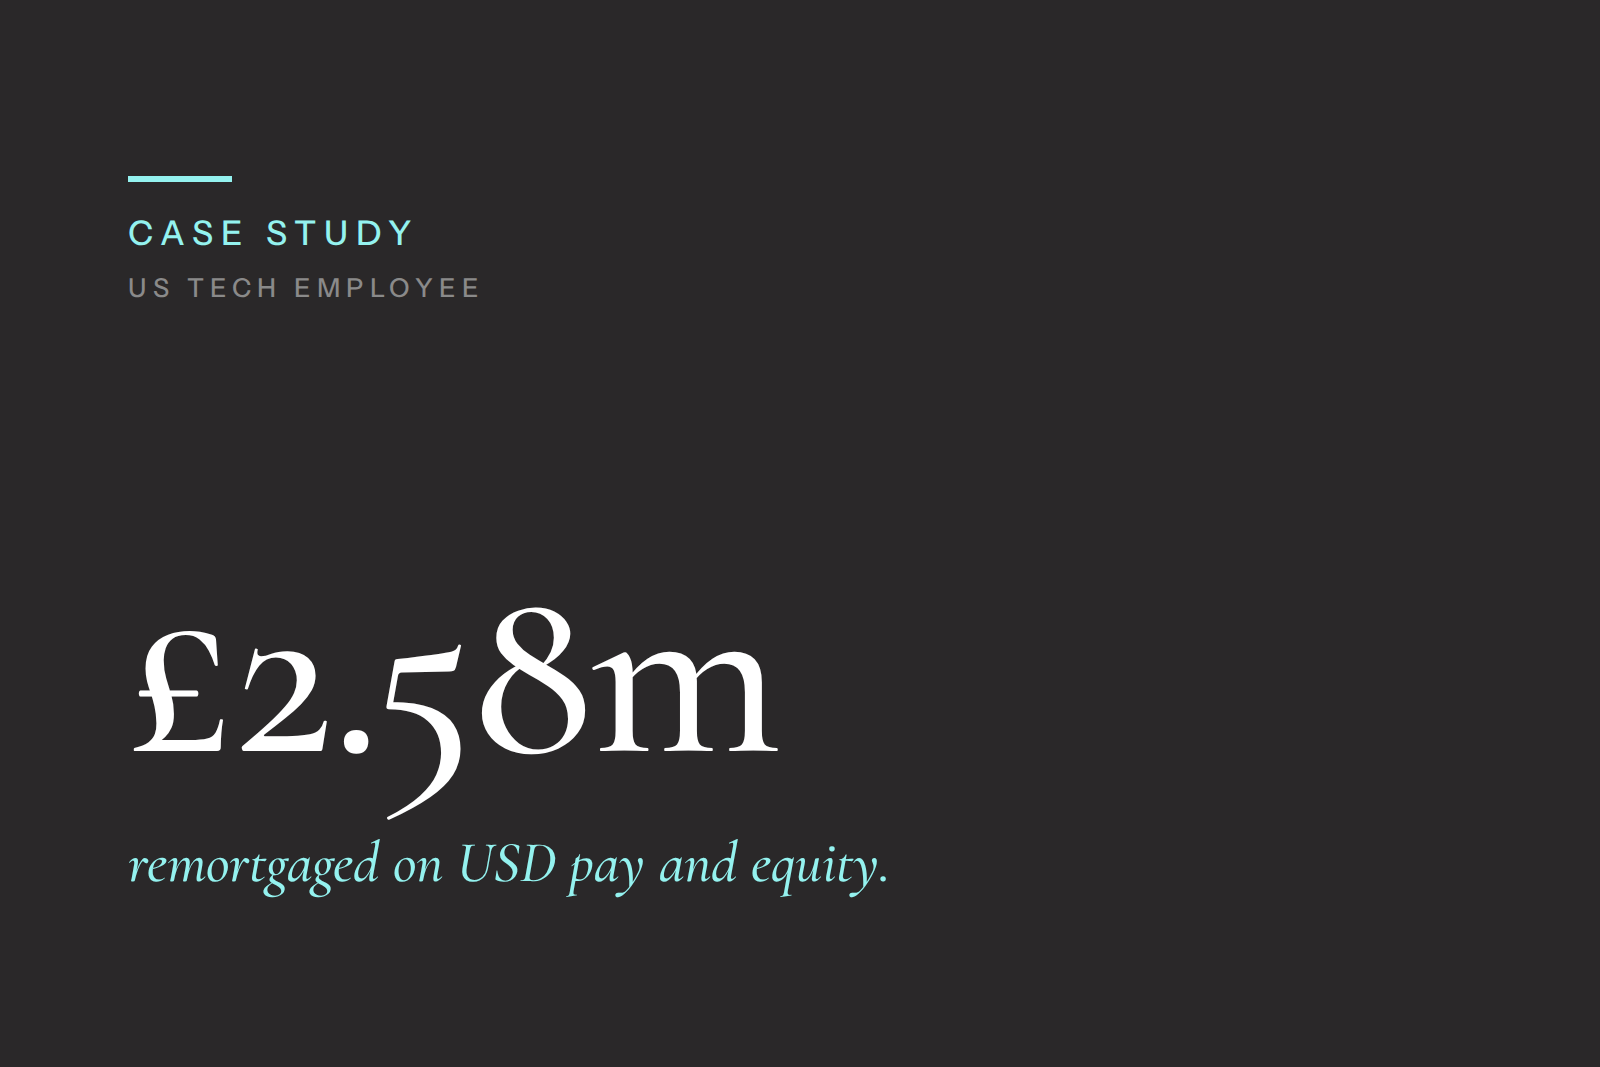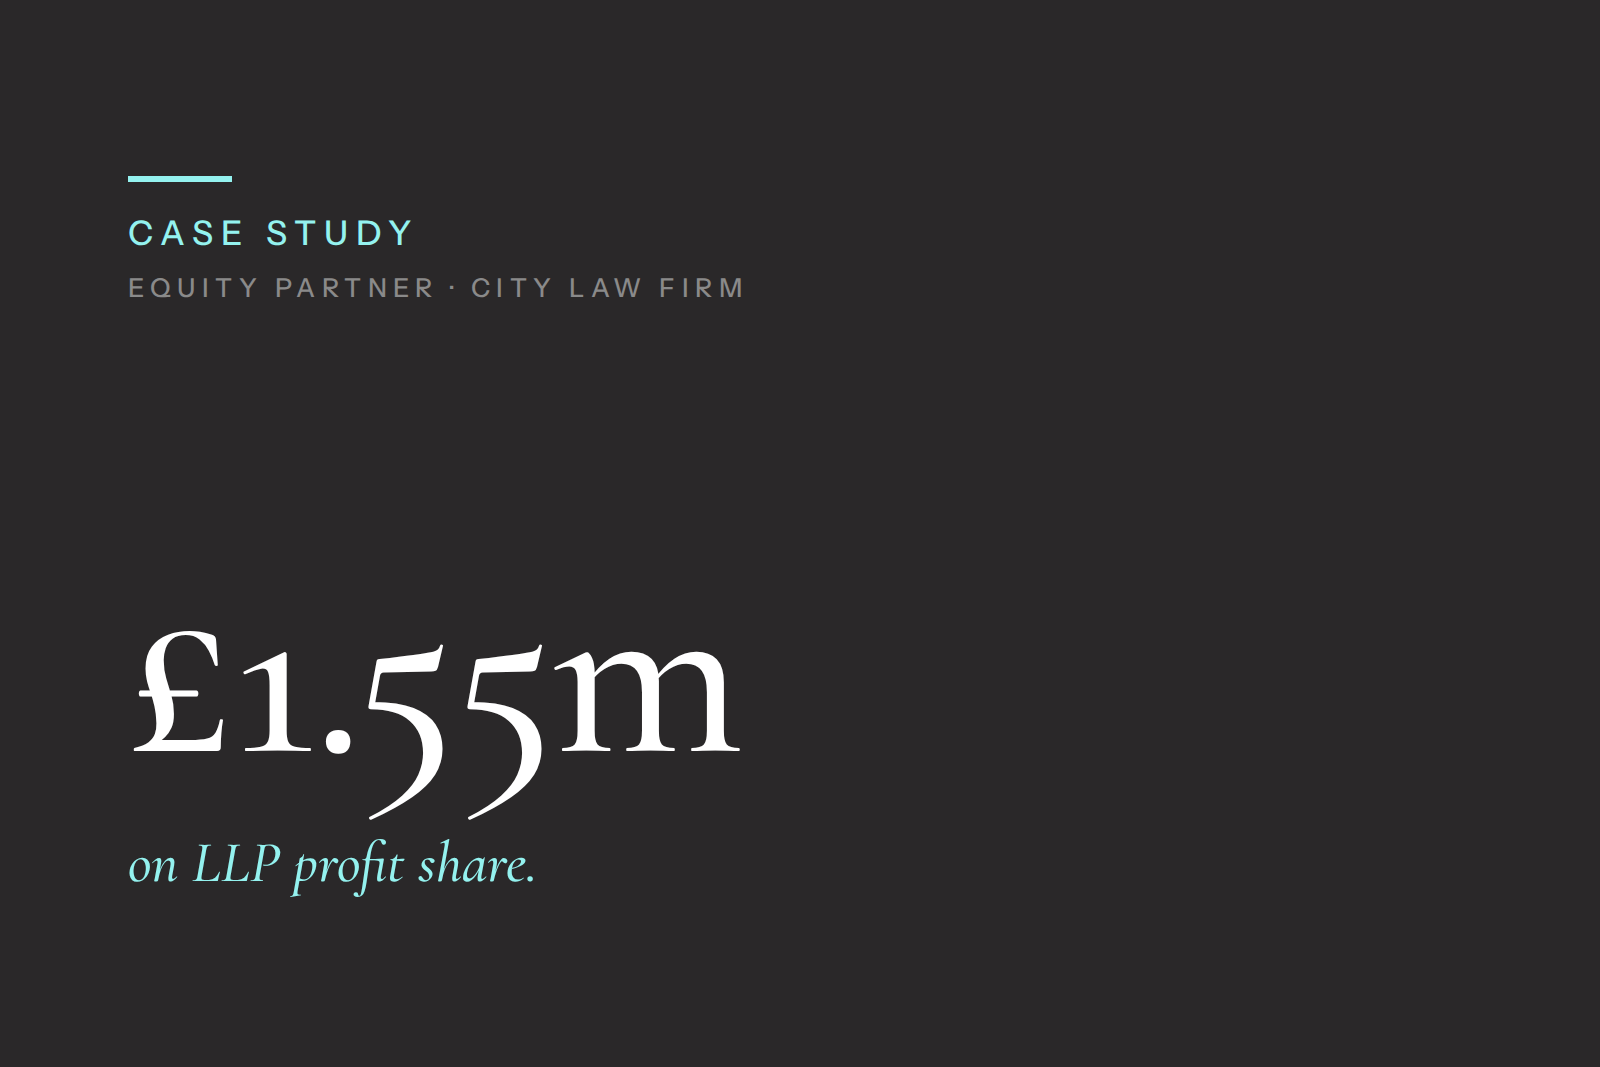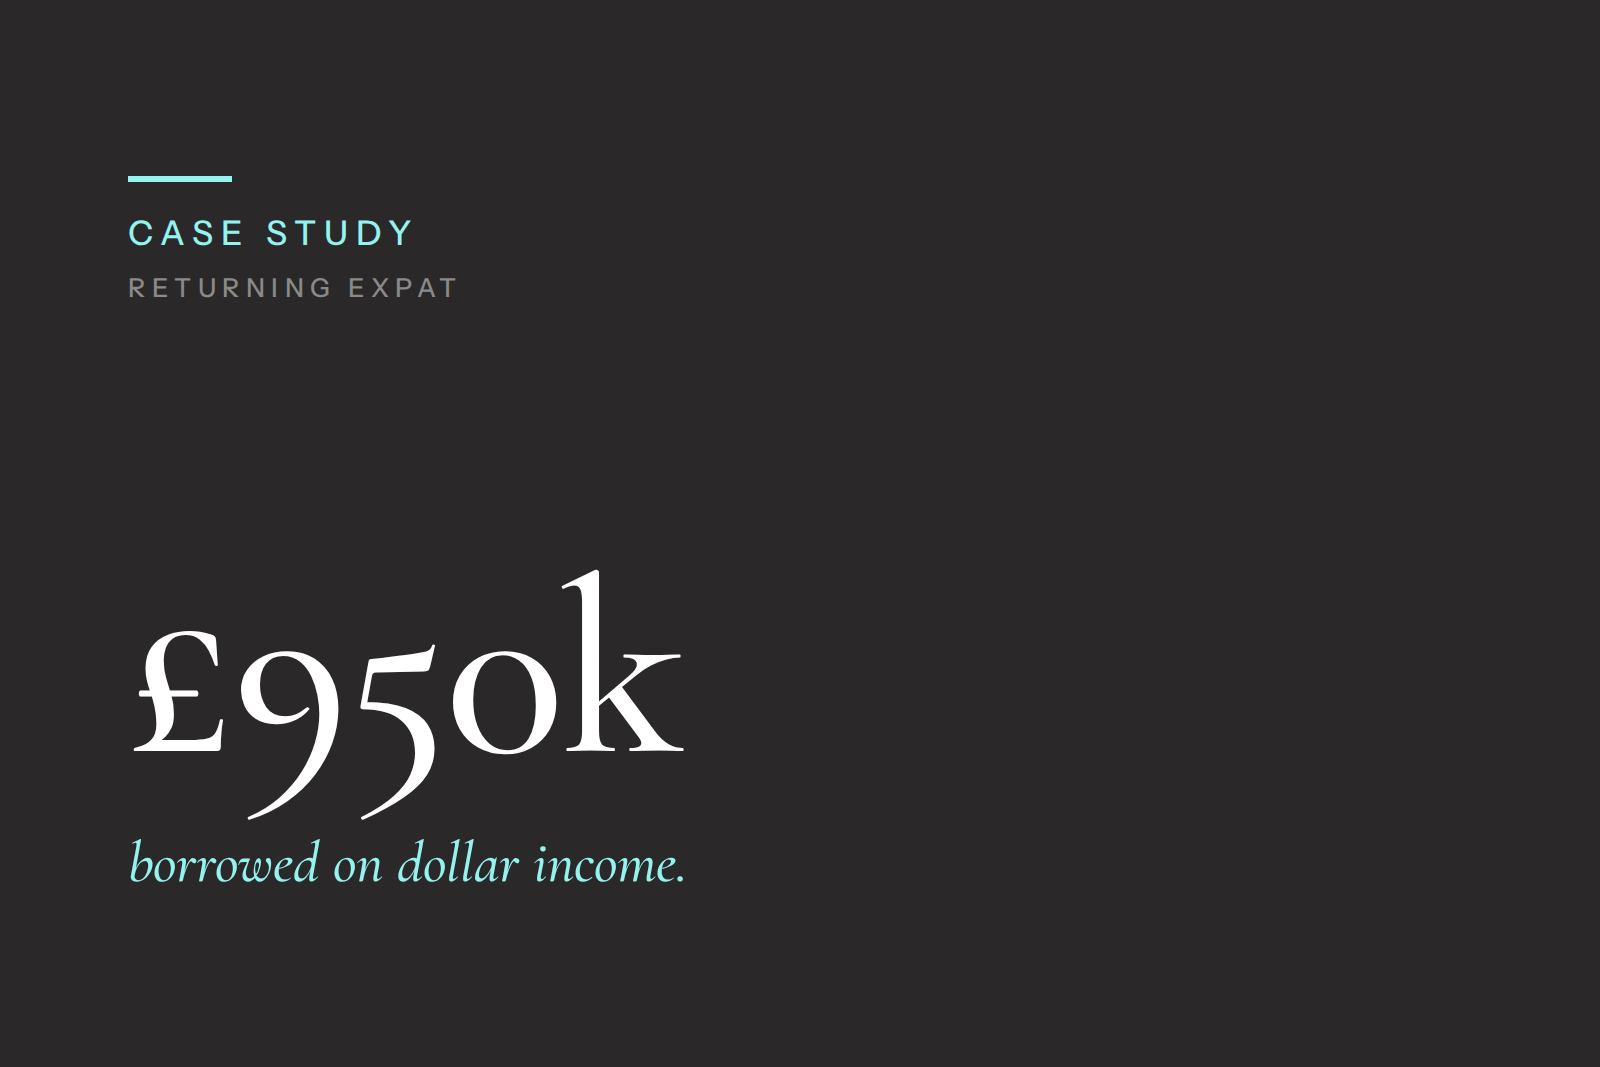Private Bank vs High Street Lenders: Which Is Better for You?
DIRECTOR AND MORTGAGE ADVISER
Specialist broker for high-earning professionals and complex income cases.
If you're a high-earning professional, partner, or entrepreneur, the question isn’t just “Can I get a mortgage?”—it's “Who should I get it from?”
For many, the choice comes down to private banks vs high street lenders. While both can offer competitive mortgage products, their approach to underwriting, income assessment, and flexibility varies significantly.
Here’s how to decide which option is right for your situation.
Request your fee free mortgage consultation today. No obligation, just sound advice.
What’s the Difference Between a Private Bank and a High Street Lender?
High Street Lenders
Include well-known retail banks like HSBC, Barclays, Nationwide, and Santander. These lenders:
Offer fixed, tracker, and interest-only mortgages at competitive rates
Use standardised criteria based on payslips, P60s, and credit scores
Often limit borrowing to 4.5–5x income
May struggle with complex or variable income structures
Private Banks
Include lenders like Coutts, Handelsbanken, Investec, or C. Hoare & Co. These banks:
Take a holistic view of your income, assets, and long-term potential
Offer tailored lending based on total wealth, not just salary
Are ideal for high-value mortgages or complex income profiles
Typically require assets under management (AUM) or a wealth relationship
When a High Street Lender Is the Right Fit
You may be better suited to a mainstream lender if:
You have a straightforward income structure (e.g. PAYE or two years’ self-employed history)
Your mortgage is under £1 million
You’re looking for the lowest headline rate with minimal strings attached
You want a fast, digital application process and don’t require bespoke structuring
High street lenders are efficient, well-priced, and often more appropriate for simpler borrowing needs.
How We’ve Helped Clients Like You
These clients faced similar challenges - here’s how we helped them secure the right deal.
An American VP on a Skilled Worker visa, 18 months into a London posting, needed £900,000 for a £1.2m house. A large international bank whose criteria let income override residency recognised £238,400 including his USD bonus; completed at 75% LTV.
A PE Partner refinancing £2.4m on a £3.2m home saw mainstream calculators read his carry as zero. A holistic underwrite credited a smoothed share of four years of distributions and the refinance completed interest-only at 4.8x recognised income.
A macro trader earning a £200k base with a bonus that swung between £180k and £420k needed £1.7m for a £2.3m family home. A clearing bank averaging three full years recognised £386,000 of income and agreed the loan interest-only at roughly 4.4x.
A hedge fund analyst on a £150k base needed £1.1m for a £1.4m home after his bonus fell to £120k from £270k. A lender applying 60% of a two-year average recognised £267,000 of income, and the loan completed at roughly 4.1x with the deposit unchanged.
An operating partner at a mid-market buyout firm needed £1.3m on a £1.7m home, with income spread across fixed drawings, board fees and a volatile profit share. Built on the stable layers at roughly 4.4x, it completed on mainstream large-loan terms.
A mid-market PE director needed £1.6m for a £2.1m home; salary and bonus reached £1,425,000 at most. A private bank recognised three years of crystallised co-investment gains, taking recognised income to £375,000 and the loan to roughly 4.3x.
A sole director drawing £90k while his company retained its profit needed £1.2m of borrowing. A lender assessing salary plus share of net profit after corporation tax recognised £267,570 of income, and the loan completed at just under 4.5x with no change to his dividends.
An investment banking Director secured a £990k mortgage on a £1.1m London flat at 90% LTV using multi-year bonus income. This case study shows how bonus averaging supported borrowing while retaining funds for property works.
A private equity VP secured a £1.9m mortgage on a £2.4m family home using salary and bonus income. This case study shows how part interest-only structuring and a five-year product aligned borrowing with future carry payments.
A UK-based employee of a US technology firm secured a £2.58m remortgage using USD salary, bonus, and RSUs. This case study explains how equity compensation and foreign currency income were assessed through a private banking solution.
An equity partner at a City law firm secured a £1.55m mortgage on a £1.85m family home using LLP income. This case study shows how part interest-only structuring supported affordability during a period of higher household costs.
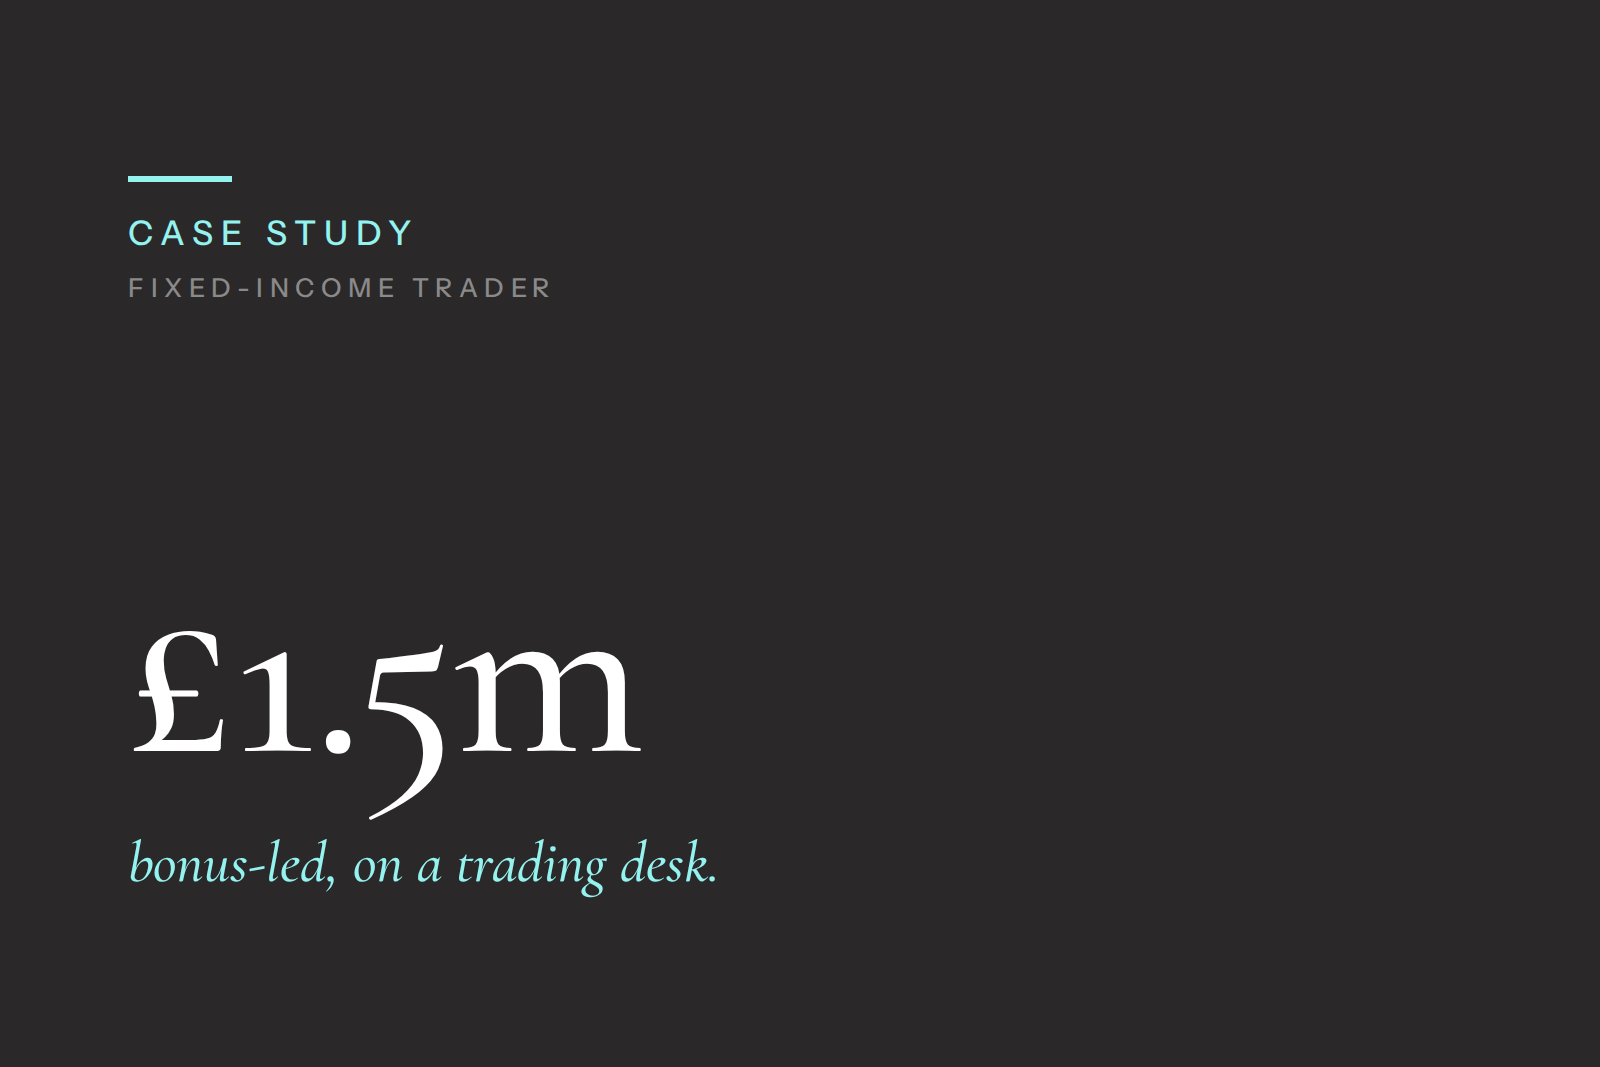
A fixed-income trader secured a £1.5m mortgage on a £2.1m purchase using bonus-led income. This case study explains how lender selection and income structuring supported affordability despite restrictive bonus caps.
A senior finance professional returning from Singapore secured a £950k UK mortgage on a £1.45m London apartment using overseas USD income. This case study explains how foreign currency income was assessed ahead of UK relocation.
An established equity partner at a UK law firm secured a £2.25m family home using fixed drawings and partnership profit share. This case shows how lender selection and part interest-only structuring supported uneven income and long-term affordability.
HNW client, strong liquid assets but modest declared income, needed £3m for a £5m townhouse. We placed assets under management, built an asset-based underwrite and used an investment portfolio as the repayment plan—securing a bespoke interest-only facility at 60% LTV.
Newly qualified solicitor on £110k, buying a £750k flat while in probation. We targeted a lender that may accept a signed contract and start date, leveraged a strong deposit, and packaged the case cleanly—securing an offer before probation completed.
Locum consultant doctor with £140k mixed NHS/private income secured a £770k mortgage on a £1.2m home. We used 12–24 month averaging, full contract history and locum-friendly criteria to align with a mainstream lender—delivering a clean, timely approval.
Director–shareholder, £60k salary and £120k retained profits, needed £1m borrowing without ramping dividends. We targeted a lender that may use salary + share of net profit, evidenced sustainability, and explained a one-off expense—achieving approval at an effective 5× multiple.
Management consultant contractor on £650/day (PSC), two-month gap, and IR35 scrutiny. We used day-rate modelling, a credible gap narrative, and an accountant’s letter to align with mainstream policy—achieving approval at 75% LTV on a £1.1m home.
Returning British expat paid in USD, thin UK credit, and a 60-day deadline. We secured a lender that accepts foreign income with a haircut, used a US credit report, and ran a pre-arrival application—agreeing the mortgage at 65% LTV on a £1.6m home.
Skilled Worker and Spouse visa clients, £160k income, <18 months in the UK, needed a fast new-build purchase at £800k. We shortlisted a lender comfortable with shorter residency, secured a rapid AIP, perfected the AML trail—and achieved a full offer inside 10 working days.
A senior software engineer on £95k with quarterly RSU vesting bought a £900k house. By averaging 12–24 months of vested RSUs and packaging award letters, brokerage statements and payslips, we evidenced sustainable equity income—resulting in approval with a part interest-only structure.
An investment banking associate on £120k base with a USD bonus needed 75% LTV on a £1.25m flat. We used a two-year average bonus, applied a foreign currency haircut, and built a strong evidence pack—resulting in c.5.2× income and a successful offer.
A City lawyer and LLP partner with £420k variable profit share bought a £2.1m London family home at 60% LTV. We targeted a lender that may average three years’ profits, clarified the capital account, and structured part interest-only with an evidenced repayment plan.
With renewals and short gaps, this IT contractor needed day‑rate treatment. We evidenced continuity, explained the gaps, and matched them with a lender that assesses on day‑rate—securing borrowing aligned to realistic annualised earnings.
A newly qualified solicitor with limited employment history needed clarity and pace. We used her offer letter and first payslips, applied professional‑criteria know‑how, and packaged a clean, conservative case—helping a mainstream lender say yes without over‑promising.
Briefs, arrears, and variable fee sheets—this barrister’s earnings were anything but tidy. We evidenced sustainability and secured a suitable mortgage at pace—without over‑promising.
A senior partner had to choose between a private bank and a high‑street lender for £2m. The private bank’s full interest‑only structure won—keeping monthly payments steady and letting annual profit share reduce the balance without hassle.
A newly made‑up equity partner needed a high‑value mortgage against uneven drawings and profit share. We evidenced sustainability, clarified tax and capital contributions, and matched them with a lender that considers partner income—without overstretching.
An IT Sales Director and Teacher with two children needed £800k to upsize to a £1.2m home. We secured 5.5x income using 100% of bonuses and structured part of the loan on interest-only — keeping monthly payments affordable with a plan to reduce the balance using future bonuses.
When a Private Bank Makes Sense
A private bank may be the better route if you:
Have a complex income structure (e.g. RSUs, carried interest, drawdowns, multiple income sources)
Need to borrow £1m+ or exceed standard income multiples
Are a non-UK resident, foreign national, or have overseas assets
Want to include assets or investment income in affordability
Require a bespoke mortgage structure (e.g. interest-only with an offset, bullet repayment, or tailored repayment schedules)
Private banks are particularly valuable for professionals in law, finance, tech, or business who earn well but don’t fit into a standard box.
Speak To An Expert Today
Get in touch for a fee free, no-obligation chat about how we might be able to help you.
Rates, Fees, and Flexibility: What to Expect
Rates: Private banks can be competitive, but not always cheaper. They often match or beat high street rates for large loans—especially when AUM is involved.
Fees: Expect higher arrangement or management fees. Some banks reduce or waive these with a wider wealth relationship.
Flexibility: This is where private banks shine—allowing bespoke repayment structures, flexible underwriting, and asset-backed lending unavailable elsewhere.
Speed: Private bank processes can be slower and more relationship-driven. But they excel when standard routes fail due to income complexity.
How to Choose the Right Lender for You
Start by assessing your profile:
Loan size: Under £1m? High street may be more cost-effective.
Income type: PAYE or simple self-employed? High street. Complex income or assets? Consider private banks.
Timeframe: Need speed? High street lenders often win.
Flexibility needs: Want interest-only beyond age 65, or offset from retained profits? A private bank can deliver.
Relationship value: Are you open to placing savings or investments with the lender? That could unlock better terms.
And most importantly—work with a broker. Many private bank deals are not advertised, and access is only available through intermediaries.
FAQs
-
Not necessarily. On large loans, their rates can be extremely competitive—especially with assets under management.
-
No. Many private banks support mortgages from £750k–£1m+ with flexible criteria. Wealth requirements vary.
-
Yes. Many clients remortgage to a private bank once their assets or income become more complex.
-
Not harder—but more bespoke. You’ll need full transparency on your income, assets, and goals.
Conclusion: It’s Not Just About the Rate
Choosing between a high street lender and a private bank comes down to more than numbers. It’s about who understands your full financial picture—and can offer a mortgage that fits not just your income, but your future.
Need help deciding which route suits your situation?
We specialise in helping professionals and partners access tailored mortgage options—whether from a high street bank or a private lender.
Request your fee free mortgage consultation today. No obligation, just sound advice.
Related Articles
Two lenders can look at the same banker's P60 and reach borrowing figures hundreds of thousands of pounds apart. The difference is rarely the income. It is how each lender treats the bonus: how much of it counts, how it is averaged, and whether the deferred portion registers at all. Here is how the assessment varies across the panel.
Carry doesn't arrive in neat annual instalments. It lands deal by deal, clusters in realisation years, and goes quiet in between, and a mortgage model built for regular pay reads that shape badly. The question is rarely whether your carry is real. It's whether the pattern has been evidenced, and the application timed, so a lender can use it.
Operations and business-side pay at a hedge fund is often more legible to a lender than a portfolio manager's, yet the discretionary bonus and the deferred element still decide how much you can borrow. Here is how mainstream lenders read a non-front-office income, and where a specialist changes the outcome.
A quant's pay rarely looks like a payslip. A share of strategy profit, deferred awards split between cash and fund units, a base that is a fraction of the total, and a lender model built for salary. How much of that income actually counts, and why the same numbers can swing borrowing by a six-figure margin.
You earn well, so you will probably be fine. But "fine" can leave a lot of borrowing on the table. The same payslips can produce very different numbers depending on the lender, how your bonus is presented, and your deposit. These are the levers that actually move a lawyer's borrowing power, and when each one is worth pulling.
You pay yourself a modest salary and leave the profit in the company, which is tax-efficient and quietly makes you look like a low earner to a high street lender. The income is there. Whether a lender can see it depends on how it reads your accounts, and that varies more than most directors expect.
For hedge fund professionals, the variability of performance-linked pay isn't what limits mortgage borrowing — lender methodology is. The same P60 can produce borrowing figures that differ by over £500k depending on how each lender averages your bonus, caps it, and reads a down year.
Your co-investment is real money, but a mortgage lender may not see it. A capital call isn't a credit commitment, so it may not be on a credit search and you have no obligation to declare it. The work of a specialist broker is asking the questions a lender may not, and structuring borrowing so liquidity is there when calls land.
You earn well, so why does the mortgage offer capture a fraction of it? With hedge fund pay the problem is rarely the amount. It's that the right answer depends on which lender, applied for when, through which route. That's what structuring means, and why a generalist misses it.
As a PAYE associate you'll probably be fine, but "fine" understates it. Your base is taken at face value; your bonus is where lenders disagree, sometimes by hundreds of thousands of pounds of borrowing power. This is how associate income is actually assessed, and where the right lender choice changes the number.
Buying your first UK home after years overseas combines two profiles lenders rarely see together — first-time buyer and returning expat. Standard FTB rates and 95% LTVs are still on the table, but only at the right lender, and only if your credit, currency, and SDLT position have been read correctly before submission.
Your total compensation and your assessed income are rarely the same number. For City professionals, the gap between what you earn and what a lender will count — and at what percentage — is often the difference between the mortgage you want and the one you're offered.
Restricted Stock Units (RSUs) can significantly increase what you're able to borrow — but many mainstream lenders either exclude them or apply steep discounts. The lender you choose, and how your equity income is packaged, can sometimes make a difference of hundreds of thousands of pounds in borrowing power.
Loan sizes in seven figures need a different conversation. This guide covers how private banks and specialist lenders actually underwrite HNW cases — asset-based affordability, AUM, interest-only structuring, and complex income — plus how to know which route is right for your profile.
The rate on a professional mortgage is often identical to a standard deal. The difference shows up in how much you can borrow, how lenders treat variable income, and which structures they'll offer. That gap can be worth far more than a few basis points.
As an LLP partner you're treated as self-employed by every mainstream lender, even when your income is more reliable than most PAYE roles. Some lenders default to needing two years of tax calculations — others will lend on day one of partnership. The difference can be hundreds of thousands in borrowing power.
Mortgage affordability for markets professionals often extends beyond payslips and P60s. This article explains how lenders assess bonus-led and complex income, and why documentation alone rarely tells the full story.
Private equity income rarely fits standard mortgage models. This article explains why salary, bonus, and carry are treated differently by lenders and when specialist mortgage structuring is often required.
Foreign currency income often causes confusion when applying for a UK mortgage. This article separates common myths from reality and explains how lenders assess overseas income, currency risk, and affordability.
Bonus income plays a major role in mortgage affordability for investment bankers. This article explains how bonuses are typically calculated by lenders, why averaging and caps apply, and what factors influence borrowing capacity.
Equity compensation can complicate mortgage affordability. This article explains how RSUs are typically assessed, why some lenders exclude them, and what factors influence whether equity income is considered.
Becoming a partner doesn’t automatically make mortgages easier. This article explains how lenders assess newly promoted partners, what changes after promotion, and why income structure often matters more than job title.
Traders and structurers are often assessed conservatively for mortgages due to variable bonus income. This article explains why standard income models can fail to reflect front-office compensation and what typically drives lender affordability decisions.
Maximum borrowing isn’t always the best outcome for high earners. In this article, we explain why many professionals choose flexibility, cash-flow resilience, and future options over pushing affordability to its limit.
London prices stretch affordability. A JBSP (Joint Borrower, Sole Proprietor) lets family boost borrowing without going on the deeds. Learn who it suits, how lenders may assess it, risks for helpers, and clean exit strategies—plus alternatives like gift, JBSP+offset, or family springboard.
Bonus-heavy or RSU-led pay doesn’t have to derail your remortgage. Learn how lenders may treat variable pay and vesting equity, what typically counts, and the documents that help—plus a clean packaging strategy, worked example, and risk controls.
Multiple income streams? This guide shows how lenders may assess salary, bonus, RSUs and rental income together—what typically counts, common hurdles, and how to package your case so more of your genuine earnings may be considered, without overpromising.
Irregular income doesn’t have to mean uneven cashflow. See how offset mortgages can reduce interest, keep cash liquid for invoices and tax, and flex with day-rate or self-employed earnings—plus when lenders may consider it and how to set your accounts up for success.
Your deal is ending. Do you remortgage to a new lender or accept a product transfer with your current one? This guide compares pricing, fees, speed, affordability checks and extra borrowing—plus a simple decision framework and timeline so you choose with confidence.
On a Skilled Worker visa and buying in the UK? This clear guide shows what lenders may consider: time in the UK, months left on your visa, LTV caps, income and deposit rules, plus the documents that smooth approval—without overpromising.
YOUR HOME MAY BE REPOSESSED IF YOU DON’T KEEP UP REPAYMENTS ON YOUR MORTGAGE
Kite Mortgages is a trading style of Kite Financial Ltd which is an appointed representative of The Openwork Partnership, a trading style of Openwork Limited which is authorised and regulated by the Financial Conduct Authority.
APPROVED BY THE OPENWORK PARTNERSHIP ON 19/09/2025.